
Stethoscope Market Report Scope & Overview:
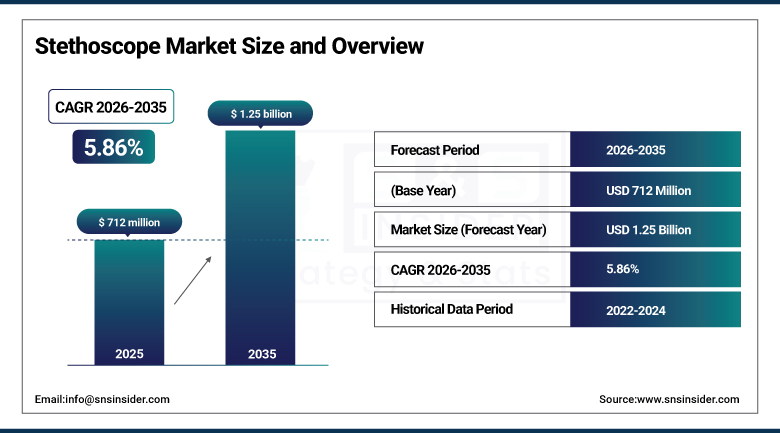
The Stethoscope Market was valued at USD 712 million in 2025 and is expected to reach USD 1.25 billion by 2035, growing at a CAGR of 5.86% from 2026–2035.
The stethoscope is among the most widely known symbols of medicine and, even after more than two centuries since its invention, it remains an essential tool in the daily lives of healthcare practitioners everywhere. The industry is changing drastically, with the adoption of digital and electronic stethoscopes becoming more widespread than their acoustic predecessors. The modern technology allows for sound amplification, noise reduction, sound recording, and even synchronization with smart devices such as phones and computers. Increasing incidence of heart and lung disorders ensures constant demand for stethoscopes in hospital wards, outpatient clinics, emergency rooms, and even home-based health care.
Cardiovascular disease remains the leading cause of death globally, with over 17 million deaths annually. Every physician, nurse practitioner, and paramedic who screens, diagnoses, or monitors heart conditions needs a stethoscope. This creates a large and stable baseline of demand that is unlikely to diminish regardless of other technology changes.
Market Size and Forecast
-
Market Size in 2026E: USD 753.72 Million
-
Market Size by 2035: USD 1258.34 Billion
-
CAGR: 5.86% from 2026 to 2035
-
Fastest Growing Region: Asia Pacific
-
Largest Region: North America
To Get more information on Stethoscope Market - Request Free Sample Report
Stethoscope Market Trends
-
Electronic and digital stethoscopes with noise cancellation and amplification are gaining market share from traditional acoustic models.
-
AI integration in digital stethoscopes is enabling automatic detection of murmurs, arrhythmias, and abnormal breath sounds.
-
Telemedicine is creating demand for digital stethoscopes with wireless transmission capabilities that can share recordings remotely.
-
Home healthcare growth is expanding the market for consumer-friendly stethoscopes and remote patient monitoring devices.
-
Medical education programs are adopting smart stethoscopes with recording and playback features for training purposes.
-
Wireless Bluetooth stethoscopes are making it easier to store and share recordings in electronic health records.
-
Growing prevalence of COPD, asthma, and heart failure in aging populations is sustaining demand for auscultation tools.
U.S. Stethoscope Market Outlook
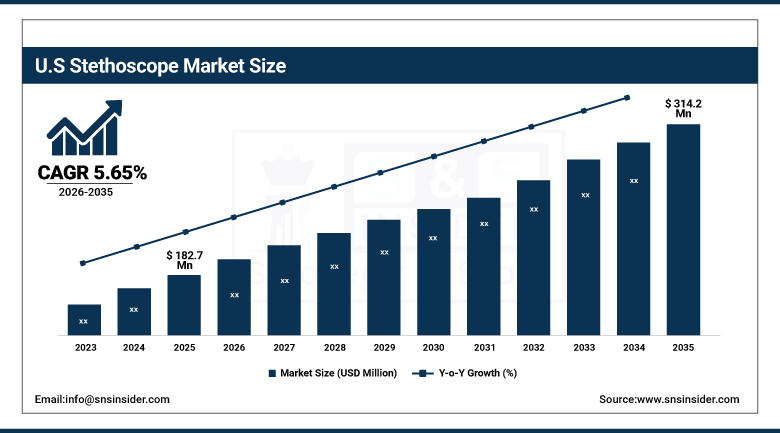
The U.S. Stethoscope Market was valued at USD 182.7 million in 2025 and is expected to reach USD 314.2 million by 2035, growing at a CAGR of 5.65% from 2026 to 2035.
The U.S. has a robust healthcare system that is an important market for the purchase of stethoscope variants such as digital versions. 3M Littmann and Eko Health, companies based in the U.S., are considered global market leaders for each variant of the stethoscope segment, respectively. Investments made to enhance primary care facilities and integrate telemedicine have opened up new markets. The U.S. is also ahead in using AI-enabled digital stethoscopes for detecting heart anomalies, which is the highest value segment in the market.
AI-enhanced digital stethoscopes like the Eko CORE 500 are particularly compelling in the U.S. context where physician time is expensive and shortage is significant. A tool that can help a primary care doctor flag a potential cardiac issue that might have been missed without specialist expertise has clear clinical and economic value.
Stethoscope Market Segment Insights
-
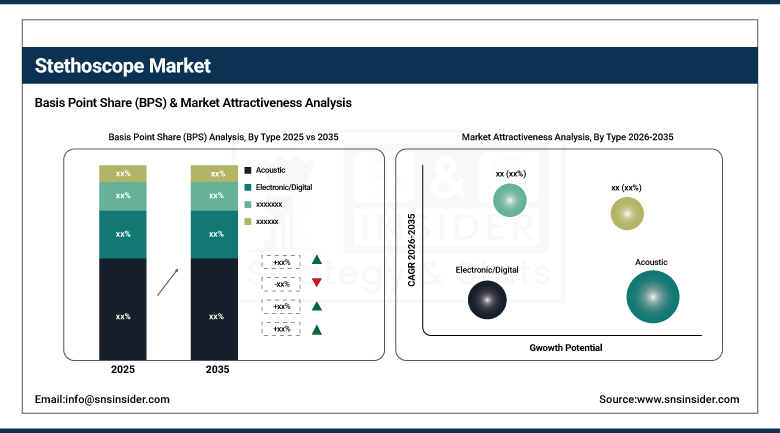
By Type, Acoustic Stethoscopes dominated the Stethoscopes Market with approximately 73.00% share in 2025, while Electronic/Digital Stethoscopes are the fastest growing with a CAGR of approximately 8.42% during 2026–2035.
-
By Application, Cardiology dominated the Stethoscopes Market with approximately 32.68% share in 2025, followed by Pulmonology with approximately 24.57% share, while Cardiology remains the largest clinical application.
-
By End Use, Hospitals and Clinics dominated the Stethoscopes Market with approximately 67.84% share in 2025, while Home Healthcare is the fastest growing segment with a CAGR of approximately 9.16% during 2026–2035.
By Type, Acoustic Leads, Digital Growing Fastest
The Acoustic Stethoscopes segment dominated the Stethoscopes Market in 2025, owing to their widespread use as a standard diagnostic tool across hospitals, clinics, emergency care facilities, and medical education institutions. Their simple construction, affordability, durability, and ease of use make them accessible across both developed and emerging healthcare markets. Acoustic stethoscopes also require minimal maintenance and do not depend on batteries or electronic components, supporting their continued adoption among physicians, nurses, and other healthcare professionals. Their established role in routine physical examinations and cardiovascular and respiratory assessments further reinforces their leading position.
The Electronic/Digital Stethoscopes segment is growing at the highest CAGR, driven by increasing demand for enhanced auscultation capabilities and digital healthcare technologies. These devices can amplify heart and lung sounds, reduce background noise, record auscultation data, and support digital transmission for remote consultations. Integration with smartphones, electronic health records, artificial intelligence, and telemedicine platforms is further expanding their clinical utility. Growing interest in remote patient monitoring and AI-assisted diagnosis is encouraging healthcare providers to adopt connected diagnostic devices, while technological improvements and declining device costs are gradually making digital stethoscopes more accessible.
By Application, Cardiology Biggest, Pulmonology Consistent
The Cardiology segment dominated the Stethoscopes Market in 2025, reflecting the essential role of auscultation in evaluating cardiovascular function and identifying abnormal heart sounds. Stethoscopes remain routinely used for detecting murmurs, irregular rhythms, and other cardiac abnormalities during physical examinations. Rising cardiovascular disease prevalence is increasing the volume of cardiac assessments across hospitals, clinics, and outpatient settings. Continued emphasis on early diagnosis and routine cardiovascular screening is also sustaining demand for reliable auscultation devices. Advanced electronic stethoscopes are further enhancing cardiac applications through sound amplification, recording, and digital analysis capabilities.
Pulmonology represents another major application area, supported by the widespread use of stethoscopes for assessing respiratory sounds and identifying abnormalities associated with pulmonary conditions. Healthcare professionals routinely use auscultation to evaluate wheezing, crackles, diminished breath sounds, and other respiratory indicators. Growing respiratory disease burden, including asthma, chronic obstructive pulmonary disease, and respiratory infections, continues to generate demand for diagnostic assessment. Increasing adoption of digital and amplified stethoscopes is also improving the detection of subtle respiratory sounds, particularly in primary care and remote healthcare environments.
By End-Use, Hospitals Lead, Home Healthcare Emerging
Hospitals and Clinics dominated the Stethoscopes Market in 2025, as these facilities represent the primary settings for routine physical examinations, emergency assessments, inpatient monitoring, and specialist consultations. Stethoscopes are used extensively across cardiology, pulmonology, general medicine, pediatrics, and emergency care, creating broad institutional demand. High patient volumes and continuous diagnostic activity support recurring procurement and replacement requirements. Medical training programs and expanding healthcare infrastructure in developing markets further contribute to demand, while hospitals are increasingly evaluating digital stethoscopes that can support connected diagnostics and remote consultations.
Home Healthcare is an emerging fast-growing segment as healthcare delivery increasingly shifts toward decentralized and patient-centered care. Home-based monitoring allows healthcare professionals to evaluate patients outside traditional clinical environments, particularly elderly individuals and those requiring long-term disease management. The expansion of telemedicine and remote patient monitoring is creating opportunities for connected stethoscopes capable of transmitting auscultation data to clinicians. Growing demand for convenient healthcare access and reductions in hospital visits are supporting adoption. Technological improvements that make digital devices easier to operate and integrate with mobile platforms are expected to further strengthen the role of stethoscopes in home-based care.
Regional Analysis
|
Region |
Major Country |
Share within Region (%) |
|---|---|---|
|
North America |
United States |
77.00% |
|
Europe |
Germany |
30.00% |
|
Asia Pacific |
China |
44.00% |
|
Middle East & Africa |
UAE |
36.00% |
|
Latin America |
Brazil |
53.00% |
North America Stethoscope Market Insights
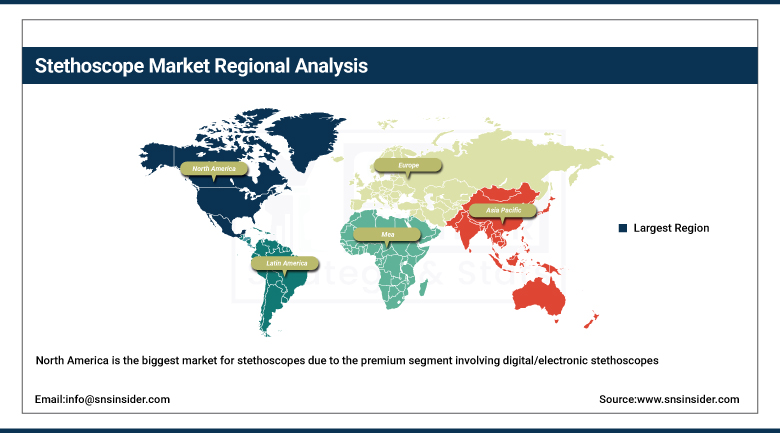
North America is the biggest market for stethoscopes due to the premium segment involving digital/electronic stethoscopes. North America has a higher density of health care practitioners and advanced use of medical equipment. Similarly, Canada has a highly developed health care system. This region is at the forefront in terms of integrating AI-enabled digital stethoscopes into their facilities.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Stethoscope Market Insights
The European stethoscope market is highly developed and stable owing to the existence of universal health care facilities in many countries such as Germany, France, Italy, and the UK. The medical universities in Europe graduate many doctors each year, and each of them needs a stethoscope as a part of their kit. There is also rising demand for advanced medical diagnostic equipment in the region.
Asia Pacific Stethoscope Market Insights
Asia Pacific is not only a high-volume market for low-cost acoustic stethoscopes but also a developing market for electronic stethoscopes due to increased investment in healthcare. The nations of China, India, and Southeast Asia are constructing primary care facilities that ensure steady demand. The healthcare system in Japan and South Korea is highly developed with widespread use of high-end medical equipment. India, with its large healthcare industry, is a particularly crucial market for diagnostic devices.
Middle East & Africa & Latin America Stethoscope Market Insights
The investment in healthcare infrastructure in the Middle East through initiatives such as the Vision 2030 program in Saudi Arabia and health services development initiatives in the UAE has brought about a constant need for various types of medical instruments like the stethoscope. The market size in Africa is high based on the sheer number of people in the region who have very minimal healthcare infrastructure. Acoustic stethoscopes are purchased in bulk by organizations such as the World Health Organization.
Latin America has a growing healthcare sector with significant needs in both urban hospitals and rural primary care. Brazil, Mexico, Colombia, and Argentina all have substantial markets. Brazil's large public health system (SUS) is a major institutional buyer. The region has a mix of demand for affordable acoustic models for primary care and higher-end electronic models for private hospital and specialist use. Medical education is expanding across the region, creating a consistent stream of new stethoscope purchasers.
Market Dynamics
Growth Drivers: Rising cardiovascular and respiratory disease burden drives sustained demand
The rate of occurrences of heart and lung diseases has continued to rise annually due to the aging population and increased occurrence of risk factors such as obesity, smoking, and lack of exercise. These types of illnesses need regular clinical checks that depend heavily on the use of stethoscopes. With the increasing number of people needing heart and lung assessments regularly, the number of times stethoscopes are worn increases accordingly.
Healthcare expansion in developing countries is a powerful structural growth driver. As governments in Asia, Africa, and Latin America invest in primary care networks, community health workers, and rural clinics, demand for affordable and reliable diagnostic tools grows proportionally. The stethoscope is typically one of the first purchases for any new clinical facility.
Restraints: Cybersecurity risks from digital devices and limited battery life concern some users
With the move to digitization and connectivity of stethoscopes, cybersecurity in the medical industry becomes another concern. The digital stethoscope which records the sounds of patients will have to conform to such policies like HIPAA and GDPR regarding data confidentiality. In addition, the risk of a cyber-attack exposing the data stored can cause great harm to the organization. The other challenge with digital stethoscopes is that they require frequent charges.
Opportunities: AI-powered cardiac screening for remote and underserved populations
There is an interesting application involving the use of AI-assisted digital stethoscopes to provide specialized cardiac screening in places where specialists such as cardiologists do not exist. With AI-based digital stethoscopes, one may be able to train a healthcare provider to detect valvular heart disease, which otherwise goes undetected in most African, Asian countries, as well as some other rural locations. Such innovations can make a considerable contribution towards public health and have immense potential in the market.
Recent Developments
-
2025: Eko Health launched its CORE 500 digital stethoscope with onboard AI that can detect atrial fibrillation, murmurs, and other cardiac abnormalities in real time during a clinical examination without requiring any specialist interpretation from the examining clinician.
-
2024: 3M Littmann launched the CORE Digital Stethoscope series with improved Bluetooth range, 40x sound amplification, and integration with the Eko app for recordings and telehealth consultations, expanding the capabilities of the world's most trusted stethoscope brand.
Stethoscope Market Key Players
-
3M Littmann Stethoscopes
-
Eko Health Inc.
-
Welch Allyn (Hillrom/Baxter)
-
American Diagnostic Corp.
-
Heine Optotechnik GmbH
-
Riester GmbH
-
Nasco Healthcare
-
Rudolf Riester GmbH
-
Prestige Medical
-
Ultrascope
-
Spirit Medical
-
Medline Industries Inc.
-
Suzuken Co., Ltd.
-
MDF Instruments
-
Think Labs Inc.
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 712 Million |
| Market Size by 2035 | USD 1.25 Billion |
| CAGR | CAGR of 5.86% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (Acoustic, Electronic/Digital, Fetal Stethoscope, Others) • By Application (Cardiology, Pulmonology, General Diagnosis, Others) • By End-Use (Hospitals & Clinics, Ambulatory Care, Home Healthcare, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | 3M, Eko Health Inc., Welch Allyn (Hillrom/Baxter), American Diagnostic Corp., Heine Optotechnik GmbH, Riester GmbH, Nasco Healthcare, Rudolf Riester GmbH, Prestige Medical, Ultrascope, Spirit Medical, Medline Industries Inc., Suzuken Co., Ltd., MDF Instruments, Think Labs Inc. |
Frequently Asked Questions
Leading companies include Robert Bosch GmbH, Ford Motor Company, Continental AG, Federal-Mogul LLC, and TRW Automotive, along with other major global and regional brake component manufacturers.
Key opportunities include the development of asbestos-free composite and ceramic friction materials, lightweight brake components, and expanding aftermarket distribution networks across emerging automotive markets.
Market growth is primarily driven by increasing vehicle production and ownership, stringent vehicle safety regulations, rising replacement demand, and advancements in braking technologies for passenger and commercial vehicles.
The Leading/Trailing segment dominates by product type with approximately 52.40% share, while Semi-Metallic leads by material with approximately 46.60%, and Passenger Cars dominate by vehicle type with approximately 58.60% share. Duo-Servo, Ceramic/Composite, and Aftermarket segments are among the fastest-growing categories.
Asia Pacific dominates the Automotive Brake Shoe Market and is also among the fastest-growing regional markets, supported by its large automotive manufacturing base, expanding vehicle fleet, increasing aftermarket demand, and growing automotive production in countries such as China and India.
