
Stolen Vehicle Recovery Market Report Scope & Overview:
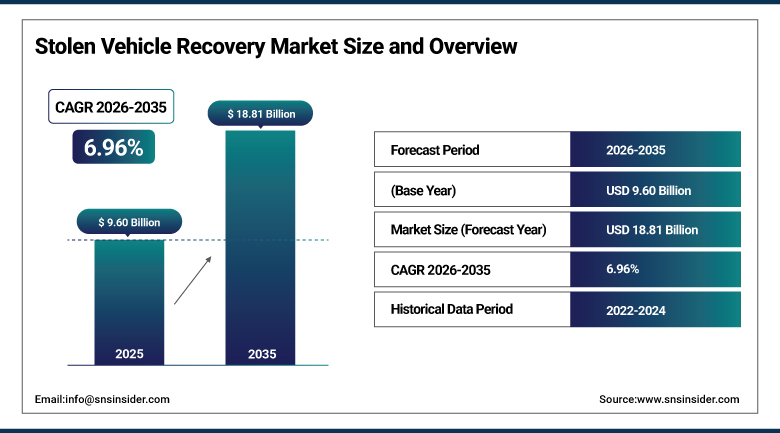
The Stolen Vehicle Recovery Market was valued at USD 9.60 Billion in 2025 and is expected to reach USD 18.81 Billion by 2035, growing at a CAGR of 6.96% from 2026-2035.
The stolen vehicle recovery system facilitates the recovery of vehicles after they have been stolen through the installation of a hidden device within the vehicle that records its position and sends it to relevant authorities, who then use this data to locate the vehicle and retrieve it. Today’s SVR systems are comprised of technologies such as GNSS navigation, cellular and IoT networking capabilities and even artificial intelligence analytics, allowing them to offer live tracking, geofencing, remote immobilization, and behavioral analysis among others, thereby making the process of recovery much more complex than it used to be before. Automakers, insurance companies and fleet managers all make use of integrated SVR technology in order to minimize theft risks, increase speed of recovery and improve driver safety.
On November 24, 2025, Ituran Location and Control Ltd. announced it had signed an initial three-year service agreement with Renault, a new major European original equipment manufacturer, with the contract covering multiple countries in the Latin American region and strong potential for expansion to additional markets globally as well as extended service periods. André Mói, Purchasing Director at Renault, noted that the agreement aligns with the automaker's strategy of working with leading suppliers to ensure the best solutions for customers, reflecting the continued trend of established OEMs formalizing direct, embedded stolen vehicle recovery partnerships rather than leaving telematics security as a purely aftermarket consumer decision.
To Get more information Stolen Vehicle Recovery Market - Request Free Sample Report
Stolen Vehicle Recovery Market Trends
- Rising integration of AI-based analytics enabling behavioral anomaly detection and predictive theft-risk scoring.
- Growing adoption of embedded OEM telematics hardware driven by expanding European safety regulation mandates.
- Expanding demand from rental and leasing fleet operators requiring unified dashboards for unauthorized movement alerts.
- Increasing collaboration between automakers, law enforcement agencies, and telematics vendors improving recovery rates.
- Rising use of low-power wide-area connectivity compressing device costs and spurring aftermarket demand.
U.S. Stolen Vehicle Recovery Market Outlook
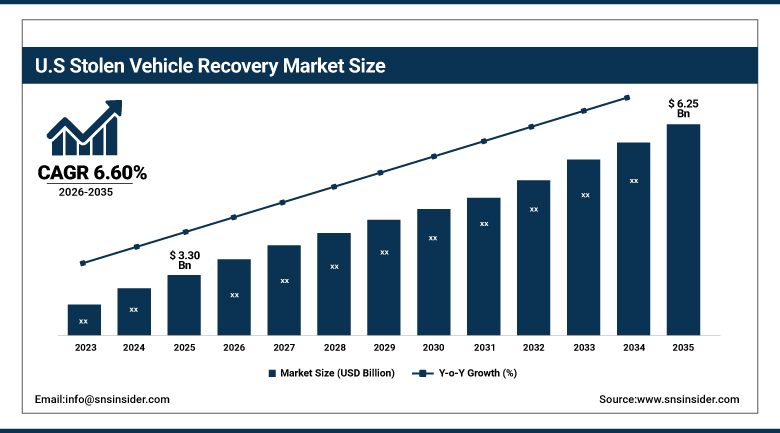
The U.S. Stolen Vehicle Recovery Market was valued at USD 3.30 Billion in 2025 and is expected to reach USD 6.25 Billion by 2035, growing at a CAGR of 6.60% from 2026-2035.
The U.S. Stolen Vehicle Recovery Market continues to benefit from rapid theft-response programs, stricter safety mandates, and the broader pivot toward data-driven mobility services that continue redefining competitive priorities across the domestic industry. Automotive industry collaboration with the police and telematics companies has already reduced vehicle thefts in the US by 17% each year, which proves the real need for such measures within the US market and justifies further investments into vehicle recovery systems. Insurance and financial companies are becoming more and more interested in installing certified tracking devices in order to provide insurance and financing, which increases the demand, and the government still represents the niche customer for covert devices used in investigation procedures.
On September 16, 2026, LoJack marked its next chapter for dealers, consumers, and the communities it serves, combining back-to-back industry recognition, a 47-year law enforcement recovery network, and a powerful integrated role inside Solera's emerging Dealer OS platform. This integration reflects how one of the domestic market's longest-established recovery brands continues modernizing its distribution and dealer-facing technology infrastructure, positioning the company to extend its decades-long law enforcement partnership network into an increasingly digital, platform-based dealer sales and service ecosystem.
Stolen Vehicle Recovery Market Segment Analysis
- By Technology, the Cellular & Telematics Platforms segment dominated the Stolen Vehicle Recovery Market with approximately 38.60% share in 2025, while the Hybrid segment is the fastest growing with a CAGR of approximately 9.20%.
- By Vehicle Type, the Passenger Vehicles segment dominated the Stolen Vehicle Recovery Market with approximately 70.60% share in 2025, while the Commercial Vehicles segment is the fastest growing with a CAGR of approximately 8.60%.
- By Installation Type, the OEM-Installed segment dominated the Stolen Vehicle Recovery Market with approximately 60.60% share in 2025, while the Aftermarket segment is the fastest growing with a CAGR of approximately 8.20%.
- By End-User, the Individual Vehicle Owners segment dominated the Stolen Vehicle Recovery Market with approximately 42.60% share in 2025, while the Fleet Operators/Rental & Leasing segment is the fastest growing with a CAGR of approximately 8.60%.
By Technology, Cellular & Telematics Platforms Dominates the Stolen Vehicle Recovery Market and Hybrid Grows Fastest
Cellular and telematics platforms hold the largest technology share, reflecting the widespread availability and reliability of cellular network coverage across virtually every major market alongside these platforms' ability to deliver continuous, real-time vehicle location updates rather than the more limited, event-triggered capability that earlier-generation recovery technologies typically offered. Modern cellular and telematics platforms continue combining GNSS positioning with cellular and IoT connectivity to enable live vehicle tracking, geofencing, remote immobilization, and behavioral anomaly detection, a genuinely comprehensive capability set that continues to make this technology category the default architectural foundation for the majority of currently deployed stolen vehicle recovery systems worldwide.
Hybrid platforms represent the fastest-growing technology category, as manufacturers increasingly combine multiple positioning and connectivity technologies, including GNSS, cellular, radio frequency, and low-power wide-area connectivity, within a single integrated system to maximize recovery reliability across the full range of theft scenarios these vehicles might encounter, including situations where GPS signal jamming or cellular network gaps might otherwise compromise a single-technology system's effectiveness. As theft techniques continue growing more sophisticated, including criminals employing signal-jamming equipment specifically designed to defeat single-technology tracking systems, hybrid platforms' redundant, multi-technology architecture continues to position this category for sustained above-market growth as both automakers and consumers increasingly prioritize genuinely reliable recovery capability over cost alone.
By Vehicle Type, Passenger Vehicles Dominates the Stolen Vehicle Recovery Market and Commercial Vehicles Grows Fastest
Passenger vehicles dominate the market due to high ownership rates and increasing theft incidence globally, reflecting the sheer scale of the global passenger vehicle population relative to commercial fleets alongside sustained consumer demand for personal vehicle security, particularly as criminals continue employing increasingly advanced techniques, including hacking into vehicle computer systems, to steal cars equipped with keyless entry that may be susceptible to unauthorized access. This combination of scale and genuine, evolving theft risk continues to sustain passenger vehicles' position as the largest vehicle type category across the broader stolen vehicle recovery market.
Commercial vehicles represent the fastest-growing vehicle type, driven by growing fleet operations, ride-hailing, and logistics sectors that continue recognizing the substantial financial exposure a single stolen commercial vehicle or its cargo can represent relative to a typical personal vehicle theft. Asset pools spanning thousands of vehicles across multiple cities require unified dashboards that flag unauthorized movement, mileage overruns, and tamper attempts, and as commercial fleet operators increasingly adopt these comprehensive monitoring platforms as standard operational practice rather than an optional add-on, commercial vehicles continue capturing an increasing share of new stolen vehicle recovery system deployment relative to the broader, passenger-vehicle-dominated market.
By Installation Type, OEM-Installed Dominates the Stolen Vehicle Recovery Market and Aftermarket Grows Fastest
OEM systems take the lead when installation type is concerned because of direct deals between recovery technology providers and leading automakers who will integrate the technology directly into their vehicles at the manufacturing stage. The European General Safety Regulation II will be implemented by July 2024; this regulation will have a telematics hardware embedded in all new vehicles sold in Europe, thus making the installed base for security applications much wider and further confirming the dominance of OEM installations in the stolen vehicle recovery market globally.
Aftermarket installation represents the fastest-growing installation type, as low-power wide-area technologies continue compressing device costs, spurring aftermarket demand in price-sensitive geographies where consumers and fleet operators seek recovery capability for vehicles that didn't ship with factory-installed systems. As aftermarket device costs continue declining while capability continues improving, this installation type continues capturing an increasing share of new system deployment, particularly across emerging markets and among owners of older vehicles that predate widespread OEM telematics integration, positioning aftermarket installation for sustained above-market growth relative to the broader OEM-dominated market.
By End-User, Individual Vehicle Owners Dominates the Stolen Vehicle Recovery Market and Fleet Operators/Rental & Leasing Grows Fastest
Individual vehicle owners held the largest end-user share, reflecting the sheer scale of the global personal vehicle ownership base and sustained consumer willingness to invest in recovery technology given rising public awareness of vehicle theft risk and the genuine peace of mind these systems provide. Rising consumer awareness and regulatory support for vehicle security, combined with direct incentives that insurance companies increasingly offer customers who install recovery systems, continue reinforcing individual vehicle owners' position as the largest end-user category within the broader stolen vehicle recovery market.
Fleet operators, including rental and leasing companies, represent the fastest-growing end-user category, as these organizations increasingly recognize that unified, fleet-wide recovery and monitoring capability delivers genuine operational value well beyond theft recovery alone, extending into unauthorized movement detection, mileage tracking, and tamper alerting across asset pools spanning thousands of vehicles. As rental and leasing companies continue expanding their fleets while facing mounting pressure to minimize asset loss and maximize utilization efficiency, sustained investment in comprehensive fleet-wide recovery and monitoring platforms continues to drive above-market growth for this end-user category relative to the broader, individually-owned-vehicle-dominated market.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
84.60% |
|
Europe |
Germany |
29.60% |
|
Asia Pacific |
China |
39.60% |
|
Latin America |
Brazil |
27.60% |
|
Middle East & Africa |
United Arab Emirates |
24.60% |
North America Stolen Vehicle Recovery Market Insights
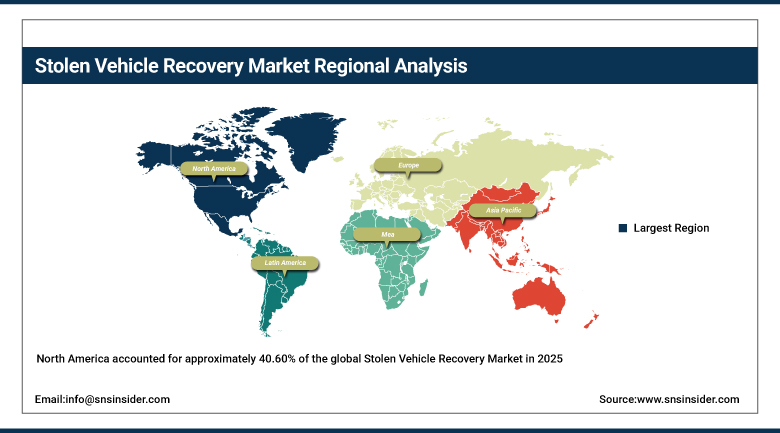
North America accounted for approximately 40.60% of the global Stolen Vehicle Recovery Market in 2025, making it the largest regional market, supported by sustained collaborations among automakers, law enforcement agencies, and telematics vendors that have already cut reported thefts in the United States by 17% annually. The region's concentration of leading recovery technology providers, combined with strong insurer requirements for certified tracking devices before underwriting high-value fleets, continues to anchor North America's position as the largest and most technologically mature stolen vehicle recovery market globally.
Canada is contributing incremental regional demand as its own vehicle security and insurance markets continue evolving. Continued domestic investment in AI-based analytics and integrated fleet management platforms is expected to sustain North America's leading position through the forecast period, even as growth in percentage terms moderates relative to faster-expanding Asia Pacific markets.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Stolen Vehicle Recovery Market Insights
Asia Pacific is the region experiencing the most rapid growth in the market at a CAGR of 6.88% during the forecast period, driven by growing demand for luxury vehicles across the region that has made these vehicles prime targets for thieves, highlighting the need for effective recovery solutions among an increasingly affluent vehicle-owning population. Public awareness campaigns aimed at informing vehicle owners about theft prevention strategies and the significance of reporting incidents continue reinforcing regional demand growth alongside rapidly expanding vehicle ownership across major regional economies.
China's substantial vehicle production and ownership base continues to anchor regional demand, supported by expanding domestic telematics manufacturing capability. India's rapidly growing vehicle fleet continues contributing meaningful incremental regional growth as vehicle ownership expands alongside rising middle-class disposable income, while Japan and South Korea contribute additional regional scale through established automotive and technology sectors, reinforcing Asia Pacific's position as the fastest-growing market for stolen vehicle recovery through the forecast period.
Europe Stolen Vehicle Recovery Market Insights
Europe represents a significant share of the global Stolen Vehicle Recovery Market, with regional demand substantially reinforced by the European Union's General Safety Regulation II, effective July 2024, which embeds telematics hardware in every new vehicle sold within the region, unlocking a broad installed base for security applications. Germany's substantial automotive manufacturing base continues to anchor regional demand, while the region's stringent regulatory framework continues to guarantee sustained baseline demand for recovery-capable telematics hardware across the entire European new vehicle market.
France, Italy, and other major European automotive markets contribute steady regional demand as national vehicle manufacturers continue extending telematics and recovery hardware adoption across their vehicle lineups. Privacy rulings that define Vehicle Identification Numbers as personal data continue compelling providers to redesign data-handling practices, adding genuine regulatory complexity that regional providers continue navigating as they balance recovery capability against evolving data protection requirements.
MEA & Latin America Stolen Vehicle Recovery Market Insights
The Middle East & Africa market is supported by growing vehicle ownership and rising vehicle theft concerns across the United Arab Emirates and Saudi Arabia, where regional governments continue investing in broader vehicle security infrastructure and regulatory frameworks. Regional insurance and automotive markets continue gradually adopting more sophisticated recovery technology as consumer security expectations continue rising.
Latin America's market is anchored substantially by Ituran's position as the largest OEM telematics provider in the region, with the company's recent multi-year agreements with Stellantis and Renault continuing to expand embedded recovery hardware across the region's new vehicle fleet. Brazil represents a particularly substantial market given Ituran's established subscriber base within the country, while Mexico and other regional markets continue contributing incremental growth as domestic vehicle security awareness continues to expand.
Market Dynamics
Growth Drivers: Rising Vehicle Theft Rates and Connected Vehicle Architecture Adoption
Rise in vehicle theft rates and increasingly sophisticated auto-theft networks represent the primary driver of Stolen Vehicle Recovery Market growth, as criminals continue employing more advanced techniques, including hacking into vehicle computer systems and defeating keyless entry security, that continue reinforcing genuine consumer and commercial demand for effective recovery technology. Growing technological innovations spanning GPS, IoT, and AI/ML capability continue expanding what these systems can reliably deliver, reinforcing sustained market growth even as underlying theft rates fluctuate across different regions and time periods.
Growing fleet operations, ride-hailing, and logistics sectors represent a second major growth driver, as the rapid adoption of connected vehicle architectures, intelligent telematics, and embedded security modules continues transforming the broader stolen vehicle recovery ecosystem well beyond its traditional individual-consumer origins. Rise in consumer awareness and regulatory support for vehicle security, exemplified by Europe's General Safety Regulation II, continues reinforcing sustained demand across both OEM and aftermarket installation channels.
Restraints: High Installation Costs and Data Privacy Concerns
High cost of SVR installation and subscription represents a meaningful restraint on market growth, as comprehensive, hybrid-technology recovery systems continue commanding premium pricing that can genuinely limit adoption among price-sensitive consumers and smaller fleet operators, particularly across emerging markets where disposable income constraints remain more pronounced than in established Western markets.
Data privacy and cybersecurity concerns represent a further restraint, as privacy rulings that define Vehicle Identification Numbers as personal data continue compelling providers to redesign data-handling practices to retain regulatory compliance, adding genuine operational complexity and cost that continues to constrain how quickly providers can deploy new tracking and analytics capability across different regulatory jurisdictions.
Opportunities: Fleet Management Integration and Emerging Market Expansion
Continued integration with smart-city initiatives and public-safety networks represents a substantial opportunity, as providers that can successfully position their recovery technology within broader municipal traffic monitoring and public safety infrastructure are positioned to capture demand from government agencies seeking comprehensive urban mobility and security data beyond individual vehicle recovery alone, exemplified by recent telematics providers securing government traffic-monitoring contracts leveraging their existing connected vehicle data assets.
Expansion in emerging markets with growing vehicle ownership offers a further substantial avenue for growth, as providers that can successfully establish OEM partnerships and distribution networks across rapidly motorizing regions are positioned to capture significant new subscriber growth. Manufacturers pursuing strategic OEM agreements across multiple international markets simultaneously are well positioned to capture demand from automakers increasingly viewing embedded recovery and telematics capability as a genuine competitive differentiator rather than an optional accessory.
Recent Developments:
- 2026: Tracker expanded its connected-vehicle security offering around GPS-based stolen-vehicle location and recovery services, integrating tracking capabilities with automotive security solutions.
- 2026: CalAmp’s telematics technology remained focused on connected-vehicle tracking and location intelligence, supporting asset monitoring, fleet visibility, and vehicle-recovery applications.
- 2026: Teltonika expanded its automotive telematics portfolio with connected tracking hardware supporting GNSS positioning, cellular communication, fleet monitoring, and vehicle-security applications.
Stolen Vehicle Recovery Market Key Players are:
- Ituran Location and Control Ltd.
- Cartrack Holdings Ltd.
- LoJack Corporation (Solera)
- Tracker Network (Cobra)
- CalAmp Corp.
- ERM Advanced Telematics Ltd.
- Teltonika Networks
- Vodafone Automotive
- Netstar (Altron)
- OCTO Telematics
- Karooooo Ltd.
- Bosch Mobility Solutions
- Targa Telematics S.p.A.
- Ridecell, Inc.
- Spireon, Inc.
- Ruptela
- Beame
- Motive Technologies, Inc.
- Sensata Technologies
- Mister Track
Stolen Vehicle Recovery Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 9.60 Billion |
| Market Size by 2035 | USD 18.81 Billion |
| CAGR | CAGR of 6.96% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Technology (Cellular & Telematics Platforms, GPS/GNSS-Based, RFID, Hybrid, Others) • By Vehicle Type (Passenger Vehicles, Commercial Vehicles) • By Installation Type (OEM-Installed, Aftermarket) • By End-User (Individual Vehicle Owners, Fleet Operators/Rental & Leasing, Insurance Companies, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Ituran Location and Control Ltd., Cartrack Holdings Ltd., LoJack Corporation (Solera), Tracker Network (Cobra), CalAmp Corp., ERM Advanced Telematics Ltd., Teltonika Networks, Vodafone Automotive, Netstar (Altron), OCTO Telematics, Karooooo Ltd., Bosch Mobility Solutions, Targa Telematics S.p.A., Ridecell, Inc., Spireon, Inc., Ruptela, Beame, Motive Technologies, Inc., Sensata Technologies, Mister Track |
Frequently Asked Questions
Key players include Ituran Location and Control Ltd., Cartrack Holdings Ltd., LoJack Corporation, Tracker Network, CalAmp Corp., and ERM Advanced Telematics Ltd., among other telematics and recovery technology providers.
Continued integration with smart-city initiatives and public-safety networks, and expansion in emerging markets with growing vehicle ownership, represent the primary opportunities.
Growth is primarily driven by rising vehicle theft rates and sophisticated auto-theft networks combined with growing fleet operations, ride-hailing, and logistics sectors.
By Vehicle Type, Passenger Vehicles dominated the market with approximately 70.60% share in 2025, reflecting high ownership rates and increasing theft incidence globally.
