
Sulfur Bentonite Market Report Scope & Overview:
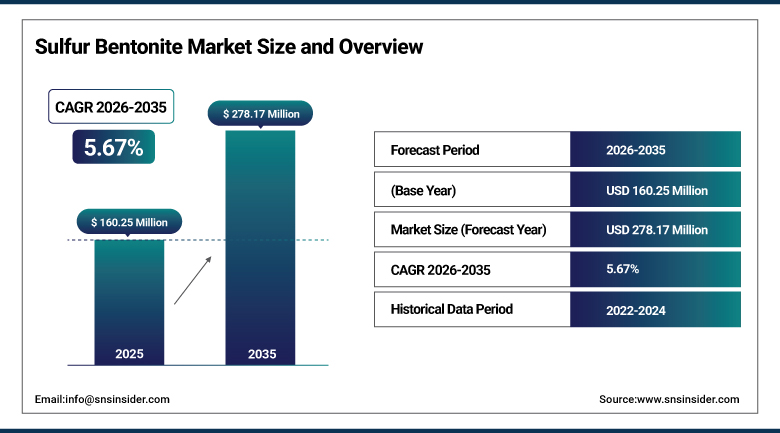
The Sulfur Bentonite Market was valued at USD 160.25 Million in 2025 and is expected to reach USD 278.17 Million by 2035, growing at a CAGR of 5.67% from 2026-2035.
The Sulfur Bentonite Market is experiencing steady growth due to the rising need for sulfur-based fertilizers to overcome the deficiency of sulfur in agricultural soils and increase crop yield. Growing popularity of balanced fertilization practices and awareness regarding the need for secondary nutrients is motivating farmers to use sulfur bentonite as an essential component in their crop nutrition plans. The property of providing slow release of plant available sulfur, improving nutrient absorption, and maintaining soil fertility makes it an appropriate option for different agricultural uses. Moreover, rising global food needs, high-intensity farming practices, and depleting soil sulfur content are boosting market demand.
⮞In January 2026, the University of Nebraska-Lincoln announced a two-year project with CU Boulder, the International Fertilizer Association and The Sulphur Institute to map crop sulfur use and deficiencies across South America, North America, South Asia, East Asia, Southeast Asia, Australia and Europe.
To Get more information Sulfur Bentonite Market - Request Free Sample Report
Sulfur Bentonite Market Trends
-
New pastillation capacity in India and the Gulf is broadening regional supply of sulfur bentonite.
-
Expanding oilseed acreage across Asia, North America and South America is lifting sulfur application rates.
-
Producers are enriching pastilles with micronutrients and humic acids to support premium positioning.
-
Organic-approved sulfur grades are gaining listings as certified growers seek compliant sulfur sources.
-
Sulfur price swings and supplier consolidation are reshaping procurement and distribution strategies.
U.S. Sulfur Bentonite Market Outlook
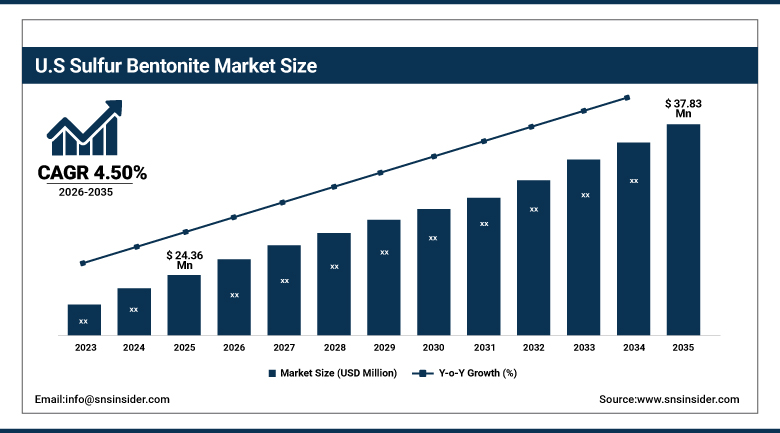
The U.S. Sulfur Bentonite Market was valued at USD 24.36 Million in 2025 and is expected to reach USD 37.83 Million by 2035, growing at a CAGR of 4.50% from 2026-2035.
The U.S. Sulfur Bentonite Market is progressing at a steady speed, as the growers in the Corn Belt and Gulf Coast regions respond to soils that are sulfur-deficient. Due to low atmospheric deposition, the amount of sulfur naturally provided to the soil has declined. Farmers growing soybean and corn are becoming increasingly conscious about applying sulfur-based products as part of their pre-planting fertilization. Sulfur bentonite granules are mixed into dry fertilizers by dealers and then supplied to farmers via existing distribution channels. Cooperative extension services offer guidelines for sulfur usage for soybean and corn, thus aiding growth. Growth remains below the world average due to the mature base and competitive sulphate.
⮞In June 2026, the USDA National Agricultural Statistics Service reported 2026 soybean plantings of 85.4 million acres, an increase of 5% from the previous year. Larger soybean area raises the sulfur requirement of Midwest fields and supports demand for sulfur bentonite applied before planting.
Sulfur Bentonite Market Segment Analysis
-
By Crop Type, the Oilseeds segment dominated the Sulfur Bentonite Market with approximately 44.95% share in 2025, while the Fruits and Vegetables segment is the fastest growing with a CAGR of approximately 6.47%.
-
By Sulfur Content, the 90% Sulfur segment dominated the Sulfur Bentonite Market with approximately 62.07% share in 2025, while the 85% to 89% Sulfur segment is the fastest growing with a CAGR of approximately 6.17%.
-
By Form, the Granules segment dominated the Sulfur Bentonite Market with approximately 78.20% share in 2025, while the Pastilles segment is the fastest growing with a CAGR of approximately 6.37%.
-
By Distribution Channel, the Agri-Retail Dealers segment dominated the Sulfur Bentonite Market with approximately 46.00% share in 2025, while the Online segment is the fastest growing with a CAGR of approximately 8.17%.
By Crop Type, Oilseeds Dominate Sulfur Bentonite Market; Fruits and Vegetables to Register Fastest Growth.
Oilseeds lead crop-type consumption because rapeseed, canola, soybean, sunflower and groundnut carry some of the highest sulfur requirements among field crops. Sulfur supports oil synthesis and protein formation, so deficiency shows directly in seed yield and oil content. Large planted areas in India, Canada, Brazil and the European Union create steady annual demand. Growers favor sulfur bentonite because the pastille disperses in soil moisture and supplies sulfur across the crop cycle, which matches the long uptake period of oilseed plants.
Fruits and Vegetables are projected to gain momentum as horticulture expands and quality standards tighten. Sulfur influences flavor compounds, pungency in onions and garlic, and fruit firmness, so produce growers treat it as a quality input rather than a yield input alone. Intensive cropping on small plots exhausts soil sulfur quickly through repeated harvests. Exporters supplying organized retail chains also adopt balanced nutrition programs. Smaller package sizes are widening access among horticulture growers beyond traditional field crop farmers.
⮞In March 2026, India's Ministry of Agriculture and Farmers Welfare reported 2024-25 fruit production of 117.65 million tonnes, an increase of 4.13% over the previous year. Rising horticulture output intensifies nutrient removal and raises sulfur demand in intensively cropped fruit and vegetable belts.
By Sulfur Content, 90% Sulfur Dominates Sulfur Bentonite Market; 85% to 89% Sulfur to Register Fastest Growth.
The 90% grade prevails because every bag delivers more elemental sulfur, so growers handle fewer bags per hectare and spend less on freight, storage and spreading labor. Producers also favor a single high-analysis product that is simpler to manufacture, stock and ship over long distances than several blends. Blenders value the predictable sulfur content when formulating custom nutrient programs. Long-standing registrations and wide dealer familiarity reinforce repeat purchases among oilseed and cereal growers in every major farming region.
The 85% to 89% grade is advancing because its higher bentonite fraction swells faster on wetting and breaks the pastille apart more quickly in soil. Faster dispersion exposes more sulfur surface to soil bacteria, which shortens the oxidation lag that limits elemental sulfur in the first season. Growers facing early-season deficiency in cereals and vegetables therefore choose it for quicker crop availability. Suppliers use the lower sulfur loading to carry added micronutrients, which differentiates their offerings from standard high-analysis products.
By Form, Granules Dominate Sulfur Bentonite Market; Pastilles to Register Fastest Growth.
Granules hold the leading position because they flow cleanly through commercial spreaders and blend evenly with phosphate and potash without segregating. The dust-free solid limits handling losses and fire risk compared with fine sulfur powder, which eases storage at retail depots and farm sheds. Bentonite inside each granule swells with soil moisture and disperses the sulfur for gradual oxidation. These traits suit large-acre broadcast application, where uniform coverage and bulk logistics matter more than the lowest ingredient cost.
Pastilles are growing faster as drop-forming technology produces uniform, hard, near-spherical units with minimal dust and consistent particle size. This uniformity improves spreader accuracy and blend quality, which professional applicators value. Producers can also adjust the bentonite ratio to tune breakdown speed and can embed micronutrients during forming. Capacity additions in India are increasing pastille availability, which lowers unit cost and moves the format into mainstream retail channels. Consistent size also reduces segregation during bulk transport and storage.
⮞In June 2025, the Organic Materials Review Institute added an elemental sulfur pellet to its listing for crop fertilizers and soil amendments, bringing one Canadian supplier's OMRI-listed sulfur range to six products. The listing reflects rising availability of organic-compliant sulfur forms for certified growers.
By Distribution Channel, Agri-Retail Dealers Dominate Sulfur Bentonite Market; Online to Register Fastest Growth.
Agri-retail dealers lead distribution because farmers prefer to buy inputs from the nearest shop they already trust. Dealers stock seed, crop protection and nutrients together, so a grower can finalize the input plan in one visit before sowing. They extend short-term credit, advise on soil deficiencies and deliver in small lots that smallholders can afford. Suppliers rely on this dense network to reach scattered farms where direct sales would be uneconomical, which keeps dealers central to seasonal stocking and promotion.
Online channels are growing fastest from a small base as marketplaces and manufacturer portals bring product information and price comparison directly to farmers. Rising smartphone use in rural areas allows growers to verify sulfur content, read agronomy guidance and order pack sizes suited to small plots. Home delivery shortens the gap between a soil test recommendation and application. Suppliers use digital platforms to enter remote districts without building dealer relationships and to reach organic growers searching for approved grades.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
41.20 |
|
Europe |
Germany |
26.50 |
|
North America |
United States |
80.00 |
|
Middle East & Africa |
South Africa |
36.10 |
|
Latin America |
Brazil |
52.40 |
North America Sulfur Bentonite Market Insights
North American demand concentrates in the U.S. Corn Belt and Gulf Coast and on the Canadian Prairies, where soybean, corn, wheat and canola fields have lost the sulfur once delivered by industrial fallout. Regional producers make pastilles close to sulfur supplies linked to oil refining and gas processing, which keeps supply chains short and supports year-round availability. Retail blenders include granular sulfur bentonite in custom dry mixes tailored to field-level soil tests. Fertilizer retailers promote early-spring applications so that oxidation begins before crop demand peaks.
Canada contributes growth through expanding canola area, a crop with one of the highest sulfur requirements among field crops. Organic production in both countries adds a specialty segment that requires listed sulfur products. Higher agronomic awareness among large farm operators encourages regular soil sampling for sulfur, and university extension programs increasingly recommend sulfur in routine fertility plans, although the shift from sulfate to elemental sulfur remains gradual. Wheat producers in the Great Plains add a further source of demand as protein premiums encourage balanced nitrogen and sulfur management.
⮞In June 2026, Statistics Canada reported that farmers planned to seed 23.4 million acres of canola in 2026, an increase of 8.4% from the previous year. Larger canola area adds directly to demand for slow-release sulfur on Prairie soils.
Europe Sulfur Bentonite Market Insights
Europe ranked as the second-largest regional market in 2025, with demand rooted in rapeseed cultivation across France, Germany, Poland and Romania. Decades of cleaner industrial emissions have all but removed atmospheric sulfur deposition, so winter oilseed rape now frequently shows deficiency symptoms in spring. Growers apply sulfur either as sulfates or as elemental sulfur within compound programs. Germany leads regional consumption through well-organized agricultural cooperatives and strong agronomic advisory services, while the United Kingdom and Italy contribute through cereal and vegetable systems.
Growth moderates relative to emerging regions because mature fertility programs already include sulfate sources that act quickly. Sulfur bentonite gains traction where growers seek residual supply across a wet winter and a longer nutrient window. EU nutrient management rules that limit leaching encourage products with controlled release and clearly traceable composition, which favors well-characterized pastilles and granules over fine powders in Germany and France alike. Eastern Europe and Russia hold untapped potential as oilseed area expands and sulfur testing becomes routine.
⮞The European Commission projected in July 2025 that the EU rapeseed harvest would reach about 18.5 million tonnes, up almost 1.9 million tonnes from 2024. A larger rapeseed harvest enlarges the sulfur-hungry crop area served by European fertilizer blenders.
Asia Pacific Sulfur Bentonite Market Insights
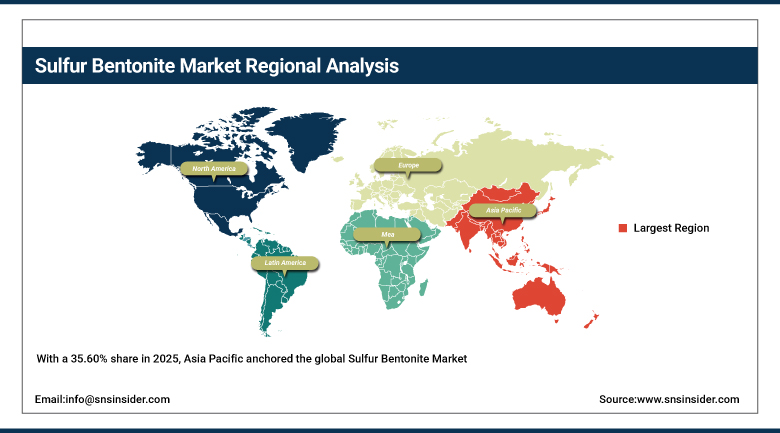
With a 35.60% share in 2025, Asia Pacific anchored the global Sulfur Bentonite Market, supported by the largest oilseed, pulse and cereal acreage in the world. China leads regional consumption through intensive rapeseed and soybean cultivation across the Yangtze basin and the northeast. India follows closely and shows the steepest national growth within the region as sulfur-deficient soils spread across mustard, groundnut and soybean belts. Australia adds demand through a large canola crop grown in rotation with wheat, while Japan and South Korea sustain smaller volumes through vegetable and rice production.
Asia Pacific is also projected to register the fastest expansion, advancing at a CAGR of 6.27% between 2026 and 2035. Wider recognition of sulfur deficiency among Indian farmers, government plans to enlarge oilseed area and new production capacity in India and the Middle East are lifting regional supply and awareness. Rising rural digital access and cooperative distribution add reach in Southeast Asia, where palm and rice systems increasingly adopt sulfur in balanced fertilization. Plantation operators in Indonesia and Malaysia are also widening sulfur use in nutrient schedules for oil palm.
⮞In March 2026, the Australian Bureau of Agricultural and Resource Economics and Sciences forecast 2025-26 canola production at 7.7 million tonnes, a rise of 20% and the second-largest crop on record. A larger canola crop expands the sulfur-responsive area available to sulfur bentonite suppliers in Australia.
Get Customized Report as per Your Business Requirement - Enquiry Now
MEA and Latin America Sulfur Bentonite Market Insights
Middle East and Africa combines a production hub with a developing consumption base. Gulf states supply sulfur from sour gas and refining and host dedicated pastillation plants that serve export markets. Within Africa South Africa leads consumption through its commercial maize, soybean and sunflower sector. Cooperative networks and smallholder access programs are expected to support gradual uptake in East and West African oilseed regions, although purchasing power remains a limiting factor. Saudi Arabia and the UAE also host fertilizer and sulfur handling infrastructure that supports regional trade.
⮞In June 2026, South Africa's Crop Estimates Committee projected sunflower seed production at 910,530 tonnes, a rise of 3.74% on its previous forecast. Higher sunflower output supports sulfur demand among South African commercial growers.
Latin America benefits from the largest soybean export base in the world. Brazil leads regional demand as farmers on the weathered tropical soils of the Cerrado apply sulfur to sustain high-yield soybean and corn rotations. Argentina adds demand through sunflower and soybean while Mexico contributes through maize, vegetables and berries. Colombia and Chile add demand through coffee, fruit and vegetable production. Most sulfur products reach farmers through imports and large agri-retail chains, which makes logistics and port access important for suppliers. Local blending near grain corridors improves availability.
⮞In February 2026, Brazil's national supply agency Conab estimated the 2025/26 soybean harvest at a record 177.985 million tonnes. Record soybean output sustains sulfur nutrition requirements across Brazilian grain corridors.
Market Dynamics
Growth Drivers: Depleting Soil Sulfur and Expanding Oilseed Acreage Are Raising Demand for Sulfur Bentonite
Cleaner fuels, tighter emissions regulation and improved phosphate and nitrogen fertilizers have led to a dramatic decrease in the incidental sulfur applied in cropland for several decades. Sulfur deficiency is now reported through soil testing programs in many parts of the U.S. Midwest, Europe and South Asia, and modern, high-yield varieties take up more sulfur during harvest. This challenge is met by sulfur bentonite, which provides a powerful, gradual-release supplement and is easily applied with conventional machinery. Agronomists advise the use of such material for responsive crops, namely canola, soybeans, mustard and sunflowers, since sulfur is responsible for oil yield and protein quality.
Agricultural projects aimed at boosting oilseed production exacerbate this trend. The government initiatives aimed at reducing the import of edible oil lead farmers to expand their planted area and apply full sets of nutrients. In addition, soil testing is promoted through extension services and fertilizers producers, which turns a hidden deficiency into an evident need for sulfur products. More and more farmers learn about yield loss due to sulfur deficiency; hence, the application shifts from corrective measures to regular part of fertilization program for large oilseed regions.
⮞In February 2026, the USDA Foreign Agricultural Service reported that India planted 9.3 million hectares of rapeseed and mustard in marketing year 2025/26. Such a large area under a high-sulfur-demand crop underpins sustained purchases of sulfur bentonite.
Restraints: Slow Sulfur Release and Volatile Elemental Sulfur Prices Are Limiting Adoption of Sulfur Bentonite
Elemental sulfur needs to be oxidized by microbes in the soil in order to allow absorption by plants, thus only a very small percentage will get absorbed within the first year itself. Cold or dry weather conditions delay the oxidation process and often leave crops which are planted early in the year short on sulfur nutrition. In light of this agronomic constraint, growers have opted for a combination of sulfate and elemental sources, with the latter being used mainly to enhance immediate effects in cold climates of early spring.
Elemental sulfur is a waste product produced by the petroleum industry. This means that its pricing would follow market prices of energy, often fluctuating sharply within a single year. There is also a need to invest in pastillation facilities in order to handle elemental sulfur due to the fact that sulfur dust is highly flammable. Government incentives to use conventional fertilizers in certain countries and lack of information among small farmers as well as the difficulty of moisture control when storing are more factors which hamper its adoption in developing regions.
⮞In February 2026, the U.S. Geological Survey reported that the average unit value of U.S. sulfur rose to USD 180 per tonne in 2025 from USD 46.42 in 2024. The steep rise in input cost compresses pastille producer margins and raises delivered prices for growers.
Opportunities: Emerging Farm Economies and Enriched Pastille Formulations Are Widening the Addressable Market
There is still a long way to go with regard to sulfur fertilizer use in fast growing markets for oilseeds and pulses in South Asia, Southeast Asia, Africa and South America. Programs for mapping soils coupled with farmer education efforts could transform vast deficient land masses into demand. Pastillation or blending companies close to these areas can reduce transportation costs, season spikes and dependence on imports. Cooperatives and Internet platforms present alternative channels to farmers who never saw any supply from distributors previously. This widens the market for sulfur beyond commercially oriented farmland.
Highly priced products with zinc, boron or humic acid additives make it possible for suppliers to introduce premiums on their sulfur bentonite products. The development of faster releasing formulations will resolve issues related to release rate and digital agronomy services can help to calibrate application rates based on deficiencies in each particular plot. Certifications for organic production create additional premium segment of the market for organic production in North America, Europe and Australia. Retailers will be able to apply sulfur fertilizers in variable amounts per field section with the help of precision platforms.
⮞In March 2026, Argentina's Ministry of Agriculture estimated the 2025/26 sunflower crop at 7.3 million tonnes, a record and a 30.4% increase over the previous season. Record sunflower output signals scope for sulfur nutrition programs across South American oilseed regions.
Recent Developments:
-
February 2025, Sohar Sulphur Fertilizers reported that its Oman plant produced 48,500 tonnes of sulphur products in 2024, equal to 105% of its production target, with exports reaching more than 26 countries. The result confirms strong overseas demand for Gulf-made sulfur bentonite and supports further utilization of its plant capacity of up to 60,000 tonnes.
-
February 2026, Amarak Chemicals, part of the Aries Group, began operating a 60,000 tonne per year sulphur bentonite and sulphur products plant at Jebel Ali in Dubai.
-
March 2025, Coromandel International doubled the capacity of its Visakhapatnam bentonite sulphur unit from 25,000 to 50,000 tonnes using German technology. Gromor Sulphur combines 90% elemental sulfur with 10% bentonite in pastille form.
-
February 2026, National Fertilizers Limited received board in-principle approval for a 25,000 tonne per year bentonite sulphur plant at Vijaipur in India, with a planned investment of approximately USD 11.5 Million.
Sulfur Bentonite Market Key Players
-
Tiger-Sul (Tessenderlo Kerley)
-
Coromandel International
-
Sohar Sulphur Fertilizers
-
Amarak Chemicals
-
Martin Resources
-
Galaxy Sulfur
-
Ravensdown
Sulfur Bentonite Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 160.25 Million |
| Market Size by 2035 | USD 278.17 Million |
| CAGR | CAGR of 5.67% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Crop Type (Oilseeds, Cereals and Crops, Fruits and Vegetables, and Others) • By Sulfur Content (90% Sulfur, 85% to 89% Sulfur, and Below 85% Sulfur) • By Form (Granules, Pastilles, and Powder) • By Distribution Channel (Agri-Retail Dealers, Cooperatives, Direct-to-Farm, and Online) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Tiger-Sul (Tessenderlo Kerley), Coromandel International, Sohar Sulphur Fertilizers, Amarak Chemicals, Martin Resources, Galaxy Sulfur, Ravensdown |

Frequently Asked Questions
The key players in the Sulfur Bentonite Market include Tiger-Sul (Tessenderlo Kerley), Coromandel International, Sohar Sulphur Fertilizers, Amarak Chemicals and Martin Resources, among others.
Key opportunities include rising sulfur adoption in emerging oilseed and pulse economies, local pastillation and blending that lower logistics costs, enriched pastilles carrying micronutrients and humic acids, and growing demand for organic-approved sulfur grades. Cooperative and online distribution also opens access to smallholders.
The major growth factor is the depletion of soil sulfur caused by cleaner fuels, purer fertilizers and higher-yielding crops, combined with expanding oilseed acreage. Together these trends raise the need for slow-release sulfur sources such as sulfur bentonite.
The Oilseeds segment dominated the Sulfur Bentonite Market with approximately 44.95% share in 2025. Rapeseed, canola, soybean and sunflower have high sulfur requirements, and large planted areas create steady annual demand.
Asia Pacific dominated the Sulfur Bentonite Market with approximately 35.60% share in 2025.
