
Syntactic Foam Market Report Scope & Overview:
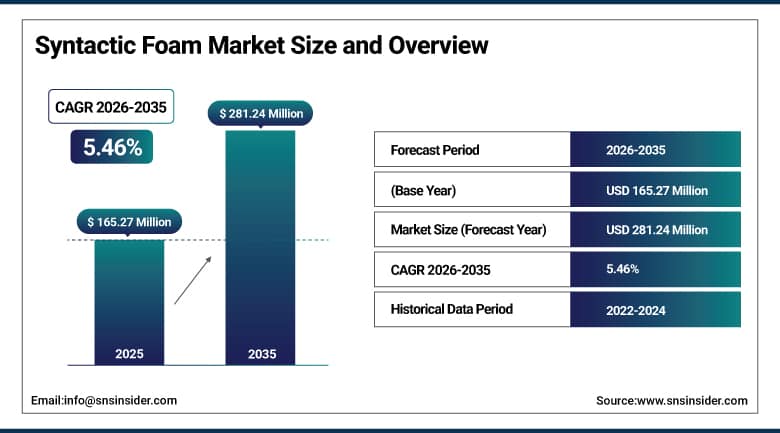
The Syntactic Foam Market size was valued at USD 165.27 Million in 2025 and is expected to reach USD 174.29 Million in 2026, rising to USD 281.24 Million by 2035. The market is forecast to expand at a CAGR of 5.46% during 2026–2035. Syntactic foam is a composite made by filling a resin or metal matrix with hollow microspheres, which gives a material that is light, strong under compression and resistant to water. Growth is supported by deepwater oil and gas development, underwater vehicles, defense and aerospace structures, and the need for buoyancy that works reliably at great depth.
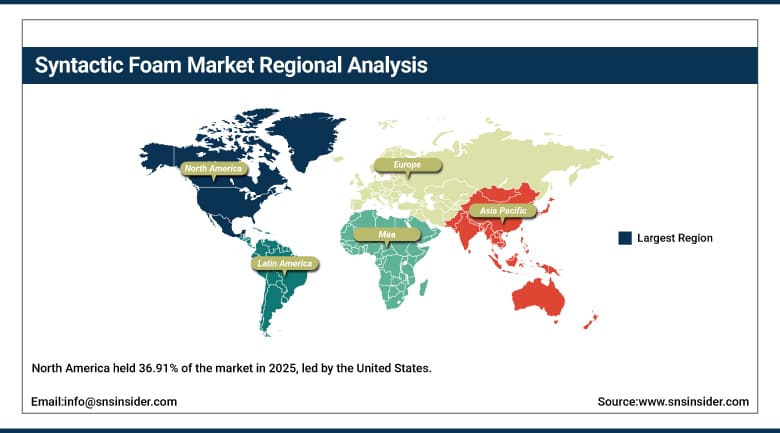
North America accounted for the largest share of the market, at 36.91% in 2025, because Gulf of Mexico deepwater projects, naval programs and aerospace suppliers create steady demand for qualified buoyancy and core materials. Europe follows on the strength of North Sea and Norwegian subsea activity, while Asia Pacific is the fastest growing region as offshore fields, shipbuilding and defense spending expand in Australia, China, India and Southeast Asia. Middle East & Africa and Latin America are smaller markets tied to offshore developments. Growth in all regions depends on offshore project timing and defense budgets.
To Get More Information On Syntactic Foam Market - Request Free Sample Report
Key Report Takeaways
-
By matrix type, polymer matrices held 40.62% in 2025, while hybrid matrices are the fastest growing.
-
By filler type, glass microspheres held 76.84% in 2025, while ceramic microspheres are the fastest growing.
-
By product type, micro-sphere foam held 54.81% in 2025 and is also the fastest growing.
-
By application, marine and subsea held 37.62% in 2025, while aerospace and defense is the fastest growing.
-
By region, North America held 36.91% in 2025, while Asia Pacific is the fastest growing.
Market Trends and Insights
Subsea operators are asking for buoyancy rated to deeper water and longer service lives, which pushes suppliers toward higher-strength microspheres, tougher resin systems and better quality records. Third-party approval of foam grades by classification societies is becoming a purchasing requirement, and it favors suppliers with documented test programs.
Manufacturers are adopting automated casting, vacuum degassing and machining of large blocks to cut cycle times and reduce voids. Tailored shapes such as molded modules for risers and vehicle hulls are replacing hand-cut blocks, and lighter foams with lower density are being developed for aerospace and electric vehicle structures.
Drivers Impact Analysis
|
Driver |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Deepwater and ultra-deepwater oil and gas development |
+2.38% |
North America and Latin America |
Short term (2 years or less) |
|
Underwater vehicles, defense and ocean science |
+1.74% |
Global |
Medium term (2 to 4 years) |
|
Lightweight structural cores in aerospace and transport |
+1.21% |
North America and Europe |
Medium term (2 to 4 years) |
|
Offshore wind and marine infrastructure |
+0.83% |
Europe and Asia Pacific |
Long term (4 years or more) |
|
Advances in microspheres, resins and production |
+0.57% |
Global |
Long term (4 years or more) |
Deepwater and Ultra-Deepwater Oil and Gas Development
Risers, umbilicals and flowlines in deep water need distributed buoyancy modules that keep their shape and volume under crushing pressure, and syntactic foam is the standard material for the job. Westwood Global Energy Group reported that 38 offshore field projects reached final investment decision in the first half of 2026, committing USD 66.40 Billion, up 90.00% from the first half of 2025. Floating production units, subsea trees and long tiebacks all require buoyancy, so a growing project backlog translates directly into foam orders.
Underwater Vehicles, Defense and Ocean Science
Remotely operated and autonomous underwater vehicles use syntactic foam for flotation because it provides lift without adding a pressurized hull. Navies are buying more uncrewed undersea systems, and research institutes are sending vehicles to the deepest ocean trenches. Each program calls for custom shapes and certified performance, and these sales carry high margins and repeat orders for replacement modules. Wider use of uncrewed vessels for survey, cable inspection and seabed mapping is adding new buyers beyond oil and gas operators and port authorities.
Lightweight Structural Cores in Aerospace and Transport
Syntactic foams are used as cores in sandwich panels and as potting and filler compounds where low weight, stiff compression behavior and moisture resistance are needed. Aircraft interiors, radomes, helicopter parts, rail components and some electric vehicle structures use these cores. As designers search for ways to cut mass without losing stiffness, specialty foams find places in new platforms and in repair work. Sandwich panels with syntactic cores also resist moisture ingress and damage from impact, which extends service life in harsh settings.
Offshore Wind and Marine Infrastructure
Floating wind farms need buoyant structures, cable buoyancy and protection systems for dynamic power cables, and these parts must survive years in the sea. Marine survey, aquaculture and port projects also use foam floats and fenders. As floating wind moves from demonstration to commercial scale in Europe and Asia, the demand for tailored buoyancy modules should widen the buyer base. Developers of floating wind arrays in Europe and Asia Pacific are testing buoyancy modules rated for decades of wave motion, which raises the technical bar and the value per unit.
Advances in Microspheres, Resins and Production
Stronger and lighter hollow microspheres, tougher epoxy and polyurethane systems and automated casting enable foams that reach greater depth at lower density. Improved quality control and nondestructive testing reduce rejection rates. These advances lower cost per unit of lift and make syntactic foam competitive for uses that once relied on cheaper but less durable materials. Digital design tools now simulate pressure, creep and thermal behavior before casting, so suppliers can offer optimized parts with fewer prototype cycles. Lower scrap and faster delivery help them win more bids.
Restraints Impact Analysis
|
Restraint |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
High material and processing costs |
-1.82% |
Global |
Short term (2 years or less) |
|
Cyclical offshore capital spending |
-1.36% |
North America and Europe |
Medium term (2 to 4 years) |
|
Long qualification cycles and strict quality needs |
-0.94% |
Global |
Medium term (2 to 4 years) |
|
Competition from alternative buoyancy and core materials |
-0.58% |
Global |
Long term (4 years or more) |
High Material and Processing Costs
High-strength glass and ceramic microspheres are costly, and epoxy and other resins are linked to petrochemical prices. Mixing, casting and curing large blocks without voids takes long cycles and skilled labor, and finished parts are often machined to tight tolerances. These costs make syntactic foam an expensive choice, and buyers use it only where simpler materials cannot meet depth or reliability needs. Raw material suppliers for premium microspheres are few, so price changes pass quickly into foam cost and delivery times.
Cyclical Offshore Capital Spending
A large part of demand comes from offshore oil and gas projects, and operators cut or postpone spending when oil prices weaken or financing tightens. Orders for buoyancy modules arrive late in a project timeline, so delays upstream can leave plants underused. Suppliers try to offset this with defense, wind and aerospace work, but these segments take years to scale. Several large contractors have responded by sharing orders among suppliers, which spreads risk but also keeps pricing firmly under sustained pressure.
Long Qualification Cycles and Strict Quality Needs
Buoyancy for deep water must pass hydrostatic pressure, creep, water absorption and thermal tests, and customers often require third-party witness and detailed records. New suppliers face lengthy approvals before they can bid, and any failure in the field carries large cost. Aerospace and defense qualification adds more time, which slows the entry of new materials and products. Tests can run for weeks at high pressure, and a single failed batch means repeating the cycle, so smaller foam makers often lack the test equipment and cash needed to compete.
Competition from Alternative Buoyancy and Core Materials
Rigid polyurethane and PVC foams, honeycomb cores, gas-filled floats and metal pressure housings can replace syntactic foam in shallower or less demanding uses. Advances in low-cost foams and fiber-reinforced composites narrow the performance gap. Syntactic foam retains an advantage for high-pressure service, but suppliers must keep showing the value of its durability and consistent density. Customers also worry about long-term water uptake, creep and aging, and some prefer to keep proven alternatives in service on lower-risk assets. Cost pressure in mature fields supports this conservative buying.
Syntactic Foam Market Segment Analysis
By Matrix Type, Polymer Matrices Dominate Syntactic Foam Market; Hybrid Matrices to Register Fastest Growth.
Polymer matrices account for 40.62% of the market in 2025 because epoxy, polyurethane and other resin systems bond well to hollow microspheres, cast easily and offer a useful range of strength, density and cost. These foams cover most subsea buoyancy, vehicle flotation and structural core needs. Established formulations and wide supplier choice also make them the default for new designs. Recycling and reuse of old buoyancy modules is also being studied, which could favor thermoplastic matrices in coming years.
Hybrid matrices are projected to grow at a CAGR of 6.12% during 2026–2035. Systems that combine polymers with ceramic or metal phases, or with fibers, reach higher compressive strength, better temperature resistance and tailored thermal behavior. Aerospace, defense and deep subsea programs favor these designs, and development funding from agencies and operators supports new grades. Suppliers report that qualified hybrid grades are winning contracts despite their higher price, and test data from early projects is building customer confidence.
By Filler Type, Glass Microspheres Dominate Syntactic Foam Market; Ceramic Microspheres to Register Fastest Growth.
Glass microspheres hold a 76.84% share in 2025 because they combine low density, high crush strength, chemical resistance and moderate cost. Suppliers offer many grades rated for different depths, and processors know how to mix them into resins at high loadings. This depth of supply and technical knowledge makes glass the standard filler for most buoyancy modules. Long supply records from established producers give buyers confidence in batch consistency and available test data across many global projects and years.
Ceramic microspheres are expected to expand at a CAGR of 6.74% from 2026 to 2035. They tolerate higher temperatures and pressures and can form stiff, thermally stable foams for ultra-deepwater, aerospace and high-temperature insulation. Although they cost more and weigh more than glass, designers use them where glass cannot meet strength or heat needs. Producers are scaling hollow ceramic sphere output and testing lower-cost routes, which would open uses in industrial insulation and thermal protection beyond subsea work.
By Product Type, Micro-Sphere Foam Dominates Syntactic Foam Market and Is Also Set to Register Fastest Growth.
Micro-sphere foam holds a 54.81% share in 2025 because tiny hollow spheres pack tightly in a resin and deliver high compressive strength at low density, which suits deepwater service. The material machines cleanly, keeps stable properties across large blocks and is widely approved by operators and classification societies. These traits keep it at the center of subsea buoyancy. Producers can tune sphere size and loading to hit target density, so one product family can cover many depth ratings.
The category is forecast to register a CAGR of 5.89% during 2026–2035, ahead of the market. Projects are moving into deeper water, which calls for the higher strength of fine spheres, while vehicle makers want compact and predictable lift. Wider use in aerospace and defense, where precise density control matters, also raises demand for this type. Sphere suppliers are introducing tougher, lower-density grades, and casting lines are being upgraded to produce larger and more uniform parts for the deepest projects.
By Application, Marine and Subsea Dominates Syntactic Foam Market; Aerospace and Defense to Register Fastest Growth.
Marine and subsea applications account for 37.62% of the market in 2025. Buoyancy modules for risers and umbilicals, flotation for remotely operated and autonomous vehicles, towed arrays and moorings all depend on syntactic foam. Offshore operators place large and repeat orders tied to field development, and long equipment lives support replacement and refurbishment work. Operators prefer suppliers with long track records in the field, and framework agreements with subsea contractors keep volumes and replacement demand steady across project cycles.
Aerospace and defense is projected to grow at a CAGR of 7.04% during 2026–2035. Uncrewed undersea systems, naval sensors, radomes, helicopter parts and spacecraft structures need lightweight, stiff and moisture-resistant materials. Government spending on undersea capability and next-generation aircraft supports demand, and programs pay premium prices for qualified material. Interest is rising in thermal protection for spacecraft and missile structures, where low conductivity and stable shape are needed. Long-term defense contracts provide revenue visibility that supports capacity expansion.
Geography Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
85.74% |
|
Europe |
United Kingdom |
26.43% |
|
Asia Pacific |
China |
31.58% |
|
Middle East & Africa |
Saudi Arabia |
29.37% |
|
Latin America |
Brazil |
68.52% |
North America Syntactic Foam Market
North America held 36.91% of the market in 2025, led by the United States. The U.S. market was valued at USD 52.30 Million in 2025 and is expected to register a CAGR of 5.12% during 2026–2035. Gulf of Mexico deepwater developments, a large naval and undersea defense program and a deep base of aerospace suppliers create strong and varied demand for qualified buoyancy and core materials. Operators in the region also require third-party witness of pressure tests, which favors suppliers with local laboratories.
Several leading foam makers and subsea contractors operate in Texas, Louisiana and the Gulf Coast, while research institutions develop deep-sea vehicles and sensors. Canada adds offshore Atlantic projects and Mexico offshore field activity, and defense procurement rules favor suppliers with proven qualification records. Universities and research institutions in Massachusetts, California and Hawaii develop deep-diving vehicles that use custom foam. The region also hosts several rocket and spacecraft makers that buy foam for insulation and structural parts, and procurement by naval agencies adds long contracts.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Syntactic Foam Market
Europe accounted for 27.46% of the market in 2025, with the United Kingdom as the leading country. North Sea fields, Norwegian subsea developments and a deep base of buoyancy specialists in Scotland, Norway and Sweden give the region a strong supplier and customer cluster. Classification societies and engineering firms also set standards that shape global buyers. The Norwegian continental shelf alone hosts a large number of subsea tiebacks, and local suppliers maintain close ties with operators, classification societies and engineering firms.
Germany, France and Italy add demand from naval programs, aerospace suppliers and ocean research, and floating wind projects off the coasts of the United Kingdom, France and Norway are opening new uses. The region also leads in recyclable resin research, which could influence future product design. Research institutes in the Netherlands, Denmark and Spain study bio-based resins and recycling of end-of-life buoyancy modules. Offshore decommissioning of older fields also creates work to recover and reuse foam, which supports a circular approach.
Asia Pacific Syntactic Foam Market
Asia Pacific accounted for 25.18% of the market in 2025 and is the fastest growing region, with a projected CAGR of 6.58% over 2026–2035. China is the largest country, supported by deepwater exploration in the South China Sea, expanding naval and research vessel programs and a growing foam industry. Australia hosts a major supplier of subsea buoyancy and offshore gas developments. Chinese shipyards and research institutes have built crewed and uncrewed deep-sea vehicles that carry locally made foam, and state programs support the development of stronger spheres.
India, Malaysia, Indonesia and Vietnam are developing offshore fields, and Japan and South Korea add shipbuilding, ocean science and defense demand. Local manufacturers are improving quality and seeking third-party approvals, which should shift more regional projects to nearby supply. Thailand, the Philippines and Singapore host offshore service bases and fabrication yards that import foam for riser and umbilical work, and the city state is a hub for subsea contractors. New Zealand adds research vessels and marine survey activity, which keeps demand for flotation steady.
Middle East & Africa Syntactic Foam Market
Middle East & Africa held 6.12% of the market in 2025. Saudi Arabia and the United Arab Emirates lead regional demand through offshore gas and oil developments, while Egypt hosts Mediterranean gas fields and Nigeria, Angola and Ghana have deepwater programs off West Africa. Most buoyancy is imported through global contractors. Gas discoveries in the eastern Mediterranean and off East Africa are moving toward development, and these projects will need deepwater buoyancy in the coming years. Governments encourage local content, so suppliers are forming partnerships with yards.
National oil companies are investing in offshore capacity, and defense and port projects add small volumes of foam for floats and sensors. Local fabrication is limited, but joint ventures with international suppliers are emerging, and project timing remains the main driver of annual demand. Mozambique and Tanzania hold some of the largest undeveloped gas fields in Africa, and Senegal and Mauritania have started offshore production. These projects use floating units and subsea systems that will drive orders as they ramp up.
Latin America Syntactic Foam Market
Latin America held 4.33% of the market in 2025. Brazil leads, supported by the pre-salt deepwater fields that require large volumes of riser buoyancy and by a naval and offshore services industry. Guyana, with fast-growing deepwater production, and Mexico add further demand. The pre-salt cluster in the Santos and Campos basins relies on long risers, and operators plan more floating units that will require buoyancy for years. Petrobras and international partners place large orders that keep the regional supply chain active.
Argentina and Colombia are exploring offshore resources, and regional shipyards and universities support marine research. Most syntactic foam is imported or supplied by global contractors with local service bases, and currency swings and project delays remain the main constraints on regional growth. Suriname and Trinidad and Tobago are preparing further offshore developments that would add to riser and umbilical work. Cooperation between operators and local universities is building skills in composite materials and marine robotics, which should help regional suppliers over time.
Competitive Landscape
The Syntactic Foam Market is fragmented. Specialist buoyancy manufacturers, advanced materials groups, and composite fabricators compete across subsea, defense and aerospace uses, and no single supplier controls the market. Competition centers on depth ratings, third-party approvals, delivery reliability and the ability to produce large, custom shapes.
Companies pursue capacity additions, new filler and resin systems, certification programs and distribution agreements in growing regions. Partnerships with subsea contractors and defense primes are also shaping the field as customers prefer suppliers with documented test records.
Syntactic Foam Market Industry Leaders
1. Trelleborg: Swedish engineered polymer group supplying subsea buoyancy and syntactic foam.
2. Matrix Composites & Engineering: Australian maker of subsea buoyancy modules and syntactic foam.
3. DIAB Group: Swedish supplier of core materials and engineered foams.
4. Balmoral Group: UK-based supplier of buoyancy and subsea protection systems.
5. Deepwater Buoyancy: U.S. manufacturer of syntactic foam buoyancy for ROVs and subsea equipment.
Companies Covered in this Report
-
Trelleborg
-
Matrix Composites & Engineering
-
DIAB Group
-
Balmoral Group
-
Deepwater Buoyancy
-
CMT Materials
-
Base Materials
-
SynFoam
Recent Industry Developments
-
July 2025: Base Materials became the first manufacturer to receive full DNV type approval across its Subtec syntactic foam portfolio of seven grades.
-
July 2026: Matrix Composites & Engineering won a second major contract to supply subsea buoyancy modules for a project in the Gulf of Mexico.
Scope and Research Methodology
This study estimates the Syntactic Foam Market for 2025 as the base year and forecasts it through 2035. The scope covers composite materials made by filling polymer, ceramic, metal or hybrid matrices with hollow microspheres, supplied as blocks, sheets, rods, molded modules and compounds for subsea, aerospace, defense, transport and other uses. Values are reported in USD at the point of sale by foam manufacturers to contractors, equipment makers and end users. Solid buoyancy materials, conventional rigid foams and honeycomb cores are outside the scope. Segmentation covers matrix type, filler type, product type and application, and regional analysis covers five regions and major countries. Revenue is recorded in the year of sale, and intermediate transfers between affiliated plants are excluded to avoid double counting.
Secondary research included company annual reports, investor presentations and filings, energy and defense agency publications, classification society documents, patent filings, and peer-reviewed technical papers. Primary research consisted of structured interviews with executives, materials engineers, procurement heads, subsea contractors and defense program managers across the value chain. These inputs were used to validate depth ratings, material prices, order volumes and the share of each matrix, filler and application. Expert interviews were also used to test assumptions on depth ratings, density targets, qualification timelines and the pace of orders after project approvals. Responses were compared across regions to identify gaps between announced and delivered capacity.
Market size was built from the bottom up using supplier revenue and shipment data, and was cross-checked from the top down against offshore project spending, vehicle production and aerospace material demand. Triangulation across these views fixed the base year value. Forecasts consider project pipelines, defense budgets, material costs and macroeconomic conditions, and segment and regional shares were assigned from usage patterns in each setting. An analyst quality review checked consistency before release. Sensitivity tests on project delays and microsphere prices were run, and announced offshore and defense programs were risk-weighted by funding status and contract stage before being included.
Syntactic Foam Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 165.27 Million |
| Market Size by 2035 | USD 281.24 Million |
| CAGR | CAGR of 5.46% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Matrix Type (Polymer, Ceramic, Metal, and Hybrid) • By Filler Type (Glass Microspheres, Ceramic Microspheres, Polymer and Carbon Microspheres, and Others) • By Product Type (Micro-Sphere Foam and Macro-Sphere Foam) • By Application (Marine and Subsea, Aerospace and Defense, Sports and Leisure, Automotive and Transportation, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Trelleborg, Matrix Composites & Engineering, DIAB Group, Balmoral Group, Deepwater Buoyancy, CMT Materials, Base Materials, SynFoam |

Frequently Asked Questions
The Syntactic Foam Market was valued at USD 165.27 Million in 2025 and is projected to reach USD 281.24 Million by 2035, at a CAGR of 5.46%.
North America leads, with a 36.91% share in 2025, supported by Gulf of Mexico deepwater projects, naval programs and aerospace suppliers.
Asia Pacific is expected to grow fastest, at a CAGR of 6.58% during 2026–2035, led by China, Australia, India and Southeast Asia.
Polymer matrices, glass microspheres, micro-sphere foam and marine and subsea applications lead, while hybrid matrices, ceramic microspheres, micro-sphere foam and aerospace and defense grow fastest.
Trelleborg, Matrix Composites & Engineering, DIAB Group, Balmoral Group and Deepwater Buoyancy lead, along with CMT Materials, Base Materials and SynFoam.
