
Atmospheric Transport Systems Market Report Scope & Overview:
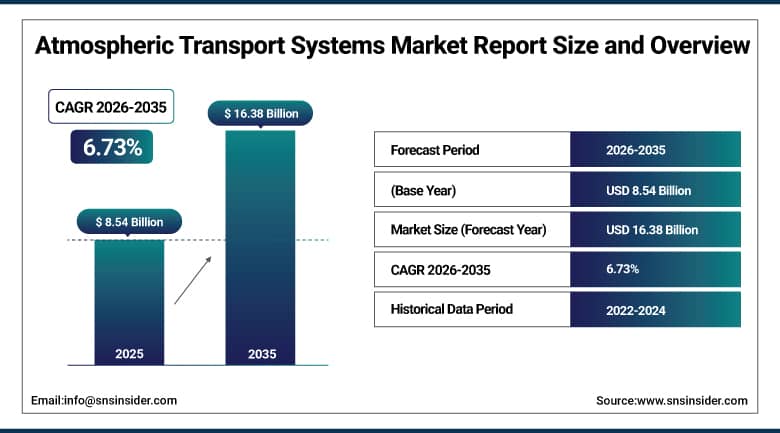
The Atmospheric Transport Systems Market was valued at USD 8.54 Billion in 2025 and is expected to reach USD 16.38 Billion by 2035, growing at a CAGR of 6.73% from 2026-2035.
The Growth in the Atmospheric Transport Systems Market can be attributed to an increase in the demand for effective, flexible, and economical aerial transport systems. The increased usage of drones in surveillance, cargo transportation, environmental monitoring, and infrastructure inspections are creating opportunities for the expansion of the market in various commercial and government sectors. Innovations in autonomous navigation, artificial intelligence, light-weight materials, and electric propulsion technology are making the process more efficient and affordable. In addition, the demand is being augmented owing to the growing need for real-time monitoring and rapid transportation in distant and hard-to-reach areas. Moreover, the growing investments in unmanned aerial systems, atmospheric mobility systems, and defense systems are adding to the growth in demand.
On November 21, 2025, Swisspod Technologies successfully tested its Aerys 1 vehicle at its hyperloop facility near Pueblo, Colorado, reaching a speed of 65 miles per hour and setting a record at what the company describes as the world's largest hyperloop test facility. The one-mile, full-scale closed-loop track is expected to support continued testing as the company works toward validating hyperloop technology for eventual commercial passenger and freight applications.
To Get More Information On Atmospheric Transport Systems Market - Request Free Sample Report
Atmospheric Transport Systems Market Trends
-
Rising private and public investment in hyperloop research and development accelerating technology validation.
-
Growing modernisation of ageing pneumatic tube infrastructure across established hospital networks.
-
Expanding interest in vacuum-based intercity transit as a genuine congestion-relief alternative.
-
Increasing government incentive support for futuristic transport pilot projects in dense urban areas.
-
Rising adoption of IoT-enabled monitoring improving reliability and maintenance planning across installed systems.
-
Growing collaboration between hyperloop developers and academic research institutions advancing propulsion technology.
U.S. Atmospheric Transport Systems Market Overview
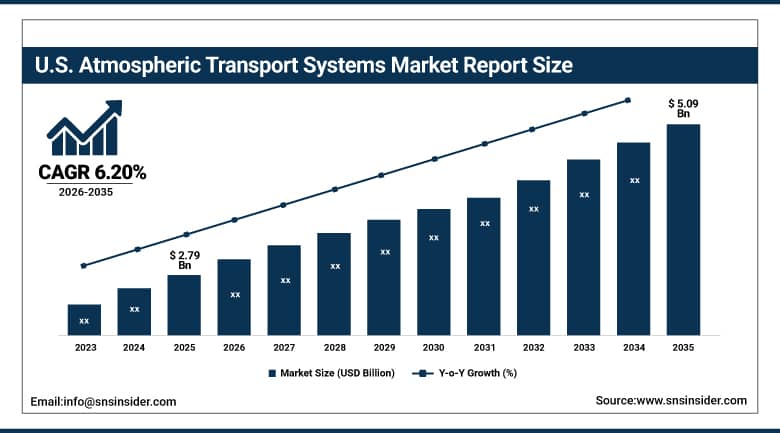
The U.S. Atmospheric Transport Systems Market was valued at USD 2.79 Billion in 2025 and is expected to reach USD 5.09 Billion by 2035, growing at a CAGR of 6.20% from 2026-2035.
Domestic demand continues to be supported by an extensive installed base of pneumatic tube infrastructure across established hospital networks, alongside a growing cluster of hyperloop test sites spanning California, Texas, Nevada, and Colorado. Continued private investment in vacuum-tube test tracks, combined with sustained academic and government research interest, continues to position the country as a key proving ground for next-generation atmospheric transport technology beyond its established healthcare logistics base.
In 2025, multiple hyperloop developers continued advancing prototype testing across U.S.-based facilities, with test programs spanning both passenger transit concepts and freight-focused applications aimed at moving shipping containers between ports at high speed. Industry observers noted that the freight-focused hyperloop concept may reach commercial viability ahead of passenger applications given its comparatively simpler regulatory and safety validation pathway.
Atmospheric Transport Systems Market Segment Analysis
-
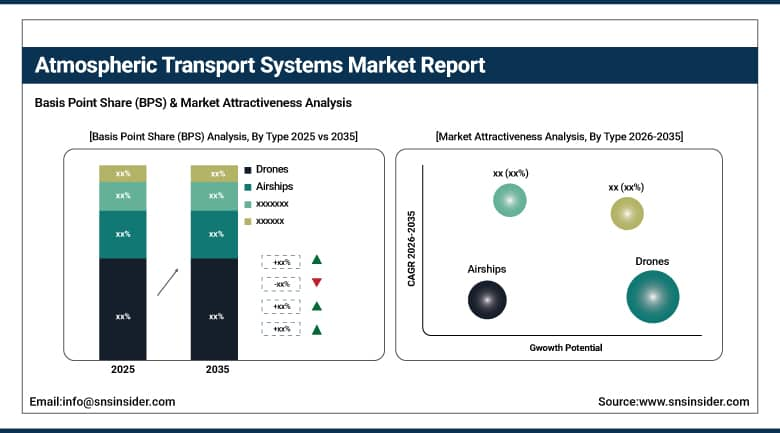
By Type, Drones segment dominated the Atmospheric Transport Systems Market in 2025 with 61% share; Airships segment is the fastest growing segment.
-
By Application, Surveillance segment dominated the Atmospheric Transport Systems Market in 2025 with 42% share; Environmental Monitoring segment is the fastest growing segment.
-
By End User, Commercial segment dominated the Atmospheric Transport Systems Market in 2025 with 53% share; Commercial segment is also the fastest growing segment.
By Type, Drones Dominate Atmospheric Transport Systems Market; Airships to Register Fastest Growth.
Drones account for a major portion of the Atmospheric Transport Systems Market owing to their cost-effectiveness, flexibility, and rapid deployment through use of the aerial platform. The capability of drones to function in different heights, equipped with unique sensors for data collection in hard-to-reach places contributes to their widespread usage. The progress made in drone autonomy, battery power, payload capacity, and remote control is increasing their effectiveness. Commercial, governmental and research organizations use drones for surveillance, mapping, inspection, data gathering and atmospheric observation purposes, which enhances the share of drones in the market.
Airships are forecasted to grow at the fastest rate, as they benefit from innovations in materials science, propulsion, autonomy, and persistent aerial operations. Their capability to stay in the air for long time while using relatively little amounts of energy makes them a perfect fit for applications that require persistent coverage and observation. Persistent surveillance, environmental monitoring, communications and remote sensing are becoming more and more popular leading to increased funding of the airship platforms. Their payload carrying capacity and vast range make airships capable of addressing atmospheric transport tasks.
By Application, Surveillance Dominates Atmospheric Transport Systems Market; Environmental Monitoring to Register Fastest Growth.
Surveillance dominate the Atmospheric Transport Systems Market since aerial platforms ensure widespread surveillance coverage, faster implementation, and surveillance at places which may not be easy to reach with traditional surveillance systems based on land. Drones and atmospheric vehicles provide surveillance for border surveillance, surveillance for protection of critical infrastructure, disaster surveillance, maritime surveillance and surveillance for security purposes by way of cameras, thermal sensors and other payloads. Security needs along with advancements in technology relating to autonomous navigation, image processing, and real-time data transmission are driving the capabilities of atmospheric transport systems for surveillance purposes.
Environmental monitoring is projected to grow at the fastest rate due to the increasing need for monitoring the environment by the government and research institutions and also by commercial organizations. Atmospheric transport platforms can be used to mount sensors that measure parameters such as air quality, greenhouse gases, temperature, humidity and particulate matter among others. Rising concerns related to climate change, pollution, degradation of ecosystems and severe weather events are some of the drivers that are fueling the demand for high resolution monitoring systems.
By End User, Commercial Dominates Atmospheric Transport Systems Market; Commercial to Register Fastest Growth.
Commercial dominate the Atmospheric Transport Systems Market since companies are adopting aerial platforms to increase efficiency, enhance monitoring capabilities, collect data, and manage infrastructure. Companies within industries such as logistics, energy, telecommunications, agriculture, mining, construction, and infrastructure are using atmospheric transport systems like drones for inspections, surveys, surveillance, and asset monitoring. The increasing availability of sensors, autonomy, and data-processing systems is increasing commercial adoption. There are efforts by many companies to reduce inspection time, operation costs, and reduce human exposure to hazardous conditions that have been driving the adoption of atmospheric transport systems commercially.
The commercial is also projected to show the fastest growth due to an increased awareness about the advantages of atmospheric transport systems in inspecting, monitoring, surveying, logistics, and data collection operations. Increased capabilities in autonomous flying, load carrying ability, communication capability, and artificial intelligence are increasing advanced commercial uses of these atmospheric transport systems. More infrastructure development, renewable energy installations, precision farming, and industrial asset monitoring are creating more demand. Increased regulation and development of aerial services are also increasing commercial uses of atmospheric transport systems.
Regional Insights
|
Region |
Major Country |
Share within Region, 2025 |
|
North America |
United States |
84.60% |
|
Europe |
Germany |
29.60% |
|
Asia Pacific |
China |
39.60% |
|
Latin America |
Brazil |
27.60% |
|
Middle East & Africa |
United Arab Emirates |
24.60% |
North America Atmospheric Transport Systems Market Insights
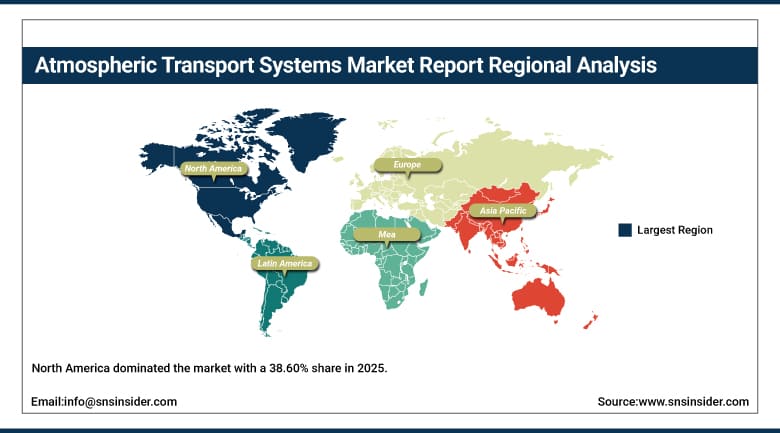
North America dominated the market with a 38.60% share in 2025. Robust healthcare infrastructure, strong investment capabilities, and a concentration of leading hyperloop and vacuum-based transport technology developers continue to anchor this leadership position. The United States in particular continues to host the largest concentration of hyperloop test facilities and pilot programs, reinforcing the region's role at the technological forefront of this emerging transport category.
Canada contributes incremental regional demand as its own healthcare and industrial infrastructure continues to modernise. Continued private investment in hyperloop test infrastructure, combined with sustained hospital pneumatic tube system replacement activity, is expected to keep North America in the lead through the forecast period, even as growth in percentage terms trails faster-scaling Asia Pacific markets.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Atmospheric Transport Systems Market Insights
Europe represents a significant share of the global market, currently sharing regional leadership with North America given the continent's robust infrastructure, strong investment capabilities, and established technological expertise. Germany's substantial industrial and healthcare infrastructure continues to anchor regional demand, reinforced by continued government and private investment in hyperloop research and development across multiple European test facilities.
France, the Netherlands, and other major European markets contribute consistent demand as national hospital networks continue extending pneumatic tube infrastructure modernisation. Continued regional collaboration on hyperloop research and development, including established test facilities within the region, continues to reinforce Europe's significant position within the broader global market.
Asia Pacific Atmospheric Transport Systems Market Insights
Asia Pacific is projected to be the fastest-growing region over the forecast period. Rapidly expanding hospital infrastructure, growing industrial facility investment, and increasing government interest in intercity transit alternatives addressing worsening urban congestion continue to accelerate regional adoption. China's substantial infrastructure investment pipeline continues to anchor regional demand across both established pneumatic tube applications and emerging vacuum-based transit pilot programs.
India's expanding hospital construction activity and growing industrial base continue to contribute meaningful regional growth. Japan and South Korea contribute additional regional scale through established manufacturing sectors and continued government research interest in next-generation transit technology, reinforcing Asia Pacific's position as the fastest-growing market for atmospheric transport systems through the forecast period.
MEA & Latin America Atmospheric Transport Systems Market Insights
The Middle East & Africa market is supported by growing hospital and industrial infrastructure investment across the United Arab Emirates and Saudi Arabia, where regional governments continue exploring next-generation transit alternatives as part of broader infrastructure diversification strategies, including publicly announced interest in hyperloop feasibility studies.
Latin America's market is anchored by Brazil, where a growing domestic healthcare and industrial sector sustains steady demand for pneumatic tube and vacuum-based transport systems. Mexico contributes further incremental growth as regional infrastructure investment continues to expand gradually.
Growth Drivers: Environmental Surveillance Demand and Hyperloop Investment
Market growth in the field is fueled by the increased demand for effective, real-time environmental surveillance, which is needed by governmental, industrial, and research bodies. The sophisticated atmospheric transport system will provide an effective solution that allows the gathering of observations and data in regions where regular infrastructure can hardly be installed. Environmental evaluation, infrastructure monitoring, disaster monitoring, and climate observation needs will fuel the demand in the future. Increasing investments in transport and vacuum transport solutions drive innovations in technology.
Increased efforts to mitigate urban traffic, transportation emissions, and conventional infrastructure dependency will drive demand in the future. Further advancements in such technologies as autonomous systems, light weight materials, electricity powered engines, and digital monitoring technology are expected.
Restraints: High Development Costs and Regulatory Uncertainty
High cost of development still remains one of the key constraints faced by transport solutions based on the atmosphere, especially for hyperloop and vacuum transportation. The development of pilots will require considerable funds for the construction of unique testing facilities, development of prototypes, the creation of advanced propulsion systems, and testing. It may slow down the process of commercialization and cause difficulties related to financing for developers of new technologies.
Uncertainty in the sphere of regulation is another major constraint, especially in case of passenger hyperloop systems. Safety certification procedures, operational guidelines, infrastructure, and other aspects of regulations are not fully developed in many regions, making the timeframe and costs of projects uncertain. Different sets of regulations might cause even greater problems for international deployment of technologies. Finally, the lack of experience and commercial operations may make investors and operators of the infrastructure more cautious.
Opportunities: Freight-Focused Hyperloop Development and Hospital Infrastructure Modernisation
The development of freight-specific hyperloop technology creates a substantial chance since developers are now actively looking into technologies that might encounter less regulatory issues than those designed for transporting people. Such freight systems will provide an opportunity to transport goods rapidly through specific tracks without causing traffic problems. Successfully launched pilots may help showcase reliability of the technology, its economic feasibility, and infrastructure viability before proceeding with passenger transportation.
Also, there is an opportunity in replacing old pneumatic tubes used by hospitals and health facilities. Higher workload, need for increased transportation of specimens and medications, and demand for faster internal logistics are the reasons why such facilities are now seeking to update their equipment. The integration with IoT sensors, tracking systems, central monitoring systems, and digital hospitals will improve the performance of the pneumatic tubes.
Recent Developments
-
2026: Swisspod set a new hyperloop speed record of 146 km/h with its AERYS 1 capsule and began development of the next-generation AERYS 2 capsule, with production planned to begin later in 2026.
-
2024: Hardt successfully completed a lane-switch test at the European Hyperloop Center, demonstrating the ability of its infrastructure to support switching between parallel hyperloop lanes.
-
2023: Zeleros and Hardt signed a strategic partnership to accelerate hyperloop deployment, establish a shared technology roadmap, and jointly test hyperloop technologies at facilities in Spain and the Netherlands.
Atmospheric Transport Systems Companies are:
-
Swisslog Holding AG
-
Translogic (Swisslog)
-
Pevco Systems International
-
Hyperloop Transportation Technologies, Inc.
-
TransPod Inc.
-
Hardt Hyperloop B.V.
-
Swisspod Technologies
-
Sumetzberger GmbH
-
Quirepace Ltd.
-
Air-Log International GmbH
-
PTS Pneumatic Tube Systems
-
Halton Group
-
Nevomo
-
MEDNET GmbH
-
Diamond Systems
-
The Boring Company
-
Hardt B.V.
-
Zephyr Hyperloop
Atmospheric Transport Systems Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 8.54 Billion |
| Market Size by 2035 | USD 16.38 Billion |
| CAGR | CAGR of 6.73% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (Airships, Drones, Balloons, Others) • By Application (Cargo Transport, Surveillance, Environmental Monitoring, Others) • By End User (Commercial, Military, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Swisslog Holding AG, Translogic (Swisslog), Pevco Systems International, Hyperloop Transportation Technologies, Inc., TransPod Inc., Zeleros, Hardt Hyperloop B.V., Swisspod Technologies, Sumetzberger GmbH, Quirepace Ltd., Air-Log International GmbH, PTS Pneumatic Tube Systems, Halton Group, Nevomo, Aerofex Corporation, MEDNET GmbH, Diamond Systems, The Boring Company, Hardt B.V., Zephyr Hyperloop |
Frequently Asked Questions
Key players include Swisslog Holding AG, Pevco Systems International, Hyperloop Transportation Technologies, Inc., TransPod Inc., Hardt Hyperloop B.V., and Swisspod Technologies, among other infrastructure and technology developers.
Continued development of freight-focused hyperloop applications and continued modernisation of ageing hospital pneumatic tube infrastructure represent the primary opportunities for providers.
Growth is primarily driven by increasing demand for environmental surveillance combined with rising private and public investment in hyperloop and vacuum-based transport innovation.
By Type, Drones dominated the Atmospheric Transport Systems Market in 2025
North America dominated the market with a 38.60% share in 2025, supported by robust healthcare infrastructure and a concentration of leading hyperloop technology developers.
