
Through-Hole Passive Components Market Report Scope & Overview:
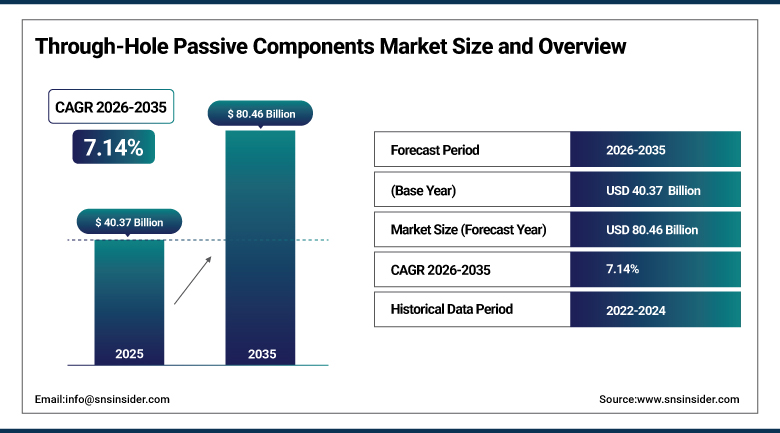
The Through-Hole Passive Components Market was valued at USD 40.37 Billion in 2025 and is expected to reach USD 80.46 Billion by 2035, growing at a CAGR of 7.14% from 2026-2035.
The Through-Hole Passive Components Market covers resistors, capacitors, inductors, diodes, transducers and sensors whose wire leads pass through holes in a printed circuit board and are soldered on the opposite side. Although surface mount parts dominate consumer miniaturization, leaded components remain indispensable where power handling, voltage rating, mechanical strength, heat dissipation or easy repair matter. Power supplies, motor drives, industrial controls, aerospace electronics, audio equipment, appliances and automotive modules continue to specify them. Demand is supported by electrification, energy storage and high-reliability programs, while automated assembly and shrinking boards slow growth in simpler consumer products through 2035. Suppliers that combine qualified quality systems with dependable delivery are best placed to benefit.
⮞The Electronic Components Industry Association reported in October 2026 that 61% to 63% of respondents to its September 2026 survey saw rising lead-time pressure for passive and electro-mechanical components, and none reported declining pressure.
To Get more information Through-Hole Passive Components Market - Request Free Sample Report
Through-Hole Passive Components Market Trends
-
Film capacitors rated for silicon carbide and gallium nitride converters are being offered in radial through-hole packages with high ripple current capability.
-
Lead-type multilayer ceramic capacitors with higher capacitance are moving into 48 V automotive and industrial power systems.
-
Precision and high-power wirewound resistors are gaining use in test equipment, charging infrastructure and battery storage cabinets.
-
Automotive qualification to AEC-Q200 is spreading across leaded safety capacitors and resistors as vehicle power electronics expand.
-
Right-to-repair rules and maker communities are sustaining demand for easily replaced and easily soldered leaded parts.
U.S. Through-Hole Passive Components Market Outlook
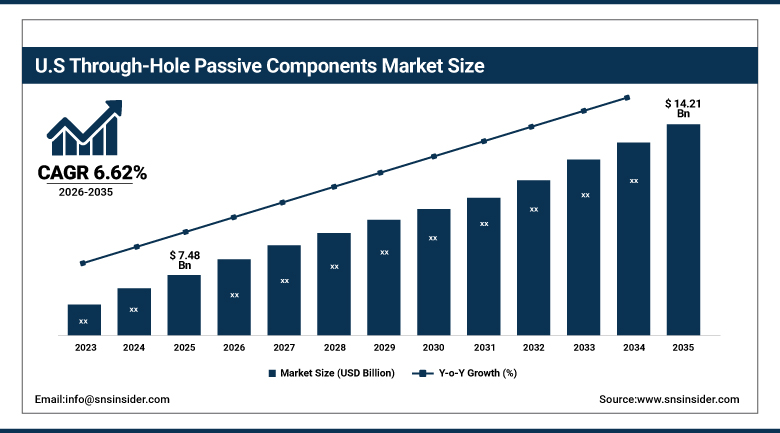
The U.S. Through-Hole Passive Components Market was valued at USD 7.48 Billion in 2025 and is expected to reach USD 14.21 Billion by 2035, growing at a CAGR of 6.62% from 2026-2035.
The U.S. Through-Hole Passive Components Market is the largest national market in North America, supported by a strong base of aerospace, defense, medical, industrial power and test equipment manufacturers that favor leaded parts for reliability and repairability. Catalog distributors supply small quantities quickly to engineers, repair shops and hobbyists. Electric vehicle charging, battery storage and data center power systems use large leaded capacitors and wirewound resistors, while federal programs to rebuild electronics manufacturing capacity support local sourcing of qualified components. Long product lifecycles in defense and infrastructure sustain replacement demand through 2035. Local distributors also stock deep catalogs of obsolete and specialty values for sustainment programs.
⮞The Global Electronics Association reported on 30 September 2026 that North American printed circuit board shipments rose 23.5% year on year in August 2026, with a three-month book-to-bill ratio of 1.29.
Through-Hole Passive Components Market Segment Analysis
-
By Component, the Capacitors segment dominated the Through-Hole Passive Components Market with approximately 42.38% share in 2025, while the Sensors segment is the fastest growing with a CAGR of approximately 11.86%.
-
By Lead Model, the Axial segment dominated the Through-Hole Passive Components Market with approximately 74.38% share in 2025 and is also the fastest growing with a CAGR of approximately 7.93%.
-
By Application, the Consumer Electronics segment dominated the Through-Hole Passive Components Market with approximately 31.27% share in 2025, while the Industrial segment is the fastest growing with a CAGR of approximately 9.74%.
-
By Material, the Ceramic segment dominated the Through-Hole Passive Components Market with approximately 38.62% share in 2025, while the Tantalum segment is the fastest growing with a CAGR of approximately 8.76%.
By Component, Capacitors Dominate the Through-Hole Passive Components Market and Sensors Grow Fastest
Capacitors hold approximately 42.38% of the Through-Hole Passive Components Market in 2025 because leaded aluminum electrolytic, film and ceramic disc types are used for bulk energy storage, filtering, snubbing and noise suppression in nearly every power circuit. Radial and snap-in electrolytics provide high capacitance at low cost for power supplies, drives and amplifiers, while metallized film types offer long life and self-healing behavior for mains and DC-link duty. Higher voltage ratings, vibration tolerance and the heat dissipation of leaded packages make them a natural fit for inverters, chargers and appliances. Product families in this group are expected to remain stable through 2035.
Sensors are the fastest growing component, with a CAGR of approximately 11.86% during 2026-2035. Leaded temperature, current, humidity and magnetic sensors are built into appliances, motors, battery packs and industrial machinery where sturdy connections and simple replacement are valued. Thermistors, Hall devices and reed types in through-hole packages are used in monitoring circuits for chargers, heating elements and pumps. Smart factory programs, predictive maintenance and electrification add many measuring points, and designers prefer robust leaded packages for harsh, high-vibration or high-temperature locations. Specialist suppliers with long product histories retain loyal customer bases in these categories.
⮞Lawrence Berkeley National Laboratory reported in June 2026 that U.S. data centers could use 11.8% of national electricity by 2030, with a reference case of 649 terawatt-hours, driving demand for power supply capacitors.
By Lead Model, Axial Dominates the Through-Hole Passive Components Market and Also Grows Fastest
Axial leaded parts account for approximately 74.38% of the market in 2025 because resistors, diodes, fuses and many inductors and capacitors are produced with a lead at each end, which suits automated taping, reel packaging and board insertion. Axial resistors in carbon film, metal film and wirewound constructions handle a wide span of power ratings and remain the standard for prototypes, repair work, audio and power equipment. Their long history of use means designers, distributors and assembly lines are all familiar with the format. Product families in this group are expected to remain stable through 2035.
Axial is also the fastest growing lead model, at a CAGR of approximately 7.93% during 2026-2035. High-reliability aerospace, defense, medical and industrial customers prefer axial wirewound, precision and fusible resistors because they dissipate heat well, tolerate shock and can be qualified to demanding standards. Energy storage and charging equipment add demand for high-power wirewound parts. Radial formats continue to serve electrolytic and film capacitors, but the breadth of axial products, together with strong requirements from repair and legacy systems, keeps the format ahead. Specialist suppliers with long product histories retain loyal customer bases in these categories.
⮞Airbus reported on 12 January 2026 that it delivered 793 commercial aircraft in 2025, up 4%, and ended the year with a record backlog of 8,754 aircraft.
By Application, Consumer Electronics Dominates the Through-Hole Passive Components Market and Industrial Grows Fastest
Consumer electronics account for approximately 31.27% of the market in 2025, reflecting large volumes of leaded components in appliances, audio equipment, televisions, chargers, power adapters, lighting and hobby electronics. Products with large power sections, such as washing machines, air conditioners, microwave ovens and amplifiers, favor through-hole capacitors, resistors and chokes for their ability to withstand heat and electrical stress. Do-it-yourself and repair communities buy leaded parts for their ease of soldering. Even as miniaturization grows, the sheer scale of appliance production keeps consumer demand the largest. Product families in this group are expected to remain stable through 2035.
Industrial applications are the fastest growing, with a CAGR of approximately 9.74% through 2035. Motor drives, programmable controllers, power supplies, welding equipment, process instruments and renewable energy inverters use leaded components that withstand vibration, high voltage and wide temperature swings. Factory automation, energy storage, robotics and charging infrastructure are expanding the installed base of such equipment. Industrial customers also value long product availability and repairability, which suit established leaded part families with stable specifications and qualified second sources. Qualified second sources reduce supply risk for these long-running programs.
⮞The Consumer Technology Association projected on 4 January 2026 that U.S. consumer technology unit shipments would grow 0.7% in 2026, with hardware up 3.4%.
By Material, Ceramic Dominates the Through-Hole Passive Components Market and Tantalum Grows Fastest
Ceramic materials hold approximately 38.62% share in 2025 because ceramic disc and multilayer capacitors, as well as ceramic-based resistors and varistors, are inexpensive and stable across a wide range of voltages and frequencies. Lead-type multilayer ceramics are used in power conversion, decoupling and snubber circuits, and high-voltage ceramic discs serve in power supplies, ignition systems and lighting ballasts. Their low losses, small size per unit of capacitance and broad supplier base make them an easy default for designers, while resin-molded leaded packaging adds durability for automotive and industrial uses. Product families in this group are expected to remain stable through 2035.
Tantalum is the fastest growing material, advancing at a CAGR of approximately 8.76% during 2026-2035. Leaded tantalum capacitors offer high capacitance in small volumes, stable performance over temperature and long life, which suits medical, aerospace, military and industrial equipment where failure is costly. Polymer variants lower the risk of ignition failure and allow higher voltage ratings. Supply concerns around raw materials and responsible sourcing remain important, but demand from defense electronics, telecommunications infrastructure and instrumentation keeps tantalum growing faster than the overall market. Specialist suppliers with long product histories retain loyal customer bases in these categories.
⮞The Japan Electronics and Information Technology Industries Association reported that Japanese passive component production in February 2026 was 91.5% of the level a year earlier.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
86.50% |
|
Asia Pacific |
China |
44.28% |
|
Europe |
Germany |
25.14% |
|
Latin America |
Brazil |
48.67% |
|
Middle East & Africa |
United Arab Emirates |
29.35% |
North America Through-Hole Passive Components Market Insights
North America held approximately 21.43% of the Through-Hole Passive Components Market in 2025, with the United States accounting for about 86.50% of regional demand and Canada the balance. Aerospace, defense, medical, industrial power and test equipment makers use leaded parts for reliability, serviceability and traceability. Distributors with broad inventories serve engineers, repair shops and educators, and demand from hobbyists and prototype builders adds a steady base of small orders. Energy storage and charging projects contribute to purchases of high-voltage capacitors and power resistors. Suppliers localize inventory to shorten delivery times and support service networks.
Long-lifecycle products, including avionics, military radios, medical imaging systems and industrial controls, are maintained and repaired for decades, creating a recurring need for exact replacement leaded parts. Canada adds demand through mining equipment, rail and power utilities. Regional production of power electronics for data centers and grid equipment is increasing, supported by public funding for manufacturing, and buyers emphasize supply chain transparency and qualification documents when selecting suppliers. Distributors with same-day shipping remain a decisive advantage for engineers who buy small quantities.
⮞The U.S. Energy Information Administration reported on 20 February 2026 that developers planned 24 gigawatts of utility-scale battery storage additions in 2026, up from a record 15 gigawatts in 2025.
Europe Through-Hole Passive Components Market Insights
Europe accounted for approximately 19.65% of the Through-Hole Passive Components Market in 2025, led by Germany, the United Kingdom, France and Italy. The region has a strong base of industrial automation, power electronics, automotive, rail, aerospace and medical equipment makers that value robust components, and several well-known film capacitor and inductor specialists operate there. Regulations on product repairability and energy efficiency encourage designs that use replaceable, serviceable parts, while safety standards for mains-connected equipment sustain demand for certified X and Y capacitors and fusible resistors. Suppliers localize inventory to shorten delivery times and support service networks.
Germany leads through machinery, drives and automotive electronics, and the Nordic countries contribute through renewable energy and marine equipment. Eastern European nations host expanding assembly plants for appliances and vehicles. Defense spending increases across the continent are lifting orders for high-reliability components for radar, communications and munitions electronics. Electric vehicle charging networks and heat pump adoption add power conversion equipment that uses leaded film and electrolytic capacitors, and local distributors maintain deep stocks for service and maintenance needs. Compliance with safety and environmental directives remains a prerequisite for market entry.
⮞The European Automobile Manufacturers' Association reported on 27 January 2026 that battery-electric cars reached a 17.4% share of EU registrations in 2025, up from 13.6% in 2024.
Asia Pacific Through-Hole Passive Components Market Insights
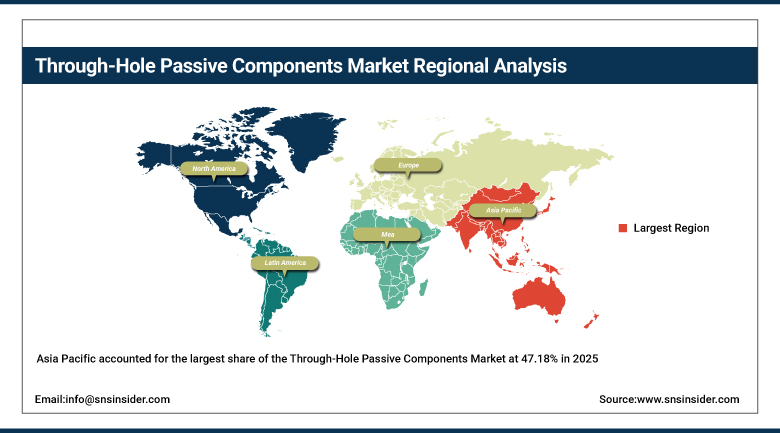
Asia Pacific accounted for the largest share of the Through-Hole Passive Components Market at 47.18% in 2025 and is also the fastest growing region, with a CAGR of 8.47% during 2026-2035. China, Japan, South Korea, Taiwan and India combine large appliance, power supply, lighting and industrial equipment production with a dense base of component manufacturers. Many leading aluminum electrolytic, film and resistor makers operate plants in the region, which keeps prices competitive. Rapid growth in electric vehicles, renewable energy and industrial automation raises demand for high-voltage and high-power leaded parts. Suppliers localize inventory to shorten delivery times and support service networks.
China is the largest country market, supported by appliances, power adapters, inverters and charging equipment, and by a large base of local component suppliers. Japan contributes premium capacitors and resistors for automotive, industrial and audio uses. India is expanding quickly through electronics manufacturing incentives, solar inverter assembly and appliance production. Taiwan and South Korea add demand through power supplies and display equipment, while Vietnam, Thailand and Malaysia host growing assembly clusters that import leaded components in volume. Local content rules and export incentives continue to shape sourcing decisions across the region.
⮞The China Association of Automobile Manufacturers reported on 15 January 2026 that China produced 34.531 million vehicles in 2025, up 10.4%.
Get Customized Report as per Your Business Requirement - Enquiry Now
MEA & Latin America Through-Hole Passive Components Market Insights
The Middle East and Africa and Latin America together account for approximately 11.74% of the Through-Hole Passive Components Market in 2025, with the Middle East and Africa at 5.94% and Latin America at 5.80%. Both regions import most components, and demand follows assembly of appliances, power equipment, telecom gear and vehicles. In the Middle East, Saudi Arabia and the United Arab Emirates are investing in solar plants, grid upgrades and industrial zones that need power conversion hardware. Africa is led by South Africa, Egypt and Nigeria, where repair markets and off-grid solar kits drive use of simple leaded parts. Imports from Asia Pacific supply the bulk of requirements in both regions.
Latin America is led by Brazil and Mexico. Brazil has appliance, automotive and power equipment manufacturing supported by local content rules, while Mexico acts as an assembly hub for appliances, vehicles and industrial equipment serving the United States. Argentina, Colombia and Chile add demand through mining, agriculture machinery and renewable energy. Independent repair shops and electronics hobbyists are significant buyers of leaded components, and distributors play an essential role in reaching small manufacturers with limited purchasing power. Rising electrification of rural areas is expanding the base of installed power equipment that needs spares.
⮞The International Renewable Energy Agency reported in April 2026 that Africa added a record 11.3 gigawatts of renewable capacity in 2025, while Middle East renewable capacity grew 28.9%.
Market Dynamics
Growth Drivers: Electrification and Power Electronics Drive Growth in the Through-Hole Passive Components Market
Electrification is the strongest force behind the Through-Hole Passive Components Market. Electric vehicle chargers, onboard power units, solar inverters, battery storage systems and heat pumps all contain power stages that rely on large capacitors, high-power resistors and chokes. Leaded packages handle high voltages, large currents and heat more easily than small surface mount parts, and their mechanical strength survives vibration. As voltage levels rise to improve efficiency, designers need components with greater creepage distances and higher ratings, which favors through-hole constructions. These pressures shape purchasing decisions and design choices across the supply chain.
Industrial automation and data center power provide a second driver. Motor drives, servo systems, uninterruptible power supplies and server power shelves require DC-link and filter capacitors, snubbers and braking resistors with long life. Wide-bandgap semiconductors switch faster and demand low-inductance film capacitors designed for high ripple current. Maintenance and retrofit programs for installed equipment also create replacement demand, and manufacturers of ruggedized systems continue to specify leaded parts for ease of inspection and repair. Utilities and grid equipment makers add steady orders for large filter and snubber parts.
⮞The International Energy Agency reported in May 2026 that electric car sales exceeded 20 million in 2025, about one in four new cars, with 23 million projected for 2026.
Restraints: Surface Mount Miniaturization and Raw Material Costs Restrain Growth in the Through-Hole Passive Components Market
The shift to surface mount technology is the main restraint on the Through-Hole Passive Components Market. Automated pick-and-place lines place small components faster and at lower cost than insertion machines, and compact devices such as smartphones, wearables and many appliances leave little board space for leaded parts. Manufacturers that redesign products for surface mount remove through-hole parts from bills of materials, and suppliers of leaded components must serve a shrinking set of simple applications. Hybrid assembly also adds process steps that some factories avoid. These pressures shape purchasing decisions and design choices across the supply chain.
Raw material costs add pressure. Aluminum foil, electrolyte, tantalum powder, copper, precious metals in resistor elements and polypropylene film all see price swings, and suppliers have raised prices as orders exceed capacity. Competition from low-cost producers compresses margins on commodity parts, while qualification costs for automotive and aerospace grades are high. Environmental rules on hazardous substances and the burden of recycling electrolytic capacitors also influence design choices and encourage alternatives. Currency swings and freight costs further squeeze importers of finished components.
⮞The World Bank forecast on 28 April 2026 that the 2026 average aluminum price would rise 21.6% from 2025.
Opportunities: Aerospace, Defense and Repair Culture Create Opportunities in the Through-Hole Passive Components Market
Aerospace and defense programs create a major opportunity. Radar, communications, avionics and munitions electronics require components that withstand shock, temperature extremes and long storage, and leaded parts with documented qualification are frequently specified. Rising defense budgets in Europe, Asia and North America are funding new platforms and upgrades, and long service lives mean spare parts are bought for decades. Suppliers that hold high-reliability certifications and can offer traceability, screening and lot-level documentation command premium prices and win multi-year contracts. Government funding for local electronics manufacturing further supports qualified local supply.
Repair, education and hobby markets add further openings. Legislation that gives consumers a right to repair, along with growing communities of makers and students learning electronics, increases demand for easily replaced and easily soldered parts. Online marketplaces and kit makers sell assortments of resistors and capacitors to these audiences. Energy storage and grid equipment, medical devices and instrumentation also continue to use leaded components, giving suppliers diverse end markets that cushion cyclical swings in consumer electronics. Medical imaging, laboratory instruments and test equipment also rely on proven leaded parts.
⮞The Stockholm International Peace Research Institute reported on 27 April 2026 that world military spending rose 2.9% in real terms in 2025, the 11th consecutive annual increase.
Recent Developments:
-
2025: Bourns launched a precision wirewound resistor line under the Riedon brand, offered in axial, radial and square packages with leads, with values up to 6 MΩ, tolerance of ±0.005% and a temperature coefficient of ±2 ppm per degree Celsius.
-
2026: YAGEO introduced the R41D V234 series of high-current Y2 and X1 film capacitors for silicon carbide and gallium nitride power systems, supplied in radial through-hole packages at 10,15 and 22.5 mm lead pitch.
-
2026: Murata began mass production of the RCE and RDE lead-type 10 µF, 100 Vdc X7S multilayer ceramic capacitors, which are resin-molded for 48 V automotive and industrial power and raise the maximum capacitance of its 100 V lead-type range from 4.7 µF.
-
2026: TDK introduced the B3201 Y1 metallized polypropylene film safety capacitors rated at 500 V AC and 1500 V DC, from 0.47 to 33 nF, qualified to AEC-Q200 and supplied with parallel wire leads at 15 and 22.5 mm pitch.
Through-Hole Passive Components Market Key Players are:
-
Vishay Intertechnology, Inc.
-
YAGEO Corporation (KEMET)
-
Murata Manufacturing Co., Ltd.
-
TDK Corporation
-
Panasonic Industry Co., Ltd.
-
Nichicon Corporation
-
Rubycon Corporation
-
Nippon Chemi-Con Corporation
-
Bourns, Inc.
-
Würth Elektronik GmbH & Co. KG
-
TE Connectivity Ltd.
-
KYOCERA AVX Components Corporation
-
WIMA GmbH & Co. KG
-
Ohmite Manufacturing Company
-
Samwha Capacitor Co., Ltd.
-
Lelon Electronics Corp.
-
Nantong Jianghai Capacitor Co., Ltd.
Through-Hole Passive Components Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 40.37 Billion |
| Market Size by 2035 | USD 80.46 Billion |
| CAGR | CAGR of 7.14% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Component (Resistors, Capacitors, Inductors, Diodes, Transducers, Sensors, and Others) • By Lead Model (Axial and Radial) • By Application (Consumer Electronics, IT and Telecom, Automotive, Industrial, Aerospace and Defense, Healthcare, and Others) • By Material (Ceramic, Film, Metal, and Tantalum) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Vishay Intertechnology, Inc., YAGEO Corporation (KEMET), Murata Manufacturing Co., Ltd., TDK Corporation, Panasonic Industry Co., Ltd., Nichicon Corporation, Rubycon Corporation, Nippon Chemi-Con Corporation, Bourns, Inc., Würth Elektronik GmbH & Co. KG, TE Connectivity Ltd., KYOCERA AVX Components Corporation, WIMA GmbH & Co. KG, Ohmite Manufacturing Company, Samwha Capacitor Co., Ltd., Lelon Electronics Corp., Nantong Jianghai Capacitor Co., Ltd. |

Frequently Asked Questions
The key players in the Through-Hole Passive Components Market include Vishay Intertechnology, Inc., YAGEO Corporation, Murata Manufacturing Co., Ltd., TDK Corporation, Panasonic Industry Co., Ltd., among others.
Key opportunities include aerospace and defense programs that need qualified leaded parts, right-to-repair legislation and maker communities, and energy storage and grid equipment.
The major growth factor is electrification, including electric vehicle charging, solar inverters, battery storage and industrial drives that rely on high-voltage, high-power leaded components.
The Capacitors segment dominated the Through-Hole Passive Components Market with approximately 42.38% share in 2025, because leaded electrolytic, film and ceramic types serve bulk storage and filtering in almost every power circuit.
Asia Pacific dominated the Through-Hole Passive Components Market with a 47.18% share in 2025, driven by appliance, power supply and industrial equipment production in China, Japan, South Korea, Taiwan and India.
