
Truck Platooning Market Report Scope & Overview:
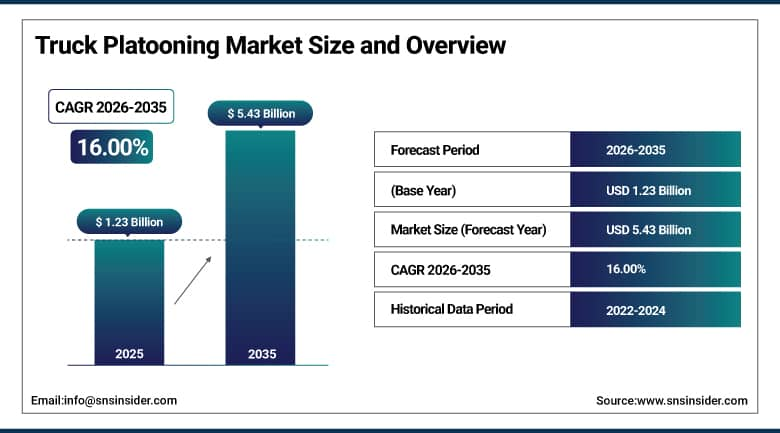
The Truck Platooning Market was valued at USD 1.23 Billion in 2025 and is expected to reach USD 5.43 Billion by 2035, growing at a CAGR of 16.00% from 2026-2035.
Truck Platooning Market growth is being primarily fueled by efforts on the part of logistics companies to achieve increased efficiencies and savings from the use of fuel, as the technology used with connected vehicles allows one truck to act as a guide to the others, coordinating the braking and acceleration, thereby cutting down the drag and lowering fuel consumption. More stringent greenhouse gas emissions guidelines and adequately funded pilot program interstate corridors continue to position platooning as a legitimate approach to reducing emissions for freight carriers, helped along by the development of increasingly efficient communication standards for vehicles capable of less than 50 milliseconds of latency.
The driver shortage that continues to plague the trucking industry is driving demand further, as it has made more and more companies turn to technologies to increase their driver efficiency and throughput. Growth prospects look good with an increased emphasis on testing corridors by governments and development of adaptive cruise control and vehicle-to-vehicle communication technologies, despite the shift of the industry as a whole towards standalone Level 4 autonomy for trucks.
In April 2025, Kratos Defense & Security Solutions expanded its truck platooning systems along Interstate 70 in Ohio and Indiana, in coordination with DriveOhio and the Indiana Department of Transportation.
To Get More Information On Truck Platooning Market - Request Free Sample Report
Truck Platooning Market Trends
- Continued interstate corridor pilot programs testing driver-assistive platooning technology in real-world freight operations.
- Growing industry focus shifting from multi-truck platooning toward standalone Level 4 autonomous trucking.
- Rising adoption of 5G-enabled vehicle-to-vehicle communication supporting sub-50 millisecond platooning latency.
- Increasing development of integrated platooning software solutions for fleet management and coordination.
- Expanding partnerships between technology firms and truck manufacturers to advance connected vehicle capability.
U.S. Truck Platooning Market Outlook
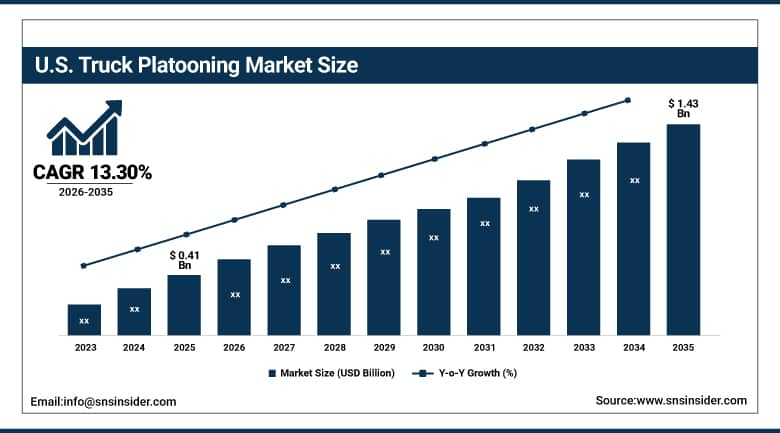
The U.S. Truck Platooning Market was valued at USD 0.41 Billion in 2025 and is expected to reach USD 1.43 Billion by 2035, growing at a CAGR of 13.30% from 2026-2035.
The U.S. Truck Platooning Market growth continues to be reinforced by commercial deployment authorization across a majority of U.S. states, supportive interstate corridor pilot programs, and growing adoption of automation technology driven by fuel efficiency and driver productivity considerations. Domestic demand also benefits from active testing partnerships between state transportation departments and technology providers along key freight corridors. It is worth noting that broader industry momentum in the United States has increasingly shifted toward standalone Level 4 autonomous trucking rather than multi-truck platooning specifically, as companies pursuing full autonomy have begun commercial driverless operations on select interstate corridors, a dynamic that is reshaping the competitive and investment landscape surrounding connected truck technology more broadly.
Commercial deployment of truck platooning technology is currently permitted across the majority of U.S. states, enabling trucks to operate across extensive interstate corridors under supportive regulatory frameworks. Continued state-level investment in testing infrastructure, including corridor programs coordinated with departments of transportation, continues to support domestic platform validation even as autonomous trucking developers increasingly pursue driverless, single-truck commercial operations as an alternative technology pathway.
Truck Platooning Market Segment Analysis
- By Truck Class, the Class-8 segment dominated the Truck Platooning Market with approximately 74.50% share in 2025, while the Class 6-7 segment is the fastest growing with a CAGR of approximately 17.80%.
- By Platooning Type, the Driver-Assistive Truck Platooning segment dominated the Truck Platooning Market with approximately 68.50% share in 2025, while the Autonomous Truck Platooning segment is the fastest growing with a CAGR of approximately 22.72%.
- By Application, the Long-Haul/Line-Haul segment dominated the Truck Platooning Market with approximately 58.50% share in 2025, while the Regional Freight & Distribution is the fastest growing with a CAGR of approximately 24.3%.
- By Component, the Hardware segment dominated the Truck Platooning Market with approximately 47.02% share in 2025, while the Software segment is the fastest growing with a CAGR of approximately 23.3%.
By Truck Class, Class-8 dominates and Class 6-7 grows fastest
Class-8 trucks remain the dominant truck class segment within the Truck Platooning Market, reflecting their predominant use in long-haul freight transportation where the fuel efficiency and productivity benefits of platooning are most economically significant. This segment benefits from the scale of long-haul Class-8 freight operations, where even modest per-mile fuel savings translate into substantial fleet-wide cost reduction.
Class 6-7 trucks are emerging as the fastest-growing truck class segment, driven by growing interest in extending platooning technology to medium-duty regional distribution and delivery applications beyond traditional long-haul trucking. This segment focuses on adapting platooning technology to the shorter routes and more frequent stops characteristic of regional and last-mile freight operations, positioning Class 6-7 trucks to capture growing demand as platooning technology providers expand beyond their traditional long-haul focus.
By Platooning Type, Driver-Assistive dominates and Autonomous grows fastest
Driver-Assistive Truck Platooning is still the largest platooning type segment of the Truck Platooning Market, considering higher acceptance and technological maturity compared to autonomous solutions, as professional drivers operate both leading and trailing trucks in order to ensure their safety and proper operation. The Driver-Assistive Truck Platooning segment enjoys well-developed technologies such as vehicle-to-vehicle communication and adaptive cruise control which have been already confirmed in various pilot programs covering different interstate corridors.
Autonomous Truck Platooning is set to become one of the most rapidly developing segments of the Truck Platooning Market, fueled by advancements in sensor fusion, machine learning, and autonomous driving technologies which expand platooning potentialities into human oversight reduction sphere. This segment specializes in the incorporation of increasingly sophisticated autonomous driving software into platooning systems, thus making autonomous platooning an attractive option to receive further investments along with the development of autonomous trucking market as a whole.
By Application, Long-Haul/Line-Haul dominates and Emergency Services grows fastest
Long-Haul/Line-Haul remains the largest application segment of the Truck Platooning Market owing to the considerable cost and efficiency advantages that truck platooning solutions offer in long interstate freight routes. Such an application segment enjoys strong support from the well-developed infrastructure and regulatory environment along interstate corridors, which facilitate the deployment of commercial truck platooning.
The Regional Freight & Distribution will be the fastest-growing application segment. The growth of this segment is fueled by the growth of e-commerce businesses, increased demand for fast transportation of goods, and development of regional logistic corridors that connect hubs with hubs. Also, shorter and predictable routes make good conditions for deployment of the connected and automated platooning technologies.
By Component, Hardware dominates and Software grows fastest
The share of Hardware is highest in the Truck Platooning Market in 2025. The dominance of this component in the market is attributed to the indispensable nature of sensors, radars, cameras, electronic control units, positioning systems, and V2V communication modules, which facilitate the operation of trucks together. The mounting use of driver assistance and connected vehicle solutions also fuels the need for hardware components in platooning enabled commercial vehicles.
The Software is projected to emerge as the fastest growing component from 2026 to 2035. The rising demand for solutions such as platoon formation, cooperative adaptive cruise control, fleet orchestration, vehicle coordination, diagnostics, and automation drives the growth of the software solution segment. The growing trend towards autonomous platooning and connected freight operations is likely to drive its growth in the future.
Regional Insights
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
82.50% |
|
Asia Pacific |
China |
44.60% |
|
Europe |
Germany |
32.80% |
|
Latin America |
Brazil |
38.60% |
|
Middle East & Africa |
United Arab Emirates |
41.20% |
North America Truck Platooning Market Insights
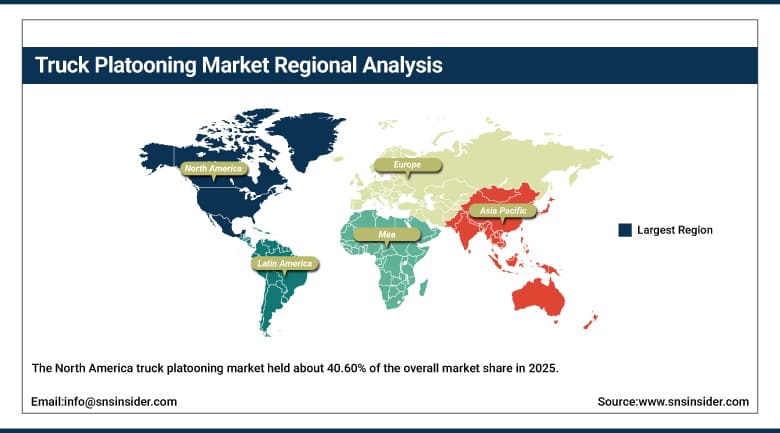
The North America truck platooning market held about 40.60% of the overall market share in 2025 owing to the presence of favorable regulations, successful interstate tests, and the authorization of commercial operation in most of the U.S. states. The United States makes up for a large percentage of demand in the region owing to the involvement of testing corridors in each state.
Canada adds to the demand from the region by being a part of the North American freight network. Owing to this, North America emerges as the biggest regional market for truck platooning technology.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Truck Platooning Market Insights
Asia Pacific is projected to expand at the fastest CAGR of around 24.25% across the Truck Platooning Market during the 2026-2035 forecast period, reflecting rising interest in advanced transportation technologies and growing government support for connected and autonomous vehicle development. China represents the largest single contributor within the region, supported by substantial government investment in autonomous vehicle infrastructure and domestic technology development.
Japan and South Korea contribute additional regional demand, supported by established automotive technology manufacturing bases and growing interest in freight efficiency solutions. Continued regional investment in vehicle-to-vehicle communication infrastructure further reinforces Asia Pacific's position as the fastest-growing global market for truck platooning technology.
Europe Truck Platooning Market Insights
Europe is another important region that holds potential for the development of truck platooning due to the presence of the largest commercial vehicle manufacturer and numerous trucking firms in Germany that have been investing in connected vehicles. The proportion of Germany in the European region is determined by the fact that the region accounts for much of the commercial vehicle production and has homegrown firms developing platooning technology.
Vehicle safety technology is promoted in the European region via General Safety Regulation issued by the European Automobile Manufacturers Association. Additional regional demand from France and the Netherlands can be explained by the existence of freight transport corridors that fit the needs of the technology.
MEA & Latin America Truck Platooning Market Insights
The Middle East & Africa region remains a smaller contributor to global demand, with growth concentrated in Gulf Cooperation Council markets such as the United Arab Emirates, where expanding logistics infrastructure investment is gradually increasing interest in connected freight technology. Broader regional demand remains limited relative to North America, Europe, and Asia Pacific, reflecting the technology's concentrated presence in markets with more advanced regulatory frameworks.
Latin America's Truck Platooning Market is led by Brazil, which accounts for the majority of regional demand on the strength of its large domestic freight transportation sector and growing interest in fuel efficiency technology. Gradual expansion of interstate freight corridor infrastructure continues to support steady regional demand growth.
Growth Drivers: Fuel Efficiency Demand and Driver Shortage Mitigation
Fuel saving and efficiency efforts on behalf of logistics providers are a key factor driving the Truck Platooning Market since the coordinated breaking and accelerating of the vehicles involved in a convoy cuts down aerodynamic drag and saves on fuel compared to independent operations. This is driven by ongoing shortages of drivers in the trucking sector, which makes technology-based solutions for increasing driver efficiency ever more appealing to fleet managers.
Tighter standards for greenhouse gas emissions along with well-financed pilot projects in the corridors between states add a key impetus to the growth of the Truck Platooning Market since platooning is increasingly recognized as one of the decarbonization tools that can be used to transport cargo. Improving standards of communication between trucks (with latency less than 50 milliseconds) add to market growth factors.
Restraints: Industry Shift Toward Full Autonomy and Regulatory Complexity
The broader autonomous trucking industry's increasing focus on standalone Level 4 autonomous operation, rather than multi-truck platooning specifically, represents a significant restraint on the Truck Platooning Market, as several prominent technology developers have redirected investment toward single-truck driverless operations on interstate corridors. This dynamic has introduced uncertainty regarding platooning's long-term role within the broader autonomous freight technology landscape.
Regulatory fragmentation across different states and countries continues to complicate cross-border and interstate platooning deployment, as commercial platooning authorization and following-distance requirements vary meaningfully across jurisdictions. Continued high technology development and validation costs add further restraint on market growth, particularly for smaller fleet operators evaluating platooning technology adoption.
Opportunities: Corridor Program Expansion and Emergency Services Applications
Further development of the government-sponsored corridor pilots provides a considerable growth potential for the Truck Platooning Market, with continued demonstration proving the practicality of platooning technology. Providers of the technology that are able to demonstrate validated and safety certified solutions have good potential to win market shares as more states and nations authorize commercial application.
Increased interest in the special emergency logistics applications and military applications of platooning technology opens a new opportunity for platooning technology providers to expand their scope of operations outside of traditional freight transportation. As government institutions continue researching applications of coordinated vehicle movements in disaster relief logistics and other similar fields, providers of the developed platooning technology will be able to capture the majority of the market.
Recent Developments
- 2026: RoboTruck, together with Toyota Tsusho, Hino Motors, Advanced Mobility, and seven logistics companies, was selected for Japan’s Ministry of Land, Infrastructure, Transport and Tourism (MLIT) autonomous-truck implementation support program, advancing automated highway freight operations.
- 2026: TRATON Group and PlusAI expanded their partnership to accelerate commercial deployment of autonomous trucks, with TRATON committing up to USD 25 million in dedicated R&D funding. The collaboration builds on trials involving Scania, MAN, and International trucks.
Truck Platooning Companies are:
- Daimler Truck AG
- AB Volvo
- Volkswagen Group (Traton SE)
- Peloton Technology, Inc.
- Intel Corporation
- Iveco Group N.V.
- ZF Friedrichshafen AG
- Aptiv PLC
- Continental AG
- DAF Trucks N.V.
- Hino Motors, Ltd.
- Robert Bosch GmbH
- Scania AB
- NXP Semiconductors N.V.
- WABCO Holdings Inc.
- Kratos Defense & Security Solutions, Inc.
- Locomation, Inc.
- Plus (PlusAI, Inc.)
- Aurora Innovation, Inc.
- Kodiak Robotics, Inc.
Truck Platooning Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 1.23 Billion |
| Market Size by 2035 | USD 5.43 Billion |
| CAGR | CAGR of 16.00% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Platooning Type (Driver-Assistive Truck Platooning and Autonomous Truck Platooning) • By Truck Class (Class-8, Class 6-7, Others) • By Application (Long-Haul/Line-Haul Freight, Regional Freight & Distribution, Port & Terminal Operations, Emergency & Public Services, Others) • By Component (Hardware, Software, Services) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Daimler Truck AG; AB Volvo; Volkswagen Group (Traton SE); Peloton Technology, Inc.; Intel Corporation; Iveco Group N.V.; ZF Friedrichshafen AG; Aptiv PLC; Continental AG; DAF Trucks N.V.; Hino Motors, Ltd.; Robert Bosch GmbH; Scania AB; NXP Semiconductors N.V.; WABCO Holdings Inc.; Kratos Defense & Security Solutions, Inc.; Locomation, Inc.; Plus (PlusAI, Inc.); Aurora Innovation, Inc.; Kodiak Robotics, Inc. |
Frequently Asked Questions
Leading companies in the Truck Platooning Market include Daimler Truck, AB Volvo, ZF Friedrichshafen, Robert Bosch, and Kratos Defense & Security Solutions, among others.
Key opportunities include continued expansion of government-funded interstate corridor pilot programs, and rising interest in specialized emergency services and defense logistics applications.
Logistics operators' pursuit of fuel savings and operational efficiency, combined with persistent driver shortages across the trucking industry, is the major factor driving market growth.
The Class-8 segment dominated the Truck Platooning Market with approximately 74.50% share in 2025.
North America dominated the Truck Platooning Market in 2025 with approximately 40.60% share, reflecting the region's supportive regulation and successful interstate pilot programs, led by the United States.
