
Semiconductor Chip Market Report Scope & Overview:
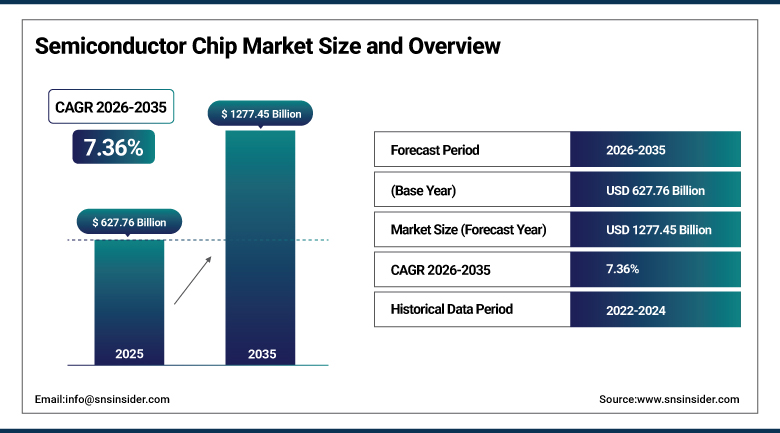
The Semiconductor Chip Market was valued at USD 627.76 Billion in 2025 and is expected to reach USD 1277.45 Billion by 2035, growing at a CAGR of 7.36% from 2026-2035.
Semiconductor chips modulate electric current across the memory, logic, analog, and sensor devices that sit inside essentially every piece of modern electronics, from smartphones and laptops to vehicles and factory equipment. Demand keeps climbing on the back of several genuinely independent growth engines running at once, cloud data centers scaling to support AI workloads, automakers packing far more electronics into every new vehicle, and consumer devices adding compute and connectivity that older models never needed. Manufacturers are responding with heavy capital investment in new fabrication capacity, since even a modest global supply shortfall ripples quickly into shipment delays across dozens of downstream industries that depend on a steady chip supply.
The Semiconductor Industry Association reported global chip sales of USD 75.3 billion for November 2025 alone, a 29.8% year-over-year increase, underscoring just how sharply AI-driven data center demand has accelerated industry-wide revenue over the past year. That same month, Intel unveiled its Panther Lake chips built on the Intel 18A process, the company's first 2-nanometer-class node produced domestically at its Fab 52 facility in Arizona, a milestone that matters less for its raw performance numbers than for what it signals about the U.S. finally bringing leading-edge manufacturing back onto its own soil after years of that capability sitting almost entirely overseas.
To Get more information Semiconductor Chip Market - Request Free Sample Report
Semiconductor Chip Market Trends
-
AI accelerator and data center chip demand continues outpacing broader semiconductor market growth, pulling capital investment toward advanced logic and high-bandwidth memory production.
-
Domestic chip manufacturing investment is accelerating across the U.S., Europe, and India as governments push to reduce reliance on concentrated East Asian production capacity.
-
Automotive semiconductor content per vehicle continues rising sharply as electrification and advanced driver-assistance systems expand across both premium and mainstream vehicle segments.
-
Advanced node development below 3-nanometer continues concentrating among a shrinking number of foundries capable of funding the enormous capital cost involved.
-
Legacy and mature-node chip demand remains resilient even as leading-edge nodes capture headlines, since industrial and automotive customers frequently prioritize supply reliability over raw performance.
U.S. Semiconductor Chip Market Outlook
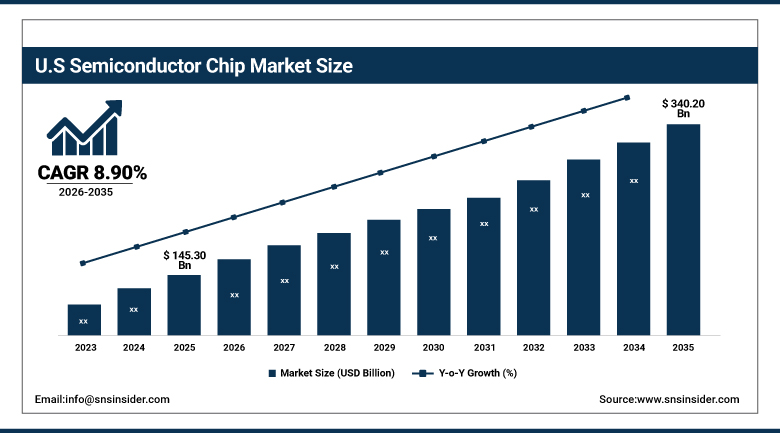
The U.S. Semiconductor Chip Market was valued at approximately USD 145.30 Billion in 2025 and is expected to reach approximately USD 340.20 Billion by 2035, growing at a CAGR of approximately 8.90%.
The U.S. market has entered a genuine manufacturing reshoring phase, with more than USD 600 billion in private-sector investment announced toward domestic chip production as part of a broader effort to roughly triple national manufacturing capacity by 2032. Strong domestic demand from hyperscale data center operators building out AI infrastructure continues to anchor near-term revenue, while defense and automotive customers add a steady secondary demand base less exposed to consumer electronics cyclicality.
Intel unveiled its Panther Lake chips in October 2025, the first products built on the Intel 18A process and manufactured at the company's Fab 52 facility in Arizona, marking the first time in years that a U.S. fab has produced chips at a genuinely leading-edge node rather than trailing several generations behind Taiwanese and South Korean competitors. The milestone carries real strategic weight beyond Intel's own product roadmap, since it demonstrates that the CHIPS Act-era investment wave is beginning to translate into actual leading-edge output rather than remaining confined to construction and equipment installation.
Semiconductor Chip Market Segment Analysis
-
By Component Type, the Memory Devices segment dominated the Semiconductor Chip Market with approximately 35.20% share in 2025, while the Analog ICs segment is the fastest growing with a CAGR of approximately 9.80%.
-
By Application, the Networking & Communications segment dominated the Semiconductor Chip Market with approximately 29.75% share in 2025, while the Automotive segment is the fastest growing with a CAGR of approximately 10.40%.
-
By End-Use Industry, the IT & Telecommunications segment dominated the Semiconductor Chip Market with approximately 31.60% share in 2025, while the Automotive segment is the fastest growing with a CAGR of approximately 10.60%.
By Component Type, memory devices dominates, analog ICs grows fastest
Memory devices dominated the component segment in 2025 with approximately 35.20% share, driven by high demand from smartphones, laptops, and cloud services, all of which require DRAM and NAND flash for storage capable of handling immense data volumes efficiently. Big technology companies continue assembling ever-larger data centers built around memory-dense server configurations, sustaining this segment's leading position well ahead of any other component category. High-bandwidth memory dedicated to AI accelerator cards has also emerged as an increasingly influential sub-category, with demand from hyperscale data center operators now rivaling traditional consumer memory demand in strategic importance to major suppliers.
Analog ICs are the fastest-growing component segment, expanding at a CAGR of approximately 9.80% over the forecast period, propelled by rapid demand for smart devices including smartphones, watches, and smart televisions that all require analog circuitry to bridge real-world signals with digital processing. Growing electrification of vehicles and industrial equipment continues to add further demand for the power-management analog chips this category encompasses. Automakers and industrial equipment manufacturers are also driving incremental analog demand as electrification programs expand the number of voltage regulation and signal-conditioning chips required in every new product design.
By Application, networking & communications dominates, automotive grows fastest
Networking and communications dominated the application segment in 2025, holding approximately 29.75% share and remaining the dominant category throughout the forecast period, attributable to increased adoption of smartphones and other smart devices worldwide. With roughly 4 billion people now accessing the internet, most through smartphones, this connectivity-driven demand base continues expanding as global internet penetration keeps climbing toward saturation in developed markets and accelerating in emerging ones. Enterprise networking equipment upgrades tied to expanding cloud infrastructure continue reinforcing this segment's lead, as data centers require increasingly sophisticated switching and routing silicon to keep pace with rising traffic volumes.
Automotive is the fastest-growing application segment, expanding at a CAGR of approximately 10.40% over the forecast period, driven by rising vehicle adoption across both developed and developing nations alongside surging electric vehicle popularity. Advanced driver-assistance systems and vehicle electrification together are pushing semiconductor content per vehicle sharply higher, a structural shift that shows no sign of slowing as automakers race to add more compute and sensing capability to every new model. Semiconductor content per vehicle is expected to keep climbing well beyond current levels as autonomous driving features move from pilot programs into broader commercial deployment across multiple vehicle segments.
By End-Use Industry, IT & telecommunications dominates, automotive grows fastest
IT and telecommunications dominated the end-use segment in 2025 with approximately 31.60% share, reflecting the sheer breadth of chip demand generated by data centers, networking infrastructure, and telecom equipment that underpin the broader digital economy. Continued 5G network buildout and expanding cloud computing capacity keep this end-use category firmly in the lead across nearly every major regional market. Enterprise IT infrastructure upgrades tied to hybrid cloud adoption further reinforce this segment's position, as businesses continue investing in networking and server hardware to support distributed computing environments.
Automotive is the fastest-growing end-use industry, expanding at a CAGR of approximately 10.60% over the forecast period, as electric vehicle adoption accelerates and advanced driver-assistance features move from premium models into mainstream vehicle trims. Growing consumer demand for connected, semi-autonomous vehicle features continues to push automakers toward richer semiconductor content in every new vehicle platform they design. Government and industry incentive programs targeting domestic vehicle electrification are further accelerating this shift, giving automotive semiconductor suppliers unusually strong demand visibility relative to more cyclical consumer electronics end-markets.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
65.70% |
|
North America |
United States |
78.90% |
|
Europe |
Germany |
24.60% |
|
Latin America |
Brazil |
28.40% |
|
Middle East & Africa |
Israel |
31.20% |
North America Semiconductor Chip Market Insights
North America is the fastest-growing region in the Semiconductor Chip Market, expanding at a CAGR of approximately 9.20% over the forecast period, driven by more than USD 600 billion in private-sector investment aimed at tripling domestic manufacturing capacity and reducing reliance on concentrated East Asian production. The CHIPS and Science Act continues to underpin much of this investment, providing both direct subsidies and tax incentives that have meaningfully lowered the effective cost of building new domestic fabrication capacity. Multiple new fabrication facilities under construction across Arizona, Texas, and Ohio are expected to substantially increase domestic leading-edge capacity over the coming several years.
The United States anchors this growth through strong hyperscale data center demand and renewed leading-edge fabrication investment, exemplified by Intel's Fab 52 facility in Arizona. Canada continues contributing specialized design and research activity supporting the broader North American semiconductor ecosystem. Growing defense-sector demand for domestically manufactured chips, driven by national security concerns around foreign-sourced components, adds a further steady demand layer supporting the region's above-average growth trajectory. Growing collaboration between chipmakers and U.S. research universities continues to strengthen the domestic talent pipeline needed to staff an expanding base of advanced fabrication facilities.
Europe Semiconductor Chip Market Insights
Europe represents a mature semiconductor market anchored by strong automotive and industrial chip demand, with Germany leading regional consumption through its large automotive manufacturing base increasingly reliant on power and analog semiconductors for vehicle electrification programs. Growing European semiconductor sovereignty initiatives, backed by the EU Chips Act, continue to direct public funding toward expanding regional fabrication capacity beyond its current, comparatively modest scale. Continued investment from equipment suppliers based in the Netherlands further reinforces Europe's strategic importance to the global semiconductor manufacturing equipment supply chain.
The Netherlands still holds its ground in terms of the region’s role as a supplier of advanced lithography technology equipment, whereas France and Italy still contribute valuable automotive and industrial semiconductor demand to the region. The European Union funding still plays an important role in the development of regional fabrication capability and import reduction. Automotive semiconductor demand in particular will still underpin European demand due to the fact that the region has a high presence of luxury car manufacturers who implement electric mobility initiatives for their fleets.
Asia Pacific Semiconductor Chip Market Insights
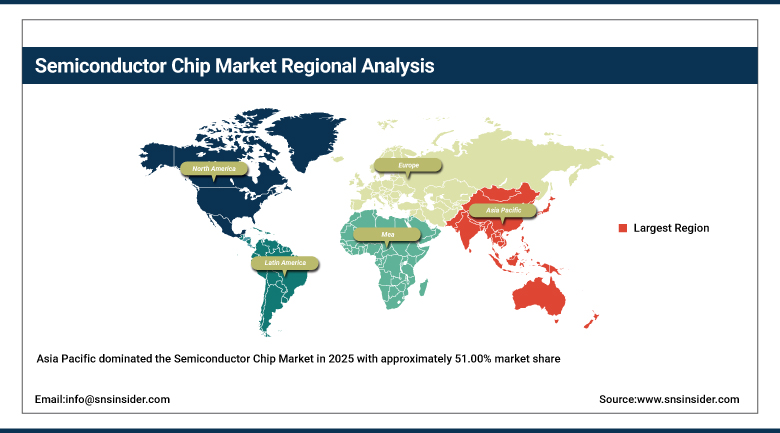
Asia Pacific dominated the Semiconductor Chip Market in 2025 with approximately 51.00% market share, anchored by China's massive domestic chip demand and manufacturing base, alongside Taiwan's and South Korea's leading-edge foundry and memory production capacity that together supply a large share of the world's advanced chips. South Korea's dominant position in memory chip production, led by Samsung and SK Hynix, further reinforces the region's overall leadership across both logic and memory device categories. Continued expansion of advanced packaging and testing capacity across the region further reinforces its central role in the global semiconductor supply chain beyond pure wafer fabrication.
China alone accounted for more than 65.7% of the Asia Pacific market, supported by aggressive government investment in domestic semiconductor self-sufficiency. Japan and India continue contributing meaningful additional regional capacity, with India in particular attracting new fabrication and R&D investment aimed at diversifying the region's manufacturing footprint. Ongoing government subsidies across the region continue to reinforce this manufacturing concentration, even as individual countries increasingly compete with one another to attract the next wave of fabrication investment. Regional trade agreements among Asia Pacific economies continue to facilitate the cross-border movement of components and equipment essential to maintaining efficient, tightly integrated supply chains.
Get Customized Report as per Your Business Requirement - Enquiry Now
MEA & Latin America Semiconductor Chip Market Insights
The Middle East and Africa represent a smaller but strategically significant market, with Israel driving regional demand through its concentrated semiconductor design and R&D sector, home to major chipmaker development centers serving global product lines. Continued investment from global chipmakers in Israeli R&D centers reinforces the country's position as a design and innovation hub disproportionate to its small domestic market size. Regional government incentive programs aimed at attracting additional design and testing investment continue to expand the Middle East's role beyond its historical concentration in Israel alone.
Latin America is a growing market led by Brazil, where expanding electronics assembly and automotive manufacturing continue to drive incremental chip demand. Mexico contributes meaningful additional volume through its role as an electronics and automotive component assembly hub serving North American supply chains. Growing regional electronics assembly investment across both Latin America and parts of Africa continues to gradually diversify global semiconductor demand beyond its historical concentration in Asia, North America, and Europe. Growing nearshoring interest among global electronics brands continues to position both Latin America and select African markets as emerging secondary assembly and testing hubs.
Market Dynamics
Growth Drivers: AI infrastructure buildout and vehicle electrification fueling chip demand
Explosive growth in AI data center infrastructure remains the single strongest driver of current semiconductor demand, with manufacturing capacity expanding by roughly 7% globally in 2025 and industry-wide capital expenditure reaching approximately USD 185 billion as companies race to keep pace with high-performance computing and memory requirements. Cloud service providers are committing multi-year capital spending plans specifically to secure long-term chip supply agreements, giving semiconductor manufacturers unusually strong demand visibility for the next several years. This sustained capital commitment gives equipment suppliers and material providers similarly strong forward visibility, encouraging further upstream investment throughout the broader semiconductor supply chain.
Automotive electrification and advanced driver-assistance system adoption continue adding substantial semiconductor content per vehicle, a structural shift that keeps expanding regardless of overall vehicle sales cycles since even a single new model generation can meaningfully increase average chip content across an automaker's entire lineup.
Restraints: Geopolitical tension and raw material supply risk limiting stability
Geopolitical tensions surrounding concentrated East Asian manufacturing capacity, particularly Taiwan's outsized role in advanced node production, continue to create genuine supply chain risk that customers and governments alike are working to hedge against through geographic diversification, even though that diversification remains a multi-year, capital-intensive undertaking. Export control measures targeting advanced chip technology have further complicated global supply chains, forcing manufacturers to navigate an increasingly fragmented set of national trade restrictions when planning cross-border production and sales. Smaller chip designers without the scale to navigate multiple overlapping regulatory regimes are particularly exposed to this complexity, occasionally losing access to markets that larger, better-resourced competitors can still serve.
Raw material shortages and supply chain fragility, cited by more than half of industry respondents as a significant growth challenge, continue to complicate production planning, particularly for specialty gases and rare materials concentrated among a small number of global suppliers. Water and energy availability for large fabrication facilities has also emerged as a growing constraint in several regions, adding site-selection complexity to already lengthy and capital-intensive facility planning processes.
Opportunities: Domestic manufacturing incentives and edge AI adoption widening addressable demand
Government incentives promoting domestic production of computer chips in America, Europe, and India provide a large opportunity for existing chip makers and new entrants to exploit subsidized capacity additions, thereby lowering the capital risk associated with building a greenfield semiconductor manufacturing plant on a large scale. Those businesses that make an early push in setting up manufacturing in these government-incentivized areas will enjoy many years of subsidized government support until they face competition from new entrants.
Increasing adoption of AI chips on edge, as more AI inference moves from the cloud data center to local devices, provides an opportunity for chip manufacturers to cater to a new type of demand for AI accelerator chips that are small and energy-efficient in nature for consumer and industrial applications. The chip manufacturers who strike the right balance between performance and efficiency in their designs can corner most of the market share as more use cases emerge on the edges.
Recent Developments:
-
October 2025- Intel unveiled its Panther Lake chips, the first products built on the Intel 18A process, a 2-nanometer-class node produced domestically at its Fab 52 facility in Arizona.
-
October 2025- UK-based Graphcore announced a USD 1.3 billion investment plan for India over the next decade to expand R&D capacity and support AI semiconductor development.
-
2025- Qualcomm reported approximately USD 43-45 billion in annual revenue, reflecting continued strength in wireless connectivity, advanced processors, and automotive chipset platforms.
-
December 2022- Qualcomm Technologies introduced its WiFi-7 capable chipsets as part of a new immersive home platform supporting high-speed wireless connections across consumer devices.
Semiconductor Chip Market Key Players
-
Taiwan Semiconductor Manufacturing Co., Ltd. (TSMC)
-
Samsung Electronics Co., Ltd.
-
Intel Corporation
-
Qualcomm Incorporated
-
SK Hynix Inc.
-
Micron Technology, Inc.
-
Broadcom Inc.
-
Texas Instruments Incorporated
-
NVIDIA Corporation
-
STMicroelectronics N.V.
-
Infineon Technologies AG
-
NXP Semiconductors N.V.
-
Applied Materials, Inc.
-
ASML Holding N.V.
-
GlobalFoundries Inc.
-
MediaTek Inc.
-
Renesas Electronics Corporation
-
ON Semiconductor Corporation
-
Analog Devices, Inc.
-
United Microelectronics Corporation (UMC)
Semiconductor Chip Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 627.76 Billion |
| Market Size by 2035 | USD 1277.45 Billion |
| CAGR | CAGR of 14.77% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Component Type (Memory Devices, Logic Devices, Analog ICs, Microprocessors (MPU), Discrete Semiconductors, Sensors, Others) • By Application (Networking & Communications, Automotive, Computing, Consumer Electronics, Industrial, Others) • By End-Use Industry (IT & Telecommunications, Automotive, Consumer Electronics, Industrial, Healthcare) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Taiwan Semiconductor Manufacturing Co., Ltd. (TSMC), Samsung Electronics Co., Ltd., Intel Corporation, Qualcomm Incorporated, SK Hynix Inc., Micron Technology, Inc., Broadcom Inc., Texas Instruments Incorporated, NVIDIA Corporation, STMicroelectronics N.V., Infineon Technologies AG, NXP Semiconductors N.V., Applied Materials, Inc., ASML Holding N.V., GlobalFoundries Inc., MediaTek Inc., Renesas Electronics Corporation, ON Semiconductor Corporation, Analog Devices, Inc., United Microelectronics Corporation (UMC) |
Frequently Asked Questions
Key players in the Semiconductor Chip Market include Taiwan Semiconductor Manufacturing Co., Ltd. (TSMC), Samsung Electronics Co., Ltd., Intel Corporation, Qualcomm Incorporated, and SK Hynix Inc., among others.
Key opportunities include government incentive programs supporting domestic chip manufacturing across the U.S., Europe, and India, and growing edge AI adoption creating new demand for compact, power-efficient AI accelerator chips.
The market is driven by explosive growth in AI data center infrastructure and continued automotive electrification and advanced driver-assistance system adoption expanding semiconductor content per vehicle.
The Memory Devices segment dominated the Semiconductor Chip Market, accounting for approximately 35.20% market share.
Asia Pacific dominated the Semiconductor Chip Market in 2025 with approximately 51.00% share, anchored by China, Taiwan, and South Korea's manufacturing capacity.
