
Ultrapure Water Market Report Scope & Overview:
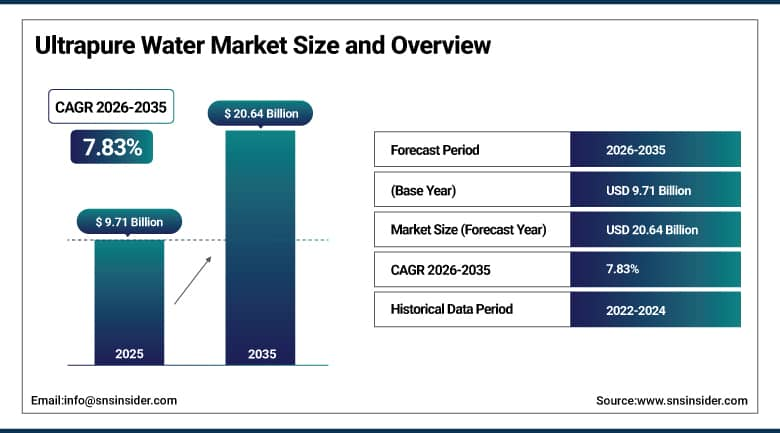
The Ultrapure Water Market size was valued at USD 9.71 Billion in 2025 and is expected to reach USD 10.47 Billion in 2026, rising to USD 20.64 Billion by 2035. The market is forecast to expand at a CAGR of 7.83% during 2026–2035. Ultrapure water is treated to remove ions, particles, organic compounds, bacteria and dissolved gases to extremely low levels, and it is produced through combinations of reverse osmosis, ion exchange, electrodeionization, ultrafiltration and degassing. Semiconductor fabs, pharmaceutical plants, power stations and laboratories use it because trace impurities can damage chips, contaminate medicines or corrode boilers.
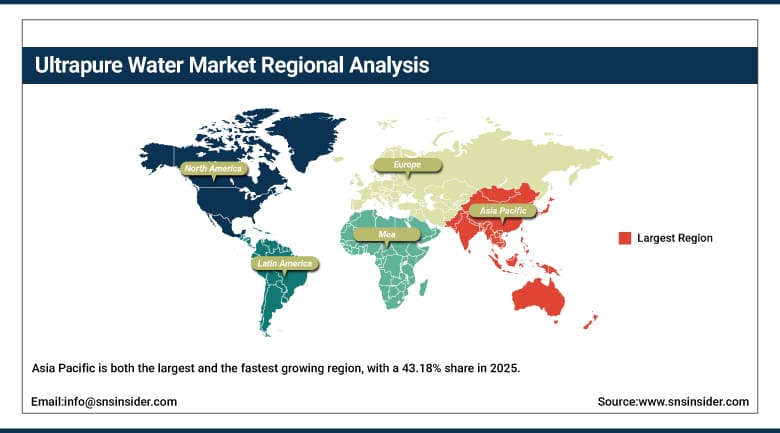
Asia Pacific accounted for the largest share of the market, at 43.18% in 2025, because Taiwan, South Korea, China, Japan and Singapore host most of the world chip fabrication capacity. North America follows, supported by new fabs in Arizona, Texas and New York and a large pharmaceutical base. Asia Pacific is also the fastest growing region, as India and Southeast Asia add semiconductor and electronics plants and as existing fabs move to more advanced nodes that require tighter water purity. Europe contributes through pharmaceutical and power demand, while Middle East & Africa and Latin America add projects tied to chips, drugs and energy.
To Get More Information On Ultrapure Water Market - Request Free Sample Report
Key Report Takeaways
-
By technology, reverse osmosis held 31.64% in 2025, while electrodeionization is the fastest growing.
-
By end use, semiconductor held 41.37% in 2025 and is also the fastest growing.
-
By application, cleaning and washing held 46.83% in 2025, while process feed is the fastest growing.
-
By product type, consumables held 48.36% in 2025, while services are the fastest growing.
-
By region, Asia Pacific held 43.18% in 2025 and is also the fastest growing.
Market Trends and Insights
Fabs are tightening water specifications as chips move to smaller nodes, and suppliers are responding with improved membranes, resins, point-of-use polishing and online monitoring of trace contaminants. Operators also add recycling loops that recover rinse water, which lowers intake and discharge.
Suppliers are moving from equipment sales toward long-term service, consumables and performance contracts, and some offer build-own-operate plants. Digital twins and remote monitoring help plants hold purity targets while cutting energy and chemical use, and data centers are emerging as an additional source of demand for high-purity water.
Drivers Impact Analysis
|
Driver |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Semiconductor fab expansion and advanced node manufacturing |
+3.12% |
Asia Pacific and North America |
Medium term (2 to 4 years) |
|
Pharmaceutical and biotech quality requirements |
+2.46% |
Global |
Medium term (2 to 4 years) |
|
Power generation and energy transition applications |
+1.74% |
Global |
Long term (4 years or more) |
|
Water reuse and recycling requirements |
+1.18% |
North America and Asia Pacific |
Medium term (2 to 4 years) |
|
Advances in membrane, electrodeionization and monitoring technology |
+0.82% |
Global |
Short term (2 years or less) |
Semiconductor Fab Expansion and Advanced Node Manufacturing
A modern fab can consume tens of thousands of cubic meters of water per day, and a large share of it must be purified to near-theoretical levels. New plants in Taiwan, South Korea, Japan, the United States, India and Europe are being built with large ultrapure water systems, and each shrink in node size tightens limits on particles, metals and organic carbon. Memory, logic and advanced packaging lines all require reliable supply. Suppliers therefore win long contracts. Fabs plan expansions in phases.
Pharmaceutical and Biotech Quality Requirements
Drug makers use purified water for formulation, cleaning, injection preparation and cell culture, and pharmacopoeia rules require strict control of conductivity, organic carbon and microbes. Expansion of biologics, vaccines and cell therapy plants adds new water loops, and validation, monitoring and sanitization needs create recurring purchases of membranes, resins and services. Single-use and closed-system manufacturing are growing, but they still depend on purified water for buffers and cleaning, and regulators inspect water systems closely during audits, which keeps spending on compliance and upgrades steady.
Power Generation and Energy Transition Applications
High-pressure boilers and steam turbines need demineralized water of very high purity to prevent scaling and corrosion. Combined cycle plants, nuclear units and concentrated solar stations continue to order such systems. Hydrogen electrolyzers also need ultrapure feed water, so energy transition projects create a newer source of demand. Nuclear restarts and new gas turbines in Asia and North America are adding further orders, and operators replace aging demineralizer trains with membrane-based systems that use fewer chemicals and meet stricter discharge limits.
Water Reuse and Recycling Requirements
Water scarcity and discharge rules push fabs and factories to reuse rinse water and treat wastewater on site. Reclaim systems use membranes, ion exchange and polishing steps to return water to the process, which increases the size of the treatment train and the volume of consumables. Municipal reuse programs near industrial clusters also supply feed water. Operators in Arizona, Taiwan and Singapore have set ambitious recovery targets, and suppliers that can combine ultrapure production with wastewater reclamation win larger projects and longer service relationships with the same customer.
Advances in Membrane, Electrodeionization and Monitoring Technology
Better membranes lower energy use and fouling, while electrodeionization replaces chemical regeneration of resins. Sensors that detect trace ions, silica and organic carbon in real time allow operators to protect yield and cut waste, and artificial intelligence tools predict membrane fouling and schedule cleaning. Vendors also introduce low-fouling membranes, modular skids and compact polishing units that cut installation time, so even smaller laboratories and hospitals can adopt higher-grade systems at a reasonable cost. Data from sensors also supports warranty claims and performance contracts. Compact units suit pilot lines.
Restraints Impact Analysis
|
Restraint |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
High capital and operating cost |
-0.72% |
Global |
Medium term (2 to 4 years) |
|
Water scarcity and wastewater discharge rules |
-0.48% |
Asia Pacific and North America |
Medium term (2 to 4 years) |
|
Complex maintenance and skilled labor shortage |
-0.19% |
Global |
Long term (4 years or more) |
|
Cyclical semiconductor capital spending |
-0.10% |
Asia Pacific and North America |
Short term (2 years or less) |
High Capital and Operating Cost
Ultrapure water systems require multiple treatment stages, high-grade piping, instrumentation and redundant equipment, so investment per plant is large. Running costs include energy, resins, membranes, chemicals and replacement of consumables. Smaller users in pharmaceuticals and laboratories may choose lower-grade systems or rent equipment, which limits sales of full-scale installations. Customers often delay upgrades until failures occur, and price competition among suppliers of standard equipment limits margins, especially in emerging markets where buyers favor local manufacturers and lower upfront prices. Financing is selective.
Water Scarcity and Wastewater Discharge Rules
Fabs are located in regions where water is limited, and permits can restrict intake or demand high recycling rates. Rejected water and spent regenerant must be treated before discharge, which adds cost, and droughts can delay approvals for new plants. These constraints can slow construction schedules and raise project cost. Local communities also question the water use of large fabs, and operators must invest in desalination, reclaimed municipal water and stormwater capture, which raises project risk and cost for developers.
Complex Maintenance and Skilled Labor Shortage
Operating an ultrapure water plant requires technicians who can manage membranes, ion exchange, degassing and analytical equipment, and such skills are scarce. Poor maintenance can lead to contamination events that halt production, so customers pay for service contracts but still struggle to find staff, which can delay commissioning and expansion. Suppliers respond with remote monitoring, training programs and managed service offers, but the shortage of experienced technicians is expected to persist as more plants open in similar locations at the same time.
Cyclical Semiconductor Capital Spending
Chipmakers raise and cut investment with demand for electronics, and downturns in memory or consumer devices delay fab construction. Because water system orders come early in a project, shifts in capital budgets quickly affect suppliers. Policy changes, export controls and subsidies also change the timing of new plants. Suppliers diversify toward pharmaceuticals, power and consumables to offset swings, but the largest single orders still come from new fab projects, which keeps revenue uneven from year to year. Tariffs also affect equipment costs.
Ultrapure Water Market Segment Analysis
By Technology, Reverse Osmosis Dominates Ultrapure Water Market; Electrodeionization to Register Fastest Growth.
Reverse osmosis accounts for 31.64% of the market in 2025 because it removes most dissolved salts, organics and microbes from feed water at a reasonable energy cost. It is the first major treatment stage in nearly every ultrapure water plant, and membranes need regular replacement. Mature design practices make it the default choice for semiconductor, pharmaceutical and power users. Replacement cycles keep revenue steady across the year, and suppliers with global manufacturing can serve customers in several regions.
Electrodeionization is projected to grow at a CAGR of 9.74% during 2026–2035. It combines ion exchange resins with electric current to remove ions continuously, which eliminates chemical regeneration and reduces waste. Plants value its steady quality and smaller footprint, and demand is rising as fabs and drug makers seek lower chemical handling. Suppliers are also developing compact skids and containerized plants that cut installation time. Chipmakers that run many fabs prefer common designs, which favors technology leaders. Orders rise too.
By End Use, Semiconductor Dominates Ultrapure Water Market and Is Also Set to Register Fastest Growth.
Semiconductor manufacturing accounts for 41.37% of the market in 2025 and is expected to expand at a CAGR of 9.68% during 2026–2035. Wafer rinsing and cleaning steps use enormous volumes of water with parts-per-trillion impurity limits, and every new fab or node transition raises demand. Government subsidies in the United States, Europe, Japan, India and Korea support new plants. Memory, logic and advanced packaging lines all require large volumes of high-grade water, and new fabs are sized with extra capacity.
Pharmaceutical, power generation and laboratory users add steady volumes, but the scale of fab projects and the tightening of purity specifications keep semiconductor ahead on both size and growth. Ultrapure water systems are among the first utilities ordered for a new plant, and operators now expect continuous monitoring, recycling loops and strict guarantees on resistivity, particles and total organic carbon, which raise the value of every installation. Suppliers also benefit from long-term service relationships with fabs that run all day.
By Application, Cleaning and Washing Dominates Ultrapure Water Market; Process Feed to Register Fastest Growth.
Cleaning and washing holds a 46.83% share in 2025 because rinsing wafers, glassware, vials and equipment surfaces consumes the largest volume of ultrapure water. Any residue left after cleaning can ruin a chip batch or contaminate a drug lot. Fabs use water after almost every process step, which makes this the main source of consumption. Cleaning also accounts for the largest use in laboratories and hospitals, where instruments and glassware need contamination-free rinses. Cycles repeat for every batch.
Process feed is expected to expand at a CAGR of 8.62% from 2026 to 2035. Ultrapure water is used as a raw material and carrier in chemical mixing, photolithography baths, boiler feed, steam generation and electrolysis. New pharmaceutical lines and hydrogen projects raise needs, and operators want stable quality at the point of use. Combined with rising volumes of ultrapure feed water for electronics chemicals and pharmaceutical formulation, process uses are growing quickly. Hydrogen projects add further volumes.
By Product Type, Consumables Dominate Ultrapure Water Market; Services to Register Fastest Growth.
Consumables account for 48.36% of the market in 2025 because membranes, resins, filter cartridges, lamps and cleaning chemicals must be replaced regularly in every plant. Revenue repeats for as long as the plant runs, and replacement cycles depend on feed quality and purity targets. Operators also prefer to stay with parts matched to their system. Fabs also buy larger quantities as capacity expands. Suppliers compete on membrane life and resin capacity. Distributors stock common items for quick restoration.
Services are projected to grow at a CAGR of 9.21% during 2026–2035. Customers outsource operation, monitoring, membrane cleaning, resin regeneration and performance guarantees, and build-own-operate contracts are spreading. Shortages of technicians and the cost of downtime make long-term service agreements attractive. Remote diagnostics lower the risk of unplanned outages, and suppliers use performance data to schedule maintenance before quality drifts. Smaller plants prefer outsourced care. Operators also value guaranteed purity, spare parts availability and training, bundled into multi-year agreements.
Geography Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
84.37% |
|
Europe |
Germany |
22.58% |
|
Asia Pacific |
China |
38.46% |
|
Middle East & Africa |
Israel |
33.18% |
|
Latin America |
Brazil |
47.28% |
North America Ultrapure Water Market
North America held 27.46% of the market in 2025, led by the United States. The U.S. market was valued at USD 2.25 Billion in 2025 and is expected to register a CAGR of 6.94% during 2026–2035. New fabs in Arizona, Texas, New York and Ohio, supported by federal incentives, drive demand, along with a large pharmaceutical and biotechnology sector. Federal incentives and state programs have accelerated site selection, and chip customers prefer suppliers that can provide local engineering, installation, resin regeneration and service teams with fast response in the region.
Canada adds demand through pharmaceutical and power projects, and Mexico is counted in Latin America although electronics assembly links it to North American supply chains. Water scarcity in the Southwest pushes operators toward high recycling rates, so reclaim systems are standard features. Pharmaceutical clusters in Massachusetts, North Carolina, New Jersey and California add steady demand for purified and injection-grade water, and biologics plants are expanding with new validated water loops and monitoring systems across the country. Smaller laboratories and hospitals buy compact systems from regional distributors.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Ultrapure Water Market
Europe accounted for 17.84% of the market in 2025, with Germany as the leading country. The region has strong pharmaceutical, power and specialty electronics sectors and is adding semiconductor capacity under public support programs. Strict environmental rules push suppliers to deliver efficient and low-waste systems. Public investment, strong industrial research and a skilled workforce support project delivery, while customers expect low energy use, high recovery and strict control of chemicals and discharge, which raises demand for efficient systems. Energy cost is a key factor.
Ireland, France, Switzerland, the Netherlands and Italy are important for drug production, and new chip projects in Germany and elsewhere add demand. European suppliers of membranes, resins and monitoring equipment export to other regions. Germany, Dresden in particular, is becoming a center for chip manufacturing, and the Netherlands and Belgium host specialized equipment suppliers. Pharmaceutical expansion in Ireland and Switzerland also supports regional growth. Companies in Scotland, Spain and Poland also add investment in electronics and pharmaceuticals, and local universities train engineers. Regional policy supports sites that need water reliably.
Asia Pacific Ultrapure Water Market
Asia Pacific is both the largest and the fastest growing region, with a 43.18% share in 2025 and a projected CAGR of 9.21% over 2026–2035. China leads the region, with a large base of fabs, display plants and power stations, and with rising local capacity for advanced chips. Taiwan, South Korea and Japan host the most advanced fabs and the strictest water specifications. Many installations are tied to wafer plants that are among the largest private investments in the region, and the supply base of resins and membranes is deep.
India is building its first large fabs and packaging plants, and Singapore, Malaysia and Vietnam are expanding electronics and chip assembly. Local engineering firms and international suppliers compete for contracts, and water reuse targets in water-stressed sites add to equipment content. Water recycling targets are strict in Taiwan and Singapore, and operators are testing advanced reclamation systems that return rinse water to the ultrapure loop with minimal loss across several major sites. Competition is intense, and buyers expect fast delivery and local support.
Middle East & Africa Ultrapure Water Market
Middle East & Africa held 6.12% of the market in 2025. Israel leads regional demand through its chip and electronics industry, and Saudi Arabia and the United Arab Emirates add demand from power plants, petrochemical complexes and pharmaceutical projects. Israel hosts advanced fabs and design centers, and its semiconductor sector invests in water recycling because freshwater supply is limited. Gulf countries add power and industrial projects supported by desalination capacity and large national investment programs. Municipal reuse supplies feed water.
Desalination plants provide feed water in many Gulf countries, and operators add polishing steps for industrial users. South Africa and Egypt have smaller markets focused on power and drug production. Water scarcity and the cost of energy shape project choices. Egypt, Turkey and North African countries are building drug plants and power stations, and international suppliers are signing local partnerships. Training programs for technicians remain important across the region. Operators in the Gulf also invest in staff training, and consultants help owners write specifications for new industrial parks.
Latin America Ultrapure Water Market
Latin America accounted for 5.40% of the market in 2025, with Brazil as the leading country. Brazil has a sizable pharmaceutical, power and chemical base that uses ultrapure water in boilers and production. Mexico is the second major market, supported by electronics assembly, medical devices and growing interest in chip packaging. Peru and Chile add mining and power projects that use demineralized water, and regional suppliers provide resins, spare parts and maintenance for plants spread across long distances in the region.
Argentina, Chile and Colombia add demand from mining, power and drug production. Import costs and currency swings affect equipment prices, and local service providers play a key role in keeping plants running. Brazil is investing in biologics, vaccines and medical devices, which need validated water systems. Tight project budgets mean customers favor modular systems and local service providers that can deliver quickly. Argentina has a growing pharmaceutical sector, and Colombia and Chile are modernizing hospitals. Distributors supply cartridges and resins to smaller plants.
Competitive Landscape
The Ultrapure Water Market is moderately consolidated. A few global water technology groups and specialty membrane and resin suppliers hold large positions, while regional engineering firms and equipment makers serve local fabs, hospitals and power plants. Competition rests on purity performance, reliability, lifecycle cost, service coverage and long relationships with chipmakers.
Vendors pursue acquisitions, capacity additions for membranes and consumables, local engineering centers and service contracts.
Ultrapure Water Market Industry Leaders
1. Veolia: French environmental services group whose Water Technologies unit builds ultrapure water systems.
2. DuPont: U.S. materials company that supplies reverse osmosis and ultrafiltration membranes and resins.
3. Kurita Water Industries: Japanese water treatment company serving electronics customers.
4. Organo: Japanese water engineering company serving chipmakers.
5. Ecolab: U.S. water, hygiene and infection prevention company with an ultrapure water business.
Companies Covered in this Report
-
Veolia
-
DuPont
-
Kurita Water Industries
-
Organo
-
Ecolab
-
Xylem
-
Asahi Kasei
-
Nomura Micro Science
Recent Industry Developments
-
2025: DuPont agreed to acquire Sinochem (Ningbo) RO Memtech to expand FilmTec reverse osmosis manufacturing in China.
-
2025: Ecolab closed its acquisition of the electronics ultrapure water business of Ovivo.
-
2026: The Semiconductor Industry Association reported that global semiconductor sales rose 25.60% to USD 791.70 Billion in 2025.
-
2026: Kurita and Membrane Group established Kurita Membrane India as a joint venture for semiconductor water treatment.
-
2026: Veolia secured two contracts with a leading semiconductor manufacturer, including ultrapure water production for a new fabrication facility in Singapore.
-
2026: Xylem agreed to acquire Cornell Pump and Roper Pump for USD 1.46 Billion.
Scope and Research Methodology
This study estimates the Ultrapure Water Market for 2025 as the base year and forecasts it through 2035. The scope covers systems, consumables and services used to produce water with very low ionic, particle, organic and microbial content for semiconductor, pharmaceutical, power generation and laboratory use. Values are reported in USD at the point of sale by suppliers. General industrial and municipal water treatment, and bottled drinking water, are outside the scope. Segmentation covers technology, end use, application, product type and region, and both new installations and recurring consumables are included. All values are rounded to two decimals.
Secondary research included company annual reports, investor presentations and filings, industry association and standards data, regulator and government databases, product documentation, and peer-reviewed and industry publications. Primary research consisted of structured interviews and surveys with fab facility managers, pharmaceutical engineers, plant operators, equipment makers and distributors. These inputs were used to validate project values, consumable demand and the share of each technology. Interviews covered fab water managers, pharmaceutical validation engineers, power plant chemists and distributors, which allowed assumptions on consumable life, pricing and service demand to be tested against practice. Responses were cross-checked.
Market size was built from the bottom up using supplier revenue, project pipelines and installed base data, and was cross-checked from the top down against fab capacity, pharmaceutical output and power capacity. Triangulation across these views fixed the base year value. Forecasts consider capital spending, water regulation, node migration and technology adoption, and segment and regional shares were assigned from adoption patterns in each setting. An analyst quality review checked consistency before release. The forecast was run under conservative, base and optimistic cases, and growth rates for each segment were set so that the parts remain consistent with the whole. Estimates are reviewed periodically as new data becomes available.
Ultrapure Water Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 9.71 Billion |
| Market Size by 2035 | USD 20.64 Billion |
| CAGR | CAGR of 7.83% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Technology (Reverse Osmosis, Ion Exchange, Electrodeionization, Ultrafiltration, and Others) • By End Use (Semiconductor, Pharmaceutical, Power Generation, and Others) • By Application (Cleaning and Washing, Process Feed, and Others) • By Product Type (Consumables, Equipment, and Services) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Veolia, DuPont, Kurita Water Industries, Organo, Ecolab, Xylem, Pentair, Asahi Kasei, Nomura Micro Science |

Frequently Asked Questions
The market was valued at USD 9.71 Billion in 2025 and is projected to reach USD 20.64 Billion by 2035, growing at a CAGR of 7.83% during 2026–2035.
Asia Pacific leads, with a 43.18% share in 2025, and is also expected to grow fastest, at a CAGR of 9.21% during 2026–2035.
The major key players are Pall Corporation, Veolia, Evocus, Osmoflo, Ovivo, MANN+HUMMEL Water & Fluid Solutions, Pentair, Memstar USA, Kurita Water Industries Ltd., Synder Filtration, Inc., DuPont, Koch Separation Solutions, NX Filtration BV, and Evoqua Water Technologies LLC.
Fab expansion, pharmaceutical quality rules, power and hydrogen projects, water reuse and better technology drive demand.
Veolia, DuPont, Kurita Water Industries, Organo and Ecolab lead, along with Xylem, Asahi Kasei and Nomura Micro Science.
