
Urinalysis Market Report Scope & Overview:
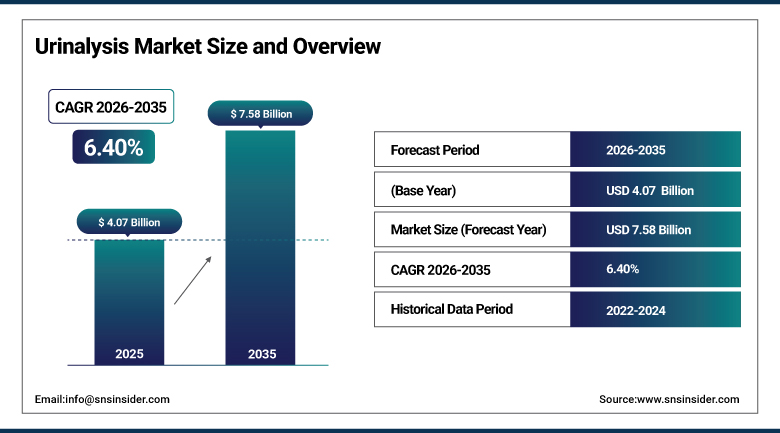
The Urinalysis Market was valued at USD 4.07 Billion in 2025 and is expected to reach USD 7.58 Billion by 2035, growing at a CAGR of 6.40% from 2026-2035.
The Urinalysis Market is growing as clinicians rely on quick, low-cost urine tests to screen for kidney disease, diabetes, urinary tract infections and pregnancy. Dipsticks and reagent strips remain the volume base, while automated chemistry and sediment analyzers lift productivity in hospitals and reference laboratories. Digital microscopy, artificial intelligence and smartphone-read home tests are widening what a urine sample can reveal. Rising chronic disease rates and antimicrobial resistance raise the value of early detection. Point-of-care analyzers and over-the-counter tests are moving testing closer to patients.
⮞In October 2025, the World Health Organization reported that one in six laboratory-confirmed bacterial infections in 2023 was resistant to antibiotics, and that more than 40% of E. coli cases resisted third-generation cephalosporins. Resistance raises the importance of fast urine screening before prescribing.
To Get more information Urinalysis Market - Request Free Sample Report
Urinalysis Market Trends
-
Automation of urine chemistry and sediment analysis in central laboratories
-
Digital microscopy and AI-based urine cell classification
-
Growth of point-of-care and CLIA-waived urine analyzers
-
Smartphone-read and over-the-counter home urine tests
-
Albumin-to-creatinine testing for early kidney disease detection
U.S. Urinalysis Market Outlook
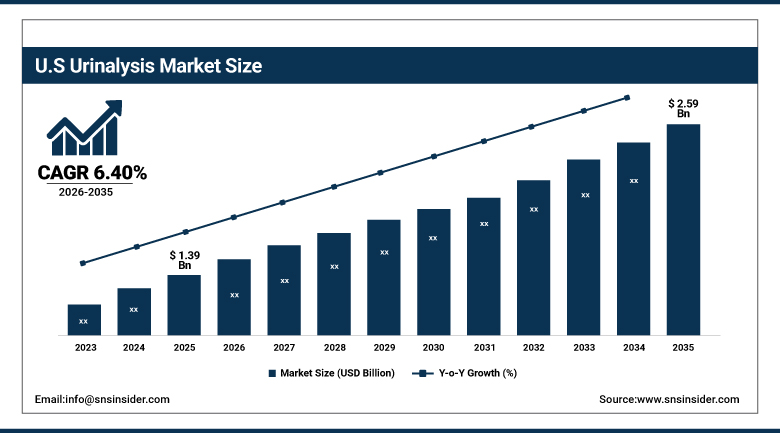
The U.S. Urinalysis Market was valued at USD 1.39 Billion in 2025 and is expected to reach USD 2.59 Billion by 2035, growing at a CAGR of 6.40% from 2026-2035.
The U.S. Urinalysis Market is the largest national market, supported by a high prevalence of chronic kidney disease and diabetes, routine urine testing in primary care and well-developed hospital and reference laboratory networks. Clinical laboratories run high volumes on automated analyzers, while physician offices use CLIA-waived tests. Regulators are clearing over-the-counter tests for home use. Kidney health guidelines now recommend regular albumin testing in at-risk adults. Reimbursement rules guide test selection.
⮞In March 2026, the Centers for Disease Control and Prevention reported that about 14% of U.S. adults, or roughly 37 million people, have chronic kidney disease, and 87% of them are unaware. Large undiagnosed populations create ongoing demand for urine screening.
Urinalysis Market Segment Analysis
-
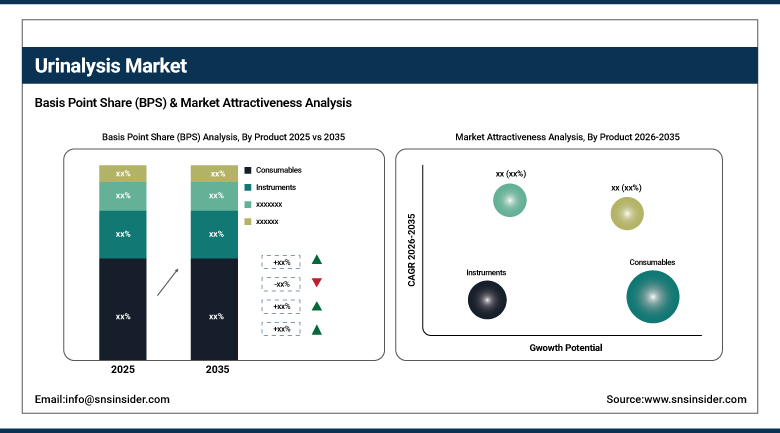
By Product, the Consumables segment dominated the Urinalysis Market with approximately 69.88% share in 2025, while the Instruments segment is the fastest growing with a CAGR of approximately 6.91%.
-
By Test Type, the Biochemical segment dominated the Urinalysis Market with approximately 49.19% share in 2025, while the Sediment segment is the fastest growing with a CAGR of approximately 6.80%.
-
By Application, the Urinary Tract Infection segment dominated the Urinalysis Market with approximately 30.69% share in 2025, while the Diabetes segment is the fastest growing with a CAGR of approximately 8.40%.
-
By End User, the Hospitals segment dominated the Urinalysis Market with approximately 39.35% share in 2025, while the Home Care segment is the fastest growing with a CAGR of approximately 8.01%.
By Product, Consumables Dominate the Urinalysis Market and Instruments Grow Fastest
Consumables lead because every urine test consumes a strip, reagent, cup or kit, so volumes recur with each sample. Dipsticks are inexpensive and accepted worldwide for first-line screening, and laboratories buy them in bulk through standing contracts. Reagent supply is tied to installed analyzers, which gives vendors a steady revenue base. Pregnancy and fertility kits add large retail volumes.
Instruments are the fastest growing as laboratories automate to handle rising test volumes and staff shortages. New analyzers combine chemistry, particle counting and digital imaging in a single workflow, reducing manual microscopy. Point-of-care devices with built-in connectivity are entering clinics and pharmacies. Vendors are launching higher-throughput platforms, which raises instrument placements.
⮞In February 2025, ACON Laboratories received a CLIA waiver for its Mission U120 Urine Touch Analyzer with Mission urinalysis reagent strips. The waiver extends automated urine testing into physician offices and clinics.
By Test Type, Biochemical Dominates the Urinalysis Market and Sediment Grows Fastest
Biochemical testing leads because dipstick chemistry reports glucose, protein, ketones, blood, leukocyte esterase and nitrite within minutes at low cost. It is the standard first-line screen in primary care, emergency departments and occupational health. Results guide decisions to order confirmatory culture or further tests, and automated readers improve consistency and recordkeeping.
Sediment analysis is the fastest growing as laboratories replace manual microscopy with flow cytometry and digital imaging. Automated systems count cells, casts and crystals more consistently and reduce review workload. Artificial intelligence classification is improving accuracy for abnormal samples. Demand for these platforms is rising in hospital laboratories that serve nephrology and infectious disease services.
⮞In September 2025, the UAE Ministry of Health and Prevention approved Biomerica's Fortel Kidney home urine microalbumin test for people with diabetes or hypertension. The approval shows regulators accepting more advanced urine tests outside laboratories.
By Application, Urinary Tract Infection Dominates the Urinalysis Market and Diabetes Grows Fastest
UTI takes the lead since it remains one of the most frequent bacterial infections, and every suspected infection usually starts with urine analysis. Women, elderly patients, and patients undergoing catheterization make up for a significant proportion of patients that visit the clinic. Leukocyte and nitrite strips determine the need for antibiotic treatment, which aligns with stewardship aims. Emergency departments and primary health care clinics provide the volume of patients.
Diabetes becomes one of the most rapidly growing fields since screening programs develop, and more patients get tested for kidney disease. Guidelines suggest routine urine testing for albumin and glucose for people with diabetes. Increase in diabetes rates in Asia, the Middle East, and Latin America expands the number of patients to be checked. Albumin at-home urine tests appear on the market.
⮞In May 2025, the National Kidney Foundation reported that more than 35 million U.S. adults are estimated to have chronic kidney disease and about 90% do not know it. Wider albumin testing is being promoted to close the gap.
By End User, Hospitals Dominate the Urinalysis Market and Home Care Grows Fastest
Hospitals lead because they run urine tests for admissions, emergency visits, surgery preparation and inpatient monitoring, and they maintain automated analyzers in central and satellite laboratories. Nephrology, obstetrics and infectious disease services generate frequent orders. Purchasing teams sign multi-year contracts for instruments and consumables, which keeps volumes concentrated in institutional settings.
Home care is the fastest growing end user as consumers adopt smartphone-read strips and over-the-counter tests for urinary infections, kidney health and fertility. Telehealth providers prescribe home kits, and regulators are clearing more products for non-professional use. Convenience and privacy encourage use, and results can be shared digitally with clinicians for follow-up.
⮞In September 2026, the Centers for Disease Control and Prevention reported that 40.1 million Americans have diabetes. The large patient group relies on regular urine monitoring, including at home.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
U.S. |
91.46 |
|
Europe |
Germany |
27.38 |
|
Asia Pacific |
China |
39.72 |
|
Latin America |
Mexico |
33.59 |
|
Middle East & Africa |
Saudi Arabia |
24.15 |
North America Urinalysis Market Insights
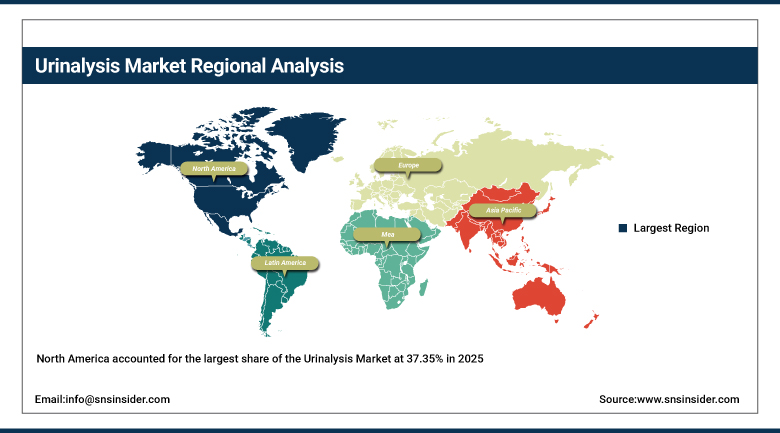
North America accounted for the largest share of the Urinalysis Market at 37.35% in 2025, led by the United States and followed by Canada. Chronic kidney disease, diabetes and aging populations create steady test volumes, and consolidated laboratory networks run automated platforms. The region also hosts several of the leading instrument and strip manufacturers.
Regulators are clearing more point-of-care and over-the-counter products, supporting home testing and pharmacy-based screening. Laboratories face labor shortages, which accelerates automation of sediment review. Reimbursement for albumin testing in at-risk adults is expanding, though pricing pressure from group purchasing organizations limits supplier margins.
⮞In November 2025, the Kidney Foundation of Canada reported that about 4.5 million Canadians live with chronic kidney disease, projected to exceed 6.2 million by 2050. Rising prevalence supports demand for screening tests.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Urinalysis Market Insights
Europe held about 23.91% of the Urinalysis Market in 2025 and is led by Germany, France, the United Kingdom, Italy and Spain. Several European companies, including Erba Mannheim, Analyticon and 77 Elektronika, produce analyzers and strips, and national health systems run large centralized laboratories.
Antimicrobial stewardship policies encourage accurate urine testing before antibiotic prescribing. The In Vitro Diagnostic Regulation has raised compliance requirements, which favors established suppliers. Public tenders and cost containment keep prices low, while aging populations support steady volumes. Digital microscopy is being adopted in larger laboratory networks.
⮞In September 2026, the UK Health Security Agency reported 44,879 E. coli bacteraemia cases in England in 2025-26, with the urinary tract the source in 48.6% of cases with a reported focus. The burden highlights the role of early urine diagnosis.
Asia Pacific Urinalysis Market Insights
Asia Pacific is projected to be the fastest growing region in the Urinalysis Market, at a CAGR of 7.93% over 2026-2035, and held about 25.84% share in 2025. China, Japan, India, South Korea and Australia lead. Expanding hospital capacity, health insurance coverage and a rising burden of diabetes and kidney disease are boosting test volumes.
Chinese manufacturers such as DIRUI, Mindray and URIT are gaining share with competitively priced analyzers, while Japanese companies Sysmex and ARKRAY lead in sediment and automated systems. Government screening programs in India and Southeast Asia are widening access, though rural laboratory capacity remains limited.
⮞In April 2025, the International Diabetes Federation reported 215.4 million adults with diabetes in the Western Pacific region and 106.9 million in South-East Asia in 2024. The size of the population at risk supports regular urine testing.
MEA & Latin America Urinalysis Market Insights
Latin America and the Middle East and Africa together hold about 12.90% of the Urinalysis Market. In Latin America, Brazil, Mexico, Argentina and Colombia lead, driven by public health systems, private laboratory chains and rising diabetes prevalence. Mexico's social security institute runs large laboratory networks.
In the Middle East and Africa, Saudi Arabia, the United Arab Emirates, Egypt and South Africa lead. Gulf countries invest in modern laboratories and approve advanced home tests, while sub-Saharan Africa relies on low-cost dipsticks distributed through donor programs. Import dependence and currency volatility affect pricing across both regions.
⮞In March 2026, Mexico's IMSS was reported to care for more than 2.3 million affiliated people with some degree of kidney disease, about 85,000 of whom need dialysis or replacement therapy. The burden underscores the need for screening.
Market Dynamics
Growth Drivers: Chronic Disease Prevalence and Decentralized Testing Drive Growth in the Urinalysis Market
Chronic disease prevalence is the main driver. Diabetes, hypertension and chronic kidney disease affect large and growing populations, and urine albumin and glucose testing is a guideline-recommended screen. Most people with early kidney disease are unaware, so public health programs promote routine testing. Aging populations add to urinary tract infection cases.
Decentralized testing adds momentum. Point-of-care analyzers, CLIA-waived tests and home kits move urinalysis out of central laboratories into clinics, pharmacies and homes. Smartphone readers improve accuracy and share data with clinicians. Telehealth growth supports prescription of home tests, and laboratories adopt automation to cope with higher volumes.
⮞In October 2025, the World Health Organization Western Pacific regional office reported that one in seven adults aged 30 and over in the region has diabetes. The prevalence supports demand for routine urine monitoring.
Restraints: Low Guideline Adherence and Price Pressure Restrain Growth in the Urinalysis Market
Poor compliance with guidelines hampers development. Clinicians frequently fail to request urine albumin screening tests, while patient compliance is poor too, which means that the actual market size cannot be maximized. Primary care physicians are not fully aware of the guidelines, and the practice in a busy clinic is more oriented on rapid testing rather than more complicated ones.
Price constraints pose additional restrictions. The cost of such urine tests is relatively low, and the competitive situation is tough because there are many producers. Price pressure is increasing, as group buying organizations and government procurement impose pricing pressures on vendors. European in vitro diagnostic guidelines impose additional burdens on smaller players.
⮞In 2023 data published by the Office of Disease Prevention and Health Promotion, only 39.8% of Medicare beneficiaries with chronic kidney disease received the recommended tests. The gap shows how much testing demand remains untapped.
Opportunities: Over-the-Counter Tests and Digital Microscopy Create Opportunities in the Urinalysis Market
Over-the-counter tests offer a major opportunity. Regulators are clearing home screening products for urinary tract infection, kidney health and fertility, and consumers value convenience and privacy. Connected apps allow results to be shared with clinicians, and retailers are expanding shelf space. Manufacturers that secure clearances early can build brand recognition.
Digital microscopy and artificial intelligence offer further potential. Automated imaging reduces manual review, improves consistency and supports remote reading across laboratory networks. New algorithms can flag abnormal cells and crystals for review. Laboratories short of skilled staff are likely to invest, and vendors can sell software upgrades and reagents alongside instruments.
⮞In October 2025, the U.S. FDA cleared Hangzhou AllTest Biotech's over-the-counter urinary tract infection test, which screens for leukocytes and nitrite, for home use. The clearance widens the consumer market for urine screening.
Recent Developments:
-
In July 2026, Beckman Coulter launched the DxU 1800 Urinalysis System in the United States at the ADLM conference. The system pairs a chemistry analyzer processing up to 300 samples an hour with a digital microscopy analyzer, and the company said manual microscopic review can fall below 3% of samples.
-
In October 2026, Siemens Healthineers launched the Atellica LumIQ Analyzer in Canada, a portable point-of-care urinalysis analyzer that also performs hCG pregnancy testing. The company said the device connects by Wi-Fi and targets primary care, emergency medical services and pharmacies.
-
In January 2026, Nova Biomedical received a CLIA waiver for its Allegro UACR assay, which measures urine albumin and creatinine and calculates the ratio on the Allegro point-of-care analyzer. The waiver allows kidney screening in clinics without a central laboratory.
Urinalysis Market Key Players
-
Siemens Healthineers AG
-
F. Hoffmann-La Roche Ltd
-
Sysmex Corporation
-
Beckman Coulter (Danaher Corporation)
-
ARKRAY, Inc.
-
ACON Laboratories, Inc.
-
Erba Mannheim
-
Analyticon Biotechnologies AG
-
Teco Diagnostics
-
Healthy.io
-
DIRUI Industrial Co., Ltd.
-
Sciteck Diagnostics
-
Hangzhou AllTest Biotech Co., Ltd.
-
Nova Biomedical
-
Biomerica, Inc.
-
Shenzhen Mindray Bio-Medical Electronics
-
URIT Medical Electronic Co., Ltd.
-
77 Elektronika Kft.
-
Clarity Diagnostics
-
Cardinal Health, Inc.
Urinalysis Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 4.07 Billion |
| Market Size by 2035 | USD 7.58 Billion |
| CAGR | CAGR of 6.40% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product (Consumables and Instruments) • By Test Type (Biochemical, Sediment, and Others) • By Application (Urinary Tract Infection, Diabetes, Kidney Disease, Pregnancy and Fertility, and Others) • By End User (Hospitals, Diagnostic Laboratories, Home Care, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Siemens Healthineers AG, F. Hoffmann-La Roche Ltd, Sysmex Corporation, Beckman Coulter (Danaher Corporation), ARKRAY, Inc., ACON Laboratories, Inc., Erba Mannheim, Analyticon Biotechnologies AG, Teco Diagnostics, Healthy.io, DIRUI Industrial Co., Ltd., Sciteck Diagnostics, Hangzhou AllTest Biotech Co., Ltd., Nova Biomedical, Biomerica, Inc., Shenzhen Mindray Bio-Medical Electronics, URIT Medical Electronic Co., Ltd., 77 Elektronika Kft., Clarity Diagnostics, Cardinal Health, Inc. |

Frequently Asked Questions
Key players include Siemens Healthineers, Roche, Sysmex, Beckman Coulter, ARKRAY, ACON Laboratories, Erba Mannheim, Analyticon, Teco Diagnostics, Healthy.io, DIRUI, Sciteck, Hangzhou AllTest, Nova Biomedical, Biomerica, Mindray, URIT, 77 Elektronika, Clarity Diagnostics and Cardinal Health.
Key opportunities include over-the-counter and smartphone-read home tests, digital microscopy with AI classification, point-of-care albumin testing and fast-growing Asia Pacific demand.
Rising prevalence of chronic kidney disease, diabetes and urinary tract infections, together with decentralized testing, is the main growth factor.
By Product, the Consumables segment dominated the market in 2025 with an estimated 69.88% share, supported by recurring strip and reagent use.
North America dominated the market with a share of 37.35% in 2025, driven by high chronic disease prevalence and advanced laboratory networks.
