
Urinary Tract Infection Testing Market Report Scope & Overview:
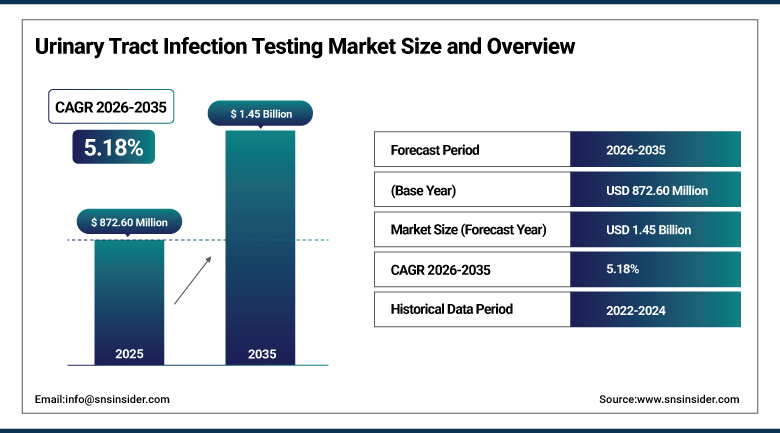
The Urinary Tract Infection Testing Market was valued at USD 872.60 Million in 2025 and is expected to reach USD 1.45 Billion by 2035, growing at a CAGR of 5.18% from 2026-2035.
Urinary tract infection testing market covers urinalysis strips and analyzers, urine culture, molecular panels and antibiotic susceptibility systems used to detect infection of the bladder, urethra and kidneys and to guide treatment. Urinary tract infections are among the most common bacterial infections, and rising antibiotic resistance is pushing clinicians to confirm the cause and the right drug before prescribing. Growth is supported by aging populations, point-of-care and home tests and automation in laboratories, while reimbursement limits and slow culture results shape adoption.
⮞On October, 2026, Genefluence announced the first clinical use of its rapid, near-patient PCR diagnostic platform for urinary tract infections at the Royal Hospital Chelsea in the United Kingdom. The system detects UTI-causing bacteria and antibiotic resistance genes in approximately one hour, supporting faster, targeted antibiotic selection.
To Get more information Urinary Tract Infection Testing Market - Request Free Sample Report
Urinary Tract Infection Testing Market Trends
- Point-of-care tests that report infection and antibiotic susceptibility in under an hour
- Home test kits linked to smartphones and telehealth prescribing
- Automation and artificial intelligence in urine analyzers and culture reading
- Rising antibiotic resistance driving demand for susceptibility testing
- Molecular panels that identify several pathogens and resistance genes at once
- Antibiotic stewardship programs that require confirmation before treatment
U.S. Urinary Tract Infection Testing Market Outlook
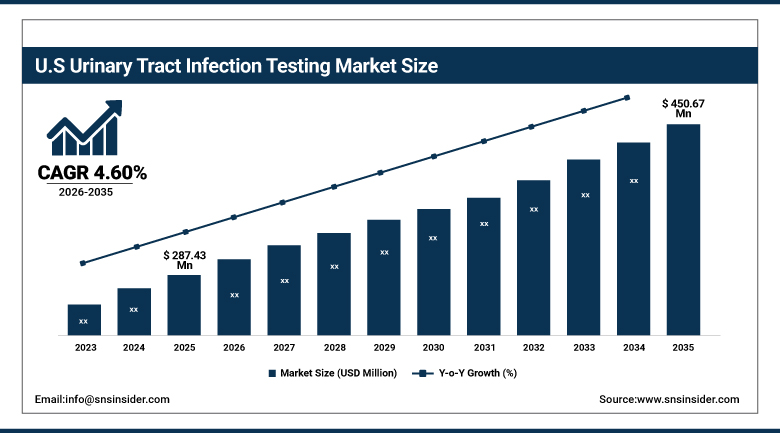
The U.S. Urinary Tract Infection Testing Market was valued at USD 287.43 Million in 2025 and is expected to reach USD 450.67 Million by 2035, growing at a CAGR of 4.60% from 2026-2035.
The U.S. Urinary Tract Infection Testing Market is the largest national market, supported by a large number of tests ordered through hospitals, reference laboratories, urgent care clinics and telehealth services. Laboratory networks run high volumes of urinalysis and culture, while home test kits are gaining use among women who want fast answers. Growth is moderated by reimbursement pressure, the cost of molecular panels, and limited evidence supporting some advanced tests.
⮞On November, 2025, Nanopath announced that the U.S. FDA had granted Breakthrough Device Designation to its molecular diagnostic platform for complicated urinary tract infections. The technology aims to provide actionable pathogen detection results within a clinical visit, potentially reducing dependence on conventional culture-based testing.
Urinary Tract Infection Testing Market Segment Analysis
- By Test Type, urinalysis segment dominated the Urinary Tract Infection Testing Market in 2025 with an estimated 46.00% share; susceptibility testing segment is the fastest-growing segment, with an estimated CAGR of 7.60% during 2026–2035.
- By Test Kit Type, laboratory test kits segment dominated the Urinary Tract Infection Testing Market in 2025 with an estimated 62.00% share; home test kits segment is the fastest-growing segment, with an estimated CAGR of 7.40% during 2026–2035.
- By Infection Type, cystitis segment dominated the Urinary Tract Infection Testing Market in 2025 with an estimated 48.00% share; pyelonephritis segment is the fastest-growing segment, with an estimated CAGR of 6.30% during 2026–2035.
- By End User, hospitals segment dominated the Urinary Tract Infection Testing Market in 2025 with an estimated 34.00% share; homecare settings segment is the fastest-growing segment, with an estimated CAGR of 8.10% during 2026–2035.
By Test Type, Urinalysis Dominates UTI Testing Market; Susceptibility Testing to Register Fastest Growth.
Urinalysis dominates the Urinary Tract Infection Testing Market because dipstick and automated analyzer tests are quick, low in cost and non-invasive, and they are the first step when a patient reports urinary symptoms. Clinics, hospitals and laboratories run large numbers of these tests each day to look for white cells, nitrites and blood. Automation and digital reading of strips allow high throughput and consistent results. Strips are also sold over the counter and used in primary care offices, so volumes stay high even when more advanced tests are available. Digital strip readers that send results to electronic records add value for busy clinics.
Susceptibility testing is projected to register the fastest growth as antibiotic resistance rises and clinicians want to know which drug will work before prescribing. New point-of-care systems report results in under an hour instead of days, and laboratories are adopting faster culture and molecular methods. Stewardship programs and payer interest in avoiding ineffective treatment support steady adoption. Laboratories are also testing automated culture reading and mass spectrometry to shorten the time to identify bacteria, which complements susceptibility panels. Payers that see fewer repeat visits and failed treatments are more willing to cover these tests.
⮞On September, 2026, Pattern Bioscience announced that the FDA had granted Breakthrough Device Designation to its Urine ID/AST Panel. Built on its single-cell microbiology platform, the test is designed to identify urinary pathogens and determine antimicrobial susceptibility directly from clinical specimens.
By Test Kit Type, Laboratory Test Kits Dominates UTI Testing Market; Home Test Kits to Register Fastest Growth.
Laboratory test kits dominate the Urinary Tract Infection Testing Market because accurate culture, microscopy and molecular testing still depend on laboratory equipment and trained staff. Hospitals and reference laboratories process the majority of samples, including those from complicated or recurrent infections. Established reimbursement and clinical guidelines also favor laboratory-confirmed results for treatment decisions. Standardized collection cups, transport tubes and quality controls add to kit sales, and instrument makers earn recurring revenue from reagents. Long-term supply contracts with hospital groups keep this segment stable.
Home test kits are projected to register the fastest growth as patients seek faster answers without a clinic visit. Smartphone readers, telehealth links and mail-in options let users test and receive advice the same day. Convenience, privacy and a growing number of women with recurrent infections support demand, while companies add better accuracy and clearer instructions. Pharmacies and online health services now offer kits with test strips, instructions and telehealth consults. Advances in color-reading apps and sample stabilization are improving accuracy, which should help attract users who are cautious about home testing.
⮞On October, 2026, BHR Biosynex announced an exclusive UK distribution agreement with TestCard for its smartphone-readable UTI self-test kit. The agreement expands access through pharmacy and retail channels, combining conventional urine dipstick testing with digital result interpretation.
By Infection Type, Cystitis Dominates UTI Testing Market; Pyelonephritis to Register Fastest Growth.
Cystitis dominates the Urinary Tract Infection Testing Market because bladder infections are the most common form of urinary infection, especially among women, and often recur. Many patients present to primary care or urgent care with burning, frequency and urgency, and a urine test is the standard first step. The high number of episodes keeps volumes of strips and cultures well ahead of other infection types. Women are far more likely than men to have urinary infections, and many experience repeat episodes within months, which increases the number of tests per patient. Children and older adults also contribute meaningful volume.
Pyelonephritis is projected to register the fastest growth as an aging population and more cases of resistant bacteria increase kidney infections and hospital admissions. These patients need culture and susceptibility testing to guide urgent treatment, which raises the value per test. Better detection of complicated cases in emergency settings also supports growth in this segment. Catheter-associated infections in hospitals and nursing homes add to demand, and laboratories use culture to guide second-line treatment when first-line drugs fail, supporting growth in more advanced tests.
⮞On July, 2025, the Infectious Diseases Society of America published its first dedicated guidelines for complicated urinary tract infections, including acute pyelonephritis. The recommendations emphasize patient-specific resistance assessment and targeted antibiotic selection using urine culture and susceptibility results.
By End User, Hospitals Dominates UTI Testing Market; Homecare Settings to Register Fastest Growth.
Hospitals dominate the Urinary Tract Infection Testing Market because they handle emergency admissions, catheter-related infections and complicated cases that require culture and susceptibility results. In-house laboratories run automated urinalysis and microbiology around the clock. Infection control programs also screen patients before surgery, which adds volume to routine testing. Many hospitals also operate outpatient clinics and emergency rooms that send large numbers of urine samples to the central laboratory. Group purchasing agreements and automated analyzers support high-volume, low-cost testing. Occupational and community clinics add further orders.
Homecare settings are projected to register the fastest growth as patients and caregivers use kits at home and telehealth services review results. Older adults in assisted living and people with recurrent infections benefit from quick checks. Manufacturers are designing simpler kits, and digital reporting links results to prescribers, which supports use outside of clinics. Telehealth firms, pharmacies and visiting nurse services support this shift by supplying kits, collecting samples and reviewing results. As payers promote care outside hospitals, use of such services is expected to expand.
⮞On January, 2025, the U.S. FDA granted 510(k) clearance to Safecare Biotech's over-the-counter Urinary Tract Infection Test, marketed as Testahead. The leukocyte esterase and nitrite urine dipstick test supports consumer-accessible screening outside conventional laboratory settings.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
North America |
United States |
91.50 |
|
Europe |
Germany |
24.00 |
|
Asia Pacific |
China |
35.00 |
|
Latin America |
Brazil |
47.00 |
|
Middle East & Africa |
Saudi Arabia |
27.00 |
North America UTI Testing Market Insights
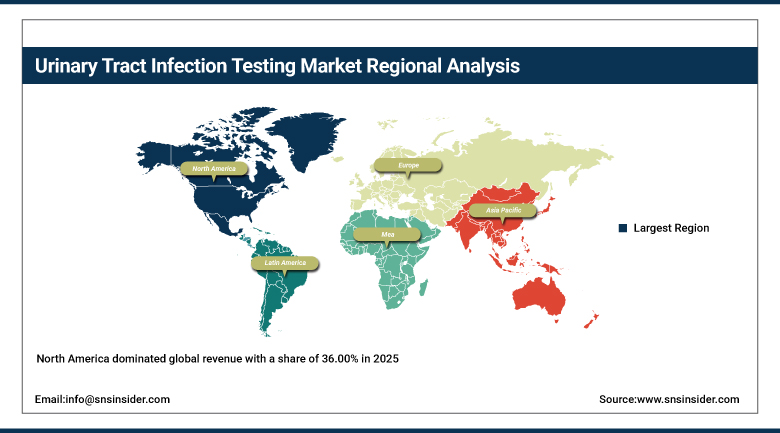
North America dominated revenue with a share of 36.00% in 2025. The United States accounts for majority of regional demand, with Canada adding volume. Quest Diagnostics, Labcorp, Abbott, Becton Dickinson, Cardinal Health, Bio-Rad and Thermo Fisher Scientific serve hospitals, reference laboratories and urgent care in the region. Retail pharmacies, telehealth platforms and urgent care chains also sell or order UTI tests, expanding the number of places where patients can be tested. Laboratory consolidation gives large networks pricing power with analyzer suppliers.
Leadership rests on high testing volumes, large laboratory networks, wide insurance coverage and fast adoption of new platforms. Telehealth and home kits are widening access, and resistance surveillance is encouraging susceptibility testing. Reimbursement scrutiny, the cost of molecular panels and a mature market for urinalysis moderate growth, though aging demographics support steady volumes. Regulatory clearance of point-of-care tests is also supporting new entrants. Growth in outpatient and home care, and in resistance surveillance programs funded by health systems, should keep testing volumes rising.
⮞On July, 2026, Beckman Coulter Diagnostics announced the U.S. launch of its DxU 1800 fully automated urinalysis system. The platform integrates urine chemistry analysis and microscopy, improving laboratory throughput, standardization and workflow efficiency for routine testing, including urinary tract infections.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe UTI Testing Market Insights
In Europe Germany, the United Kingdom, France, Italy and Spain lead regional demand. Roche, Siemens Healthineers, Sysmex, bioMérieux, Randox Laboratories and Arkray supply analyzers and kits to hospitals and laboratories across the region. Many European countries also run national resistance monitoring programs, and primary care guidelines increasingly recommend testing before repeat antibiotic courses, which supports demand for urinalysis and culture. Cross-border laboratory groups, which operate across several countries, standardize equipment and reagent purchases, giving large suppliers an advantage in tenders and long-term service contracts across the region.
National health systems promote antibiotic stewardship and primary care testing, and public funding supports point-of-care research. Common standards for susceptibility reporting help new systems enter several countries. Budget limits in public health systems, slow procurement and caution about advanced molecular panels moderate growth, though resistance concerns keep interest in rapid testing high. Research funding for rapid diagnostics through public prizes and university programs is producing a pipeline of new systems, and spin-out companies are seeking partners to reach hospital and primary care customers.
⮞On April, 2026, Sysmex Europe introduced the UC-1100 semi-automated urine chemistry analyzer. The system expands its urinalysis portfolio with improved connectivity, compact design and flexible workflows for routine urine testing in laboratories, clinics and near-patient environments.
Asia Pacific UTI Testing Market Insights
Asia Pacific is projected to be the fastest-growing region, at a CAGR of 6.70% during 2026-2035. China leads regional demand, followed by Japan, India, South Korea and Australia, supported by growing hospital networks, larger elderly populations and rising awareness of infection. Sysmex, Arkray, ACON Laboratories, Roche, Siemens Healthineers and local manufacturers supply the region. Government initiatives to expand primary health centers and insurance coverage in China and India bring more patients into testing. Japan and South Korea are mature markets with high use of automated analyzers.
Expanding diagnostic laboratory chains, new private hospitals and government health programs increase test volumes. Local companies are developing low-cost tests suited to clinics without advanced equipment. Uneven access to laboratories in rural areas, price sensitivity and limited reimbursement moderate growth, but large populations and rising incomes provide a wide base. Medical tourism hubs in Thailand, Singapore and India also add volume. Companies partner with local distributors and laboratory chains to reach smaller cities, and training programs help clinics select suitable tests.
⮞On July, 2026, the China Association of In-Vitro Diagnostics reported on URIT's UC-1800 automatic urine analyzer, featuring image-based strip analysis, automated sample handling and throughput of up to 480 tests per hour, supporting higher-volume routine urinalysis in Chinese diagnostic laboratories.
MEA & Latin America UTI Testing Market Insights
In Latin America, Brazil leads, followed by Mexico, Argentina, Colombia and Chile. Private laboratory chains and public hospitals are the main buyers, and urinalysis remains the most used test. Currency swings and uneven access to microbiology services limit adoption of advanced tests. Large private hospital groups and laboratory chains in Brazil and Mexico adopt automated analyzers first, while public facilities rely on dipsticks and basic culture. International suppliers work through distributors and local partnerships. Public tenders for laboratory supplies are a key sales channel in Latin America, and price competition from local producers is strong, so international brands often focus on automated platforms and premium products for private hospitals and large laboratory groups.
In the Middle East and Africa, Saudi Arabia, the United Arab Emirates, South Africa and Egypt lead demand. Hospital expansion and medical tourism in Gulf countries support testing, while limited laboratory capacity in parts of Africa restrains growth. Government investment in hospitals, insurance coverage and screening programs is slowly improving access to tests, and mobile laboratories and low-cost strips help reach remote communities in several countries. Private insurers and employer health plans in the Gulf countries are widening coverage for diagnostic testing, and new hospital cities are specifying automated urinalysis and microbiology from the start. Distributors with strong service teams hold a clear advantage in winning and keeping accounts.
⮞On July, 2025, researchers published a prospective study in JMIR Medical Informatics evaluating diagnostic stewardship for urine culture ordering at a hospital in Riyadh, Saudi Arabia. A clinical decision-support intervention reduced inappropriate urine culture orders from 41.6% to 36.4%, supporting more targeted diagnostic utilization.
Market Dynamics
Growth Drivers: Antibiotic Resistance, Aging Populations and Point-of-Care Tests
Rising resistance to common oral antibiotics makes it important to confirm the cause of infection and choose an effective drug. Clinicians and payers increasingly support testing that avoids repeated treatment. Hospitals and clinics also face pressure to reduce unnecessary antibiotic use, which supports the case for tests that identify infection accurately.
Older populations have more urinary infections and catheter use, and point-of-care and home tests make testing easier. Automation also allows laboratories to process more samples. Manufacturers can win business by pairing instruments with software that sends results straight to electronic health records and prescribing tools.
⮞On October, 2025, the World Health Organization published its Global Antimicrobial Resistance Surveillance Report, analyzing more than 23 million bacteriologically confirmed infection cases, including urinary tract infections. Data from 110 countries highlighted the importance of strengthening resistance surveillance and microbiological testing capabilities.
Restraints: Slow Culture Results and Reimbursement Limits
Standard culture takes two to three days, and many clinicians treat before results arrive, which reduces use of confirmatory tests. Sample collection errors and contaminated specimens also reduce the reliability of results and add to repeat testing.
Reimbursement for advanced molecular panels is limited, and evidence of clinical benefit is still being gathered, which slows adoption in some health systems. Limited laboratory capacity in rural areas of low-income countries further restricts the reach of advanced methods.
Opportunities: Rapid Susceptibility Testing, Home Testing and Emerging Markets
Systems that report both infection and antibiotic susceptibility in under an hour can change how clinics prescribe and are attracting prizes and funding. Combining results with clinical decision tools could help physicians narrow treatment choices and reduce hospital stays.
Home testing with telehealth, and low-cost tests for clinics in emerging markets, provide new customer groups for kit makers and laboratories. Public funding, prizes and grants for rapid diagnostics are also lowering the cost of developing new systems.
⮞On April, 2026, Biotia announced the publication of a clinical validation study evaluating its next-generation sequencing and machine-learning-based UTI diagnostic approach. The technology detects bacterial and fungal pathogens directly from urine specimens and profiles antimicrobial resistance, creating opportunities for culture-independent testing.
Recent Developments:
- In June 2026, Quest Diagnostics and Hackensack Meridian CDI published a national study showing about 69.50% of UTI-causing bacterial strains were non-susceptible to common oral antibiotics.
- In March 2026, the University of Reading announced a six-hour UTI susceptibility test, with spin-out Astratus Limited working to commercialize it.
- In June 2024, Sysmex Astrego won the GBP 8.00 million Longitude Prize on AMR for its PA-100 AST System, a point-of-care urine susceptibility test.
- In November 2022, Module Innovations of India reported USense, a credit card-sized point-of-care UTI test.
Urinary Tract Infection Testing Market Key Players are:
-
Bio-Rad Laboratories, Inc.
-
Cardinal Health, Inc.
-
F. Hoffmann-La Roche Ltd
-
Laboratory Corporation of America Holdings (Labcorp)
-
Quest Diagnostics Incorporated
-
Randox Laboratories Ltd.
-
Siemens Healthineers AG
-
Thermo Fisher Scientific Inc.
-
Danaher Corporation
-
QIAGEN N.V.
-
bioMérieux SA
-
Sysmex Corporation
-
Arkray, Inc.
-
Becton, Dickinson and Company
-
Accelerate Diagnostics, Inc.
-
T2 Biosystems, Inc.
-
Beckman Coulter, Inc.
-
Focus Diagnostics
Urinary Tract Infection Testing Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 872.60 Million |
| Market Size by 2035 | USD 1.45 Billion |
| CAGR | CAGR of 5.18% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Test Type (Urinalysis, Urine Culture, and Susceptibility Testing) • By Test Kit Type (Laboratory Test Kits and Home Test Kits) • By Infection Type (Cystitis, Urethritis, and Pyelonephritis) • By End User (Hospitals, Diagnostic Laboratories, Homecare Settings, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Abbott Laboratories; ACON Laboratories, Inc.; Bio-Rad Laboratories, Inc.; Cardinal Health, Inc.; F. Hoffmann-La Roche Ltd; Laboratory Corporation of America Holdings (Labcorp); Quest Diagnostics Incorporated; Randox Laboratories Ltd.; Siemens Healthineers AG; Thermo Fisher Scientific Inc.; Danaher Corporation; QIAGEN N.V.; bioMérieux SA; Sysmex Corporation; Arkray, Inc.; Becton, Dickinson and Company; Accelerate Diagnostics, Inc.; T2 Biosystems, Inc.; Beckman Coulter, Inc.; Focus Diagnostics |

Frequently Asked Questions
Key players include Abbott Laboratories, ACON Laboratories, Inc., Bio-Rad Laboratories, Inc., Cardinal Health, Inc., F. Hoffmann-La Roche Ltd, Laboratory Corporation of America Holdings (Labcorp), Quest Diagnostics Incorporated and Thermo Fisher Scientific Inc.
Key opportunities include rapid point-of-care susceptibility testing, home testing linked to telehealth, and low-cost tests for emerging markets.
The major growth factor is rising antibiotic resistance, which increases the need to confirm the cause of infection and choose an effective drug.
By Test Type, the Urinalysis segment dominated the market in 2025 with an estimated 46.00% share, supported by its low cost, speed and use as the first test.
North America dominated the market with a share of 36.00% in 2025, driven by high testing volumes, large laboratory networks and broad insurance coverage.
