
Water Desalination Equipment Market Report Scope & Overview:
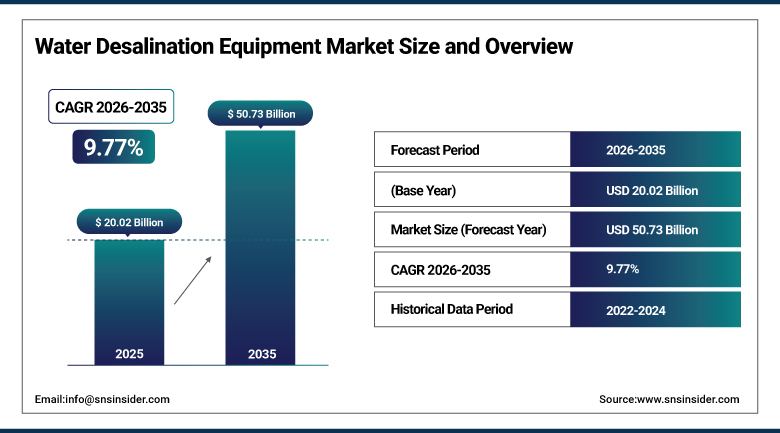
The Water Desalination Equipment Market was valued at USD 20.02 Billion in 2025 and is expected to reach USD 50.73 Billion by 2035, growing at a CAGR of 9.77% from 2026-2035.
The Water Desalination Equipment Market growth is being driven primarily by the scarcity of freshwater reserves, coupled with rising demand for water in arid regions that lack natural surface water sources such as lakes and rivers. According to the World Economic Forum, global freshwater demand is projected to exceed supply by 40% by 2030, leaving an estimated 1.6 billion people without access to safely managed drinking water, with approximately 4 billion people currently living in water-scarce regions and one in four cities facing water insecurity. Desalination equipment removes dissolved salts and minerals from seawater, brackish water, and other water sources, converting them into potable water suitable for municipal consumption as well as industrial processes across chemical, mining, oil and gas, power generation, and pharmaceutical applications. Rapid improvements in desalination technologies, including advances in membrane materials and energy-efficient system integration, continue to lower operational costs while governments worldwide invest in new desalination facilities to address escalating water scarcity.
On May 2024, Veolia obtained a USD 320 million contract from SIDEM, a Veolia subsidiary, to provide engineering services and supply technology for the Hassyan seawater desalination facility in Dubai, United Arab Emirates, that is going to have an 818,000 cubic meters per day production capacity and be the biggest desalination facility operating on solar power in the world when it achieves its maximum capacity in 2027. It demonstrates continuing high investments into energy-efficient desalination facilities in the Middle East and confirms competitive advantages of water technology providers that are able to provide such technologies and capacities as required by governments.
To Get more information Water Desalination Equipment Market - Request Free Sample Report
Water Desalination Equipment Market Trends
-
Rising adoption of energy-efficient reverse osmosis technology to reduce desalination operating costs.
-
Growing integration of renewable and solar energy sources to power large-scale desalination facilities.
-
Expanding use of AI-driven predictive platforms to monitor and forecast desalination water quality parameters.
-
Increasing government investment in brackish water desalination to serve inland, water-stressed communities.
-
Rising incorporation of digital monitoring and process control technology to enhance desalination plant operations.
-
Growing collaboration between water technology suppliers and utilities on large-scale national water security initiatives.
U.S. Water Desalination Equipment Market Outlook
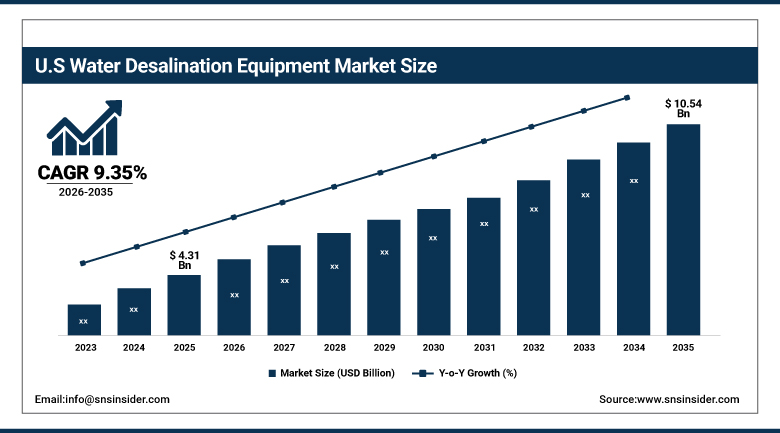
The U.S. Water Desalination Equipment Market was valued at USD 4.31 Billion in 2025 and is expected to reach USD 10.54 Billion by 2035, growing at a CAGR of 9.35% from 2026-2035.
The growth of the U.S. Water Desalination Equipment Market remains driven by increasing water scarcity challenges in the arid and coastal areas of the country along with continuing investment of municipal authorities in building desalination plants for diversifying water supplies. The municipal water utilities keep on expanding their desalination facilities in order to decrease their dependence on the already strained surface water and groundwater resources especially in such states as California, Texas, and Florida, where population growth keeps exceeding the existing capacity of conventional water supplies. Energy-saving reverse osmosis technologies continue improving economic efficiency of desalination projects for a growing number of municipalities across the country. Continued investment in brackish water desalination also supports market growth since this option is more economical than seawater desalination.
The Water Replenishment District of Southern California and the City of Torrance broke ground on a USD 166.5 million brackish water desalination expansion project in California, extending the region's water recycling and desalination infrastructure to bolster local water supply resilience amid ongoing drought conditions. The groundbreaking illustrates how U.S. municipal water utilities continue to pursue large-scale brackish water desalination investment as a strategic response to worsening water scarcity, reinforcing sustained domestic demand for desalination equipment even as broader municipal infrastructure budgets remain constrained.
Water Desalination Equipment Market Segment Analysis
-
By Technology, the Reverse Osmosis segment dominated the Water Desalination Equipment Market with approximately 55.60% share in 2025, and is also the fastest growing with a CAGR of approximately 10.20%.
-
By Source, the Seawater segment dominated the Water Desalination Equipment Market with approximately 60.40% share in 2025, while the Brackish Water segment is the fastest growing with a CAGR of approximately 9.20%.
-
By Application, the Municipal segment dominated the Water Desalination Equipment Market with approximately 51.80% share in 2025, while the Industrial segment is the fastest growing with a CAGR of approximately 10.40%.
By Technology, Reverse Osmosis Dominates the Water Desalination Equipment Market and Also Grows Fastest
Reverse osmosis dominates the market because the technology offers superior effectiveness, chemical and biological stability, and substantially lower energy requirements compared to thermal desalination methods including multi-stage flash and multi-effect distillation. Widespread adoption of reverse osmosis continues to be reinforced by desalination patents that have grown drastically since 2008, signifying intensifying innovation rivalry among suppliers seeking to further improve membrane performance and reduce energy consumption.
Reverse osmosis is also the fastest-growing technology as continued advancements in membrane materials and system integration reshape the industry toward greater efficiency and sustainability. Energy consumption of reverse osmosis desalination plants has declined by approximately 35% over the past decade, reinforcing the technology's growing cost advantage relative to legacy thermal desalination methods and supporting its accelerating adoption across both new-build and plant refurbishment projects.
By Source, Seawater Dominates the Water Desalination Equipment Market and Brackish Water Grows Fastest
Seawater dominates the market because the vast, effectively unlimited supply of ocean water continues to make seawater desalination the preferred source for large-scale municipal and industrial water production, particularly across coastal regions facing acute freshwater scarcity. The scale of major seawater desalination infrastructure investment across the Middle East and other water-stressed coastal regions continues to sustain seawater's position as the largest source category for desalination equipment suppliers.
Brackish water is the fastest-growing source category as inland water utilities increasingly adopt brackish water desalination to diversify water supply portfolios at lower capital and operating cost than seawater desalination requires. This growth is reinforced by expanding brackish water desalination investment across inland, water-stressed regions where groundwater sources contain elevated salinity levels unsuitable for direct municipal use without treatment.
By Application, Municipal Dominates the Water Desalination Equipment Market and Industrial Grows Fastest
Municipal applications account for the largest portion of the market owing to the obligation of water utilities to provide potable water for people in urban areas around the world, an obligation that has been becoming difficult to fulfill owing to increasing urban populations and development of megacities that decrease the efficiency of the existing infrastructure used to deliver municipal water supplies.
Industrial applications are the fastest growing applications category owing to the increase in demand for process water among power generation, oil and gas, mining, food and beverage, and pharmaceuticals industries, which makes the use of desalination inevitable for their water security. The growth in the industrial consumption of water in stressed water environments where desalination emerges as the only viable water source makes the case even more compelling.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Middle East & Africa |
Saudi Arabia |
42.60% |
|
Asia Pacific |
China |
38.60% |
|
North America |
United States |
82.60% |
|
Europe |
Spain |
29.60% |
|
Latin America |
Chile |
31.60% |
North America Water Desalination Equipment Market Insights
North America holds a considerable proportion of the world market for Water Desalination Equipment with the rise of water shortage fears in the U.S due to increasing numbers of arid and coastal regions in addition to municipalities' investments in both seawater and brackish water desalination systems. The water utility companies continue to invest in desalination plants to help cope with the worsening situation of droughts and the rising population that exceeds the capabilities of traditional water sources.
Canada and Mexico provide further demand due to continued consideration of desalination as a potential water security measure by regional water utilities. Large scale investments in brackish water desalination plants are anticipated to ensure steady regional growth over the forecast period.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe & Latin America Water Desalination Equipment Market Insights
Europe represents a meaningful share of the global Water Desalination Equipment Market, anchored by Spain's extensive desalination infrastructure and the United Kingdom's growing investment in desalination capacity, exemplified by recent contract awards for new coastal desalination facilities. The region's water technology suppliers continue to lead in developing energy-efficient, environmentally compliant desalination systems suited to Europe's stringent environmental regulatory framework.
Latin America's market is led by Chile, where the country's substantial mining industry continues to drive significant desalination demand given the sector's large process water requirements in the country's arid northern regions. Brazil and Mexico are contributing incremental growth as regional water utilities and industrial operators continue to evaluate desalination investment to address localized water scarcity.
Asia Pacific Water Desalination Equipment Market Insights
Asia Pacific is the fastest-growing regional market, expanding at a CAGR of approximately 10.60% from 2026 to 2035, driven by rapidly rising water scarcity concerns, expanding industrial water demand, and growing government investment in desalination infrastructure across China and India. China's large domestic industrial base continues to drive substantial regional demand for both municipal and industrial desalination capacity, while India's expanding coastal urban population is extending desalination infrastructure investment into new markets.
Singapore continues to lead in desalination technology innovation, with government agencies advancing feasibility studies for next-generation dual-mode desalination facilities. This combination of water scarcity pressure and government-backed infrastructure investment is expected to sustain Asia Pacific's position as the fastest-growing market through the forecast period.
Middle East & Africa Water Desalination Equipment Market Insights
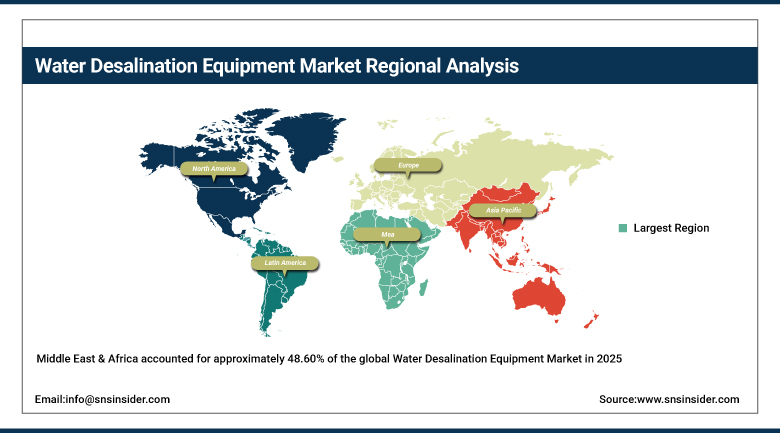
Middle East & Africa accounted for approximately 48.60% of the global Water Desalination Equipment Market in 2025, making it the largest regional market, driven by acute scarcity of freshwater reserves across the region's predominantly arid landscape, which lacks natural surface water sources such as lakes and rivers. Saudi Arabia and the United Arab Emirates continue to lead substantial national desalination infrastructure investment, with major suppliers securing multi-hundred-million-dollar contracts for large-scale, increasingly solar-powered desalination facilities.
Egypt and other North African markets are contributing incremental growth as regional governments continue to invest in desalination infrastructure to address chronic freshwater scarcity. The scale of the region's ongoing desalination capacity expansion, combined with growing emphasis on renewable-powered facilities, is expected to sustain the Middle East & Africa's position as the largest market through the forecast period.
Market Dynamics
Growth Drivers: Escalating Water Scarcity and Government Infrastructure Investment Fuel Market Growth
Increasing global water shortages pose as the main reason for the growth of the Water Desalination Equipment Market because the demand for freshwater far surpasses its availability in an increasing number of regions all around the world where billions of people live in water-stressed areas and have little or no access to properly managed drinking water. Deteriorating environmental conditions, including changing weather patterns and droughts, further increase investments made by governments and utilities in water desalination systems.
The second key growth factor is increasing government spending on water desalination plants as governments in water-stressed countries invest in such technologies in order to solve their water shortage problems and develop economically. Increased water demand in industrial applications, such as electricity production, oil & gas and mining industries, among others, also increases this trend.
Restraints: High Capital Costs and Environmental Concerns Hamper the Market Growth
The high capital cost associated with large-scale desalination facility construction represents a meaningful restraint on market growth, as the substantial upfront investment required for reverse osmosis and thermal desalination infrastructure can constrain project development, particularly in developing markets with limited public infrastructure financing capacity. This cost consideration continues to favor well-capitalized government and utility customers over smaller, resource-constrained municipalities.
Environmental concerns regarding brine discharge and marine ecosystem impact represent a further restraint, as desalination facilities must navigate increasingly stringent environmental regulations governing the composition, temperature, and disposal location of concentrated brine byproduct. This regulatory complexity requires careful facility siting and discharge management, adding cost and complexity relative to conventional water treatment infrastructure.
Opportunities: Renewable-Powered Desalination and AI-Driven Plant Optimization Boost Market Exapnsion
Continued integration of renewable and solar energy sources to power large-scale desalination facilities represents a substantial opportunity, as governments and utilities increasingly prioritize sustainable, decarbonized water infrastructure investment. Suppliers that can deliver reliable, cost-competitive renewable-powered desalination technology are positioned to capture premium government contracts as national sustainability commitments continue to shape infrastructure procurement decisions.
The continued development of AI-driven predictive platforms for desalination plant monitoring and optimization offers a further avenue for growth, as operators increasingly seek to forecast water quality parameters, including turbidity and salinity spikes, before they affect plant output. Suppliers that can pair advanced desalination hardware with intelligent digital monitoring capability are well positioned to capture demand from utilities seeking improved operational reliability and reduced downtime.
Recent Developments:
-
2026: IDE Technologies signed a contract with the State Industries Promotion Corporation of Tamil Nadu to design, construct, and operate a new seawater reverse osmosis desalination facility in Mullakadu, Tuticorin, expected to produce 60 million liters of clean filtered seawater per day.
-
2026: ACCIONA announced it had created a predictive AI platform to forecast changes in water quality parameters, including turbidity and salinity spikes, across its desalination facilities, with an example deployment at the Tampa Bay desalination plant in Florida.
-
2024: Siemens, TAQA, and SUEZ signed a Memorandum of Understanding to collaborate on the Mohamed bin Zayed Water Initiative, a global competition supporting advanced water technology development.
Water Desalination Equipment Market Key Players
-
Veolia Water Technologies
-
Xylem Inc.
-
DuPont Water Solutions
-
General Electric Company
-
Doosan Enerbility Co., Ltd.
-
SUEZ Water Technologies & Solutions
-
Acciona S.A.
-
IDE Technologies Ltd.
-
Alfa Laval AB
-
Aquatech International LLC
-
Danfoss A/S
-
Toray Industries, Inc.
-
Wärtsilä Corporation
-
Biwater Holdings Ltd.
-
LG Chem Ltd.
-
Guangzhou KangYang Seawater Desalination Equipment Co., Ltd.
-
Fisia Italimpianti S.p.A.
-
Abengoa Water S.L.U.
-
Befesa Agua S.L.
-
Hyflux Ltd.
Water Desalination Equipment Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 20.02 Billion |
| Market Size by 2035 | USD 50.73 Billion |
| CAGR | CAGR of 9.77% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Technology (Reverse Osmosis, Multi-Stage Flash Distillation, Multi-Effect Distillation, Others) • By Source (Seawater, Brackish Water, River Water) • By Application (Municipal, Industrial, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Veolia Water Technologies, Xylem Inc., DuPont Water Solutions, General Electric Company, Doosan Enerbility Co., Ltd., SUEZ Water Technologies & Solutions, Acciona S.A., IDE Technologies Ltd., Alfa Laval AB, Aquatech International LLC, Danfoss A/S, Toray Industries, Inc., Wärtsilä Corporation, Biwater Holdings Ltd., LG Chem Ltd., Guangzhou KangYang Seawater Desalination Equipment Co., Ltd., Fisia Italimpianti S.p.A., Abengoa Water S.L.U., Befesa Agua S.L., Hyflux Ltd. |

Frequently Asked Questions
Key players include Veolia Water Technologies, Xylem Inc., DuPont Water Solutions, General Electric Company, SUEZ Water Technologies & Solutions, Acciona S.A., and IDE Technologies Ltd., among other global water technology suppliers.
Continued integration of renewable and solar energy sources to power desalination facilities and continued development of AI-driven predictive plant monitoring platforms represent the primary opportunities.
Growth is primarily driven by escalating global water scarcity combined with rising government investment in desalination infrastructure to address chronic freshwater shortages.
By Technology, Reverse Osmosis dominated the market with approximately 55.60% share in 2025, reflecting its superior effectiveness and substantially lower energy requirements relative to thermal desalination methods.
Middle East & Africa dominated the market with approximately 48.60% share in 2025, driven by acute freshwater scarcity across the region's predominantly arid landscape.
