
Water Soluble Pods Packaging Market Report Scope & Overview:
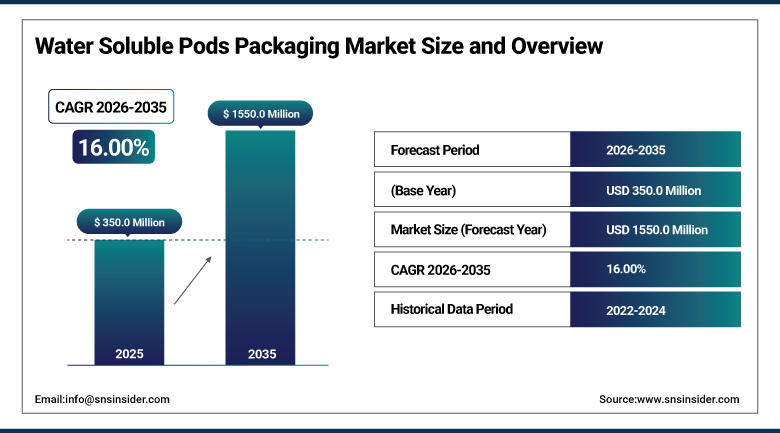
The Water Soluble Pods Packaging Market was valued at USD 350.0 Million in 2025 and is expected to reach USD 1,550.0 Million by 2035, growing at a CAGR of 16.00% from 2026–2035.
Water soluble pods packaging is the thin polyvinyl alcohol film that wraps a pre-measured dose of laundry detergent, dishwasher tablet, or agrochemical and dissolves completely the moment it hits water, leaving nothing behind but the product it was protecting. It's turned what used to require a measuring cup and a guess into a single, mess-free toss into a machine, which is exactly why laundry pods went from a novelty to a shelf staple across major consumer brands within about a decade. The technology's appeal has expanded well past cleaning products into personal care, agriculture, and even pharmaceutical unit-dose applications now chasing the same precision and convenience.
MACK partnered with Notpla in 2023 to introduce what the companies called the first commercial application of a plant-based, water-soluble film in the cleaning industry, aiming to replace polyvinyl alcohol, the material that has dominated water-soluble pod film since the category began. PVOH has been the near-universal choice for detergent pods for decades precisely because it's cheap, reliable, and dissolves predictably, so a genuine commercial alternative reaching market is a bigger deal than it might sound: it's the first real crack in a single-material monopoly that's defined the entire product category.
To Get more information Water Soluble Pods Packaging Market - Request Free Sample Report
Water Soluble Pods Packaging Market Trends
-
Cold-water dissolution reformulation continues advancing, letting pods dissolve fully and cleanly in lower-temperature wash cycles that consumers increasingly prefer for energy savings and fabric care.
-
Bio-based and marine-degradable polymer alternatives to conventional PVOH continue moving from pilot programs toward genuine commercial-scale production as brand owners seek credible sustainability claims.
-
Government bans on single-use plastics in major markets, including India, continue pushing manufacturers and brand owners toward water-soluble pod formats as a compliant alternative to conventional packaging.
-
Application expansion beyond home care continues accelerating, with water-soluble unit-dose formats increasingly adopted across agrochemicals, hospitality amenities, and emerging pharmaceutical and nutraceutical products.
-
Manufacturers continue investing in improved PVOH film strength and barrier properties, supporting expanded solubility performance without sacrificing the mechanical durability pods need to survive shipping and handling.
U.S. Water Soluble Pods Packaging Market Outlook
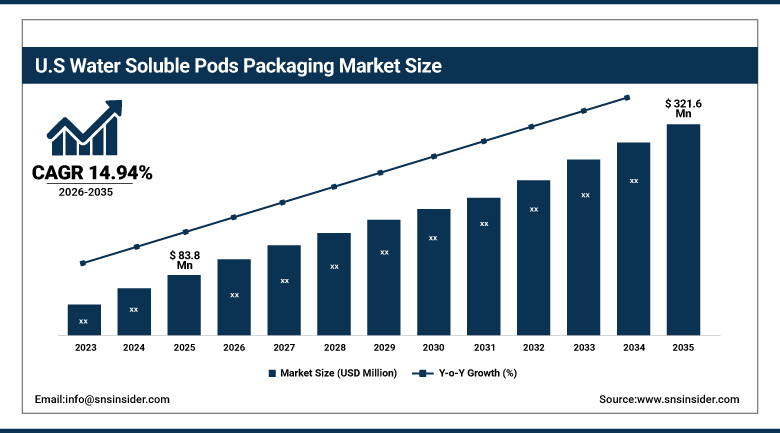
The U.S. Water Soluble Pods Packaging Market was valued at approximately USD 83.8 Million in 2025 and is expected to reach approximately USD 321.6 Million by 2035, growing at a CAGR of approximately 14.94%.
Demand in the United States is anchored by a large home and laundry care industry projected to keep growing steadily, alongside major consumer product companies that have built entire product lines around unit-dose pod formats. A small number of specialized material science companies continue supplying the PVOH film that underpins nearly every detergent pod sold domestically, giving the country deep technical expertise concentrated in a handful of Midwest manufacturing sites. Growing brand owner interest in personal care, agrochemical, and pharmaceutical applications is expanding pod technology well beyond its traditional home care base.
MonoSol, a division of Tokyo-based Kuraray Group best known for the PVOH film used in detergent pods sold by major consumer brands worldwide, announced a headquarters relocation to Portage, Indiana in August 2025, reflecting the company's strategic growth plans. The move keeps MonoSol's manufacturing and technical base concentrated in the U.S. Midwest even as its Japanese parent company continues expanding its water-soluble film portfolio globally, underscoring how much of the industry's core material science still runs through a small handful of specialized American and Japanese producers.
Water Soluble Pods Packaging Market Segment Analysis
-
By Type, the Multi Chamber Water Pods segment dominated the Water Soluble Pods Packaging Market with approximately 48.60% share in 2025, while the Dual Layer Water Pods segment is the fastest growing with a CAGR of approximately 17.80%.
-
By Material, the Polyvinyl Alcohol (PVOH) segment dominated the Water Soluble Pods Packaging Market with approximately 82.40% share in 2025, while the Others (bio-based polymers) segment is the fastest growing with a CAGR of approximately 19.60%.
-
By Thickness, the 30–60 Micrometer segment dominated the Water Soluble Pods Packaging Market with approximately 54.20% share in 2025, while the Below 30 Micrometer segment is the fastest growing with a CAGR of approximately 18.20%.
-
By Application, the Detergent segment dominated the Water Soluble Pods Packaging Market with approximately 58.40% share in 2025, while the Dish Wash segment is the fastest growing with a CAGR of approximately 17.40%.
By Type, multi chamber water pods dominates, dual layer water pods grows fastest
Multi chamber water pods held the largest share of the type segment in 2025, favored by major detergent brands for their ability to keep separate active ingredients, cleaning agents, enzymes, and fragrance compounds, isolated from each other until the pod dissolves and everything mixes at once inside the wash. That formulation flexibility has made multi-chamber design the standard architecture for premium laundry and dishwasher pod products across nearly every major consumer brand.
Dual layer water pods are growing fastest as manufacturers seek a middle ground between the simplicity of single-layer pods and the formulation complexity of multi-chamber designs, offering some ingredient separation without the full manufacturing complexity multi-chamber production requires. That balance of functional benefit and production efficiency is pulling this type category's growth ahead of the broader, more established pod format mix.
By Material, PVOH dominates, bio-based alternatives grow fastest
The polyvinyl alcohol accounted for the overwhelming majority share of the material market in 2025, retaining its dominance in the water soluble pod film materials segment since inception, owing to its inexpensive nature, clear and odorless characteristics, and consistent dissolution properties. Over decades of regulation and scale-up, PVOH has become the default material of choice which virtually all major brands' pod products rely on.
The bio-based as well as novel synthetic polymers are witnessing an exceptionally rapid growth rate, due to increasing attention to the question of biodegradability and environmental impact of the material in spite of its water solubility. Recent commercial breakthroughs with bio-based, marine-degradable films further reinforce this trend compared to the rest of the overall PVOH dominated material composition.
By Thickness, 30–60 micrometer dominates, below 30 micrometer grows fastest
Films in the 30 to 60 micrometer range held the largest share of the thickness segment in 2025, balancing the mechanical strength needed to survive manufacturing, shipping, and handling with dissolution speed that meets consumer expectations for a quick, complete wash-cycle dissolve. That middle-thickness range remains the practical default across the majority of detergent and dishwasher pod applications.
Films below 30 micrometers are growing fastest as manufacturers develop thinner formulations engineered for faster, more complete cold-water dissolution without sacrificing the film integrity a pod needs before it reaches the wash. Rising consumer preference for cold-water washing, driven by energy savings and fabric care concerns, is reinforcing this above-average growth trajectory.
By Application, detergent dominates, dish wash grows fastest
Detergent held the largest application share in 2025, remaining the primary adoption driver for water-soluble pods since laundry detergent pods were the format's original and still highest-volume commercial application. The scale of the global home and laundry care market keeps detergent the dominant application by a wide margin over other water-soluble pod use cases.
Dish wash is the fastest-growing application as dishwasher detergent pods continue gaining share from traditional powder and liquid dishwasher detergent formats, offering the same pre-measured convenience that has already proven successful in laundry care. Rising dishwasher penetration in emerging markets, combined with continued brand investment in dishwasher pod product lines, is reinforcing this above-average growth trajectory.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
79.80% |
|
Europe |
Germany |
25.40% |
|
Asia Pacific |
India |
34.20% |
|
Latin America |
Brazil |
35.10% |
|
Middle East & Africa |
UAE |
29.30% |
North America Water Soluble Pods Packaging Market Insights
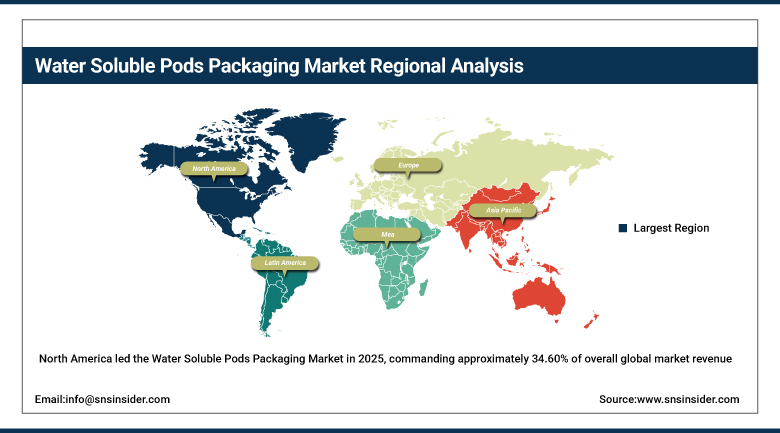
North America led the Water Soluble Pods Packaging Market in 2025, commanding approximately 34.60% of overall global market revenue, anchored by the United States' large, established home and laundry care industry and deep concentration of specialized PVOH film manufacturers. That combination of brand demand and material science expertise, concentrated in a handful of Midwest manufacturing sites, keeps the region at the forefront of both consumption and continued technology development.
Canada contributes a meaningful share through its own consumer goods and home care sector, while Mexico's market continues expanding alongside growing regional consumer products manufacturing investment. Cross-border supply relationships tie much of North American demand together, with major manufacturers typically serving all three markets through shared production networks.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Water Soluble Pods Packaging Market Insights
Asia Pacific is expected to register the fastest regional growth through 2035, driven substantially by government bans on single-use plastics across major markets, including India, that are pushing manufacturers and brand owners toward water-soluble pod formats as a compliant packaging alternative. Rapidly expanding organized retail and rising disposable incomes across the region's largest economies continue reinforcing this accelerating growth trajectory.
India's aggressive single-use plastic restrictions are driving particularly strong regional adoption, while China's expanding consumer goods manufacturing base gives the region substantial additional baseline demand. Japan and South Korea represent more mature, technology-forward markets with established pod manufacturing capability, while Southeast Asian markets continue following a similar regulatory-driven growth trajectory.
Europe Water Soluble Pods Packaging Market Insights
Europe is a matured and regulated water soluble pods packaging market being the regulatory leader on a global level, with packaging waste directive of the European Union, the extended producer responsibility, and Horizon Europe funds all driving bio-based and marine degradable pods. Germany will be at the center of regional demand owing to its significant base of home care manufacturers and consumer goods companies that already have established pod products.
France, Italy, and the UK are also contributing significantly to regional demand due to their presence in the home care and personal care manufacturing space in response to sustainability mandates from the European Union. Regional push toward commercializing bio-based polymer alternatives is keeping Europe ahead of the curve in terms of materials development in the larger global market environment.
MEA & Latin America Water Soluble Pods Packaging Market Insights
The Middle East and Africa represent a smaller but developing water soluble pods packaging market, with the UAE driving demand through growing consumer goods retail investment tied to broader economic diversification goals. Growth elsewhere in the region remains tied closely to the pace of broader home care manufacturing and organized retail infrastructure development.
Latin America is a growing market led by Brazil, where expanding home care and personal care manufacturing continue driving demand for convenient, pre-dosed packaging formats. Mexico and Argentina contribute meaningful secondary demand, tied to their own growing consumer goods manufacturing sectors.
Market Dynamics
Growth Drivers: Sustainability preference and single-use, pre-dosed convenience fueling adoption
Growing consumer and industry shift toward sustainable packaging solutions is one of the clearest forces behind rising water soluble pods packaging demand, as a significant portion of buyers now prefer biodegradable options that reduce plastic waste relative to traditional packaging formats. That preference has positioned water-soluble pods as a leading alternative to conventional plastic packaging across multiple product categories simultaneously.
Rising demand for single-use, pre-dosed consumer products adds a second major driver, as home care, personal care, and food and beverage brands increasingly favor formats that offer precise dosing and mess-free convenience over traditional measuring and pouring. Continued growth of the broader home and laundry care market worldwide continues reinforcing this demand base directly.
Restraints: Material cost premiums and dissolution performance limitations limiting broader adoption
The cost premium of specialized water-soluble film relative to conventional plastic packaging remains a genuine restraint, particularly for price-sensitive product categories and emerging markets where brand owners must weigh sustainability benefits against higher per-unit packaging costs. That cost sensitivity can slow adoption even among brands that recognize the format's genuine environmental and convenience advantages.
Dissolution performance limitations under varied water temperature and hardness conditions add a further restraint, since a pod that doesn't fully dissolve in a given wash cycle undermines the entire value proposition the format is built around. That performance requirement demands continuous material science investment to maintain reliable dissolution across the full range of real-world water conditions consumers actually encounter.
Opportunities: Bio-based material innovation and application diversification opening new growth avenues
Bio-based and marine-degradable polymer innovation offers manufacturers a genuine path to capturing premium business from brand owners chasing credible sustainability commitments beyond what conventional PVOH alone can offer. Companies that successfully commercialize genuine PVOH alternatives are positioned to capture significant new business as regulatory and consumer pressure on plastic-adjacent materials continues building.
Application diversification into personal care, agrochemicals, hospitality, and pharmaceutical unit-dose products represents a second significant opportunity, as the same precision-dosing and convenience benefits that transformed detergent packaging apply directly to these adjacent categories. Manufacturers that build genuine cross-industry application expertise are positioned to capture disproportionate growth as pod technology continues expanding beyond its traditional home care base.
Recent Developments:
-
December 2023: MonoSol expanded its operations by adding a technology center in Chicago's Fulton Market District.
-
August 2025: Aquapak Polymers highlighted growing consumer willingness to pay more for sustainable packaging and partnered with N Brown and Finisterre to replace single-use garment bags with its Hydropol marine-safe polymer.
-
2025: MonoSol introduced new water-soluble film technology extending its PVOH platform into personal care products and cosmetics applications beyond its traditional detergent pod base.
-
2025: Multiple manufacturers, including Mitsubishi Chemical and Sekisui Chemical, continued supplying high-performance PVOH grades engineered specifically for detergent and industrial pod applications requiring resistance to chemically aggressive, high-pH formulations.
Water Soluble Pods Packaging Market Key Players
-
NOBLE INDUSTRIES
-
Aicello Corporation
-
Mitsubishi Chemical Corporation
-
MonoSol, LLC (Kuraray)
-
SEKISUI CHEMICAL CO., LTD.
-
Guangdong Proudly New Material Technology Corp.
-
Aquapak Ltd.
-
Jiangmen Cinch Packaging Materials Co., Ltd.
-
Changzhou Water Soluble Co., Ltd.
-
Fujian Zhongsu Biodegradable Films Co., Ltd.
-
Solupak Ltd.
-
Amtrex Nature Care Pvt. Ltd.
-
Lithey Inc.
-
Mondi Group
-
Kuraray Co., Ltd.
-
Arrow Greentech Limited
-
Cortec Corporation
-
Notpla Ltd.
-
Constantia Flexibles Group GmbH
-
Nitto Boseki Co., Ltd.
Water Soluble Pods Packaging Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 350.0 Million |
| Market Size by 2035 | USD 1,550.0 Million |
| CAGR | CAGR of 16.00% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Type (Multi Chamber Water Pods, Single Layer Water Pods, Dual Layer Water Pods) • by Material (Polyvinyl Alcohol (PVOH), Others) • by Thickness (Below 30 Micrometer, 30–60 Micrometer, Above 60 Micrometer) • by Application (Detergent, Hand Wash, Dish Wash, Others) |
| Regional Analysis/Coverage | North America (US, Canada, Mexico), Europe (Eastern Europe [Poland, Romania, Hungary, Turkey, Rest of Eastern Europe] Western Europe] Germany, France, UK, Italy, Spain, Netherlands, Switzerland, Austria, Rest of Western Europe]), Asia Pacific (China, India, Japan, South Korea, Vietnam, Singapore, Australia, Rest of Asia Pacific), Middle East & Africa (Middle East [UAE, Egypt, Saudi Arabia, Qatar, Rest of Middle East], Africa [Nigeria, South Africa, Rest of Africa], Latin America (Brazil, Argentina, Colombia, Rest of Latin America) |
| Company Profiles | NOBLE INDUSTRIES, Aicello Corporation, Mitsubishi Chemical Corporation, MonoSol, LLC (Kuraray), SEKISUI CHEMICAL CO., LTD., Guangdong Proudly New Material Technology Corp., Aquapak Ltd., Jiangmen Cinch Packaging Materials Co., Ltd., Changzhou Water Soluble Co., Ltd., Fujian Zhongsu Biodegradable Films Co., Ltd., Solupak Ltd., Amtrex Nature Care Pvt. Ltd., Lithey Inc., Mondi Group, Kuraray Co., Ltd., Arrow Greentech Limited, Cortec Corporation, Notpla Ltd., Constantia Flexibles Group GmbH, Nitto Boseki Co., Ltd. |
Frequently Asked Questions
Key players in the Water Soluble Pods Packaging Market include Aicello Corporation, Mitsubishi Chemical Corporation, MonoSol, LLC, SEKISUI CHEMICAL CO., LTD., and Aquapak Ltd., among others.
Key opportunities in the Water Soluble Pods Packaging Market include bio-based and marine-degradable polymer innovation beyond conventional PVOH and application diversification into personal care, agrochemicals, and pharmaceutical unit-dose products.
The market is driven by growing consumer and industry shift toward sustainable packaging solutions, combined with rising demand for single-use, pre-dosed consumer products.
The Detergent segment dominated the Water Soluble Pods Packaging Market, accounting for approximately 58.40% market share.
The North America region dominated the Water Soluble Pods Packaging Market in 2025 with approximately 34.60% share, driven by the United States' large, established home and laundry care industry.
