
Welding Electrodes Market Report Scope & Overview:
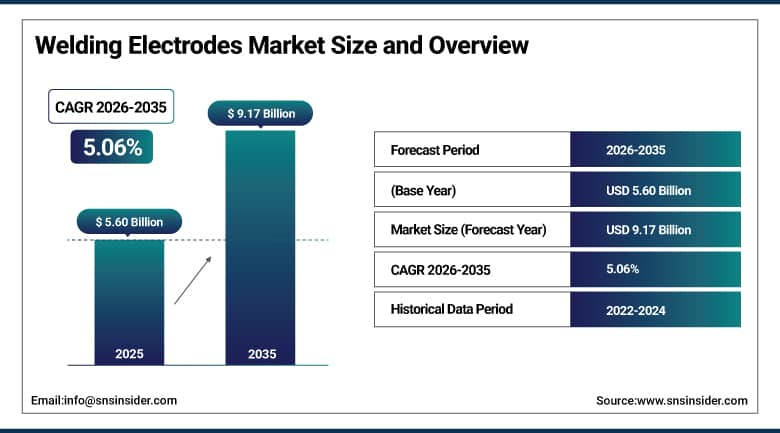
The Welding Electrodes Market was valued at USD 5.60 Billion in 2025 and is expected to reach USD 9.17 Billion by 2035, growing at a CAGR of 5.06% from 2026-2035.
The Welding Electrodes Market is expanding as infrastructure programs, shipyards and energy projects keep arc welding crews busy. Stick electrodes and coiled wires remain the core consumables for structural steel, pressure vessels and pipelines. Demand is anchored in Asia Pacific where fabrication volumes are the largest. Producers are shifting toward low-hydrogen coatings, sealed packaging and low-fume formulations. Nickel and specialty alloy grades are gaining ground in LNG and aerospace work. Semi-automatic processes are taking share from manual welding in factories. Even so, stick products stay essential for field repair, site erection and thick-section joints. New plants in India and the Gulf are reshaping regional supply chains through 2035.
⮞In January 2026, worldsteel reported that world crude steel production totaled 1,849.4 million tonnes in 2025. Output at this scale sustains a vast base of structural fabrication that consumes electrodes in construction, pipelines and heavy equipment.
To Get More Information On Welding Electrodes Market - Request Free Sample Report
Welding Electrodes Market Trends
• Fabrication shops are moving from manual stick work toward semi-automatic and robotic welding cells.
• Low-hydrogen electrodes in hermetically sealed packs are gaining use to control moisture pickup.
• Nickel and specialty alloy consumables are rising with LNG terminals and offshore wind foundations.
• Producers are localizing manufacturing in high-growth regions such as India and Saudi Arabia.
• Low-fume formulations are advancing as stricter workplace exposure limits take hold in Europe.
U.S. Welding Electrodes Market Outlook
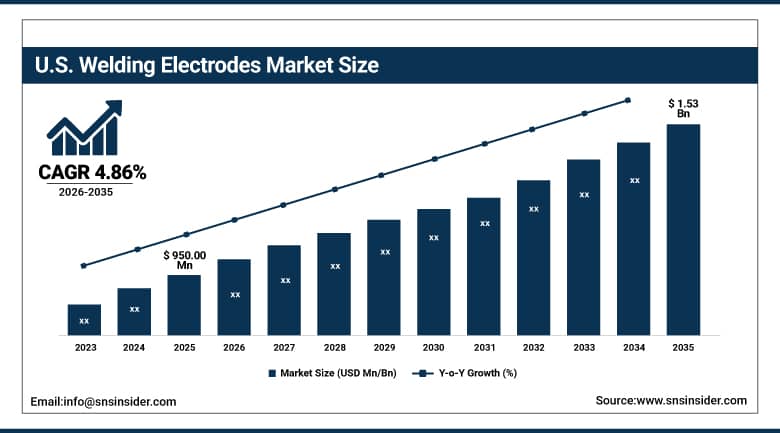
The U.S. Welding Electrodes Market was valued at USD 950.00 Million in 2025 and is expected to reach USD 1.53 Billion by 2035, growing at a CAGR of 4.86% from 2026-2035.
The U.S. Welding Electrodes Market is supported by steady infrastructure spending and a large base of fabrication shops. Highway bridges and port upgrades consume stick electrodes for structural and repair work. LNG export terminals and refinery maintenance add demand for low-hydrogen and nickel alloy grades. The availability of skilled welders shapes the mix of manual and semi-automatic consumables. North America holds 22.30% of global sales and the United States forms the largest part of that total. Buyers favor suppliers with local warehouses and certified low-moisture packaging. Pipeline integrity programs and defense shipbuilding provide recurring orders. Growth through 2035 is expected to be moderate but stable.
⮞In February 2026, the U.S. Census Bureau reported that the value of construction in the United States reached USD 2,164.4 Billion in 2025. Construction activity of this size keeps demand for structural stick electrodes and coiled wires on a firm footing.
Welding Electrodes Market Segment Analysis
-
By Type, the Stick Electrodes segment dominated the Welding Electrodes Market with approximately 37.00% share in 2025, while the Coiled Wires segment is the fastest growing with a CAGR of approximately 5.61%.
-
By Coating, the Rutile segment dominated the Welding Electrodes Market with approximately 43.71% share in 2025, while the Basic (Low-Hydrogen) segment is the fastest growing with a CAGR of approximately 5.67%.
-
By Material, the Mild Steel segment dominated the Welding Electrodes Market with approximately 48.51% share in 2025, while the Nickel and Specialty Alloys segment is the fastest growing with a CAGR of approximately 6.27%.
-
By End Use, the Construction segment dominated the Welding Electrodes Market with approximately 28.88% share in 2025, while the Aerospace and Defense segment is the fastest growing with a CAGR of approximately 6.77%.
By Type, Stick Electrodes Dominates the Welding Electrodes Market and Coiled Wires Grows Fastest
The Stick Electrodes segment dominates the Welding Electrodes Market owing to their versatility, ease of handling, and usage for construction, repair, maintenance, and fabrication purposes. Shielded Metal Arc Welding needs less complicated machinery, which allows for the use of stick electrodes for outdoor welding. Their capability of functioning in different environmental conditions makes them popular among consumers from the infrastructure and industrial segments. Moreover, their availability, limited equipment requirement, and applicability to different grades of steel ensure demand in developed and developing nations.
The Coiled Wires segment is expected to register the fastest growth as manufacturers increase in automation and semi-automation by manufacturers in welding practices. It helps cut back on electrode replacements time and increases deposit rates for big scale fabrications through wire feeding process. Investments in the automotive industry, construction, heavy equipment industry, and shipbuilding industry will fuel the demand for coiled wires for welding purposes. Moreover, robotic welding process implementation, along with cost savings efforts and cycle time savings, are driving manufacturers towards increasing coiled wire applications.
⮞Employment data from the U.S. Bureau of Labor Statistics show that welders, cutters, solderers and brazers held about 437,700 jobs in the United States in 2025. A workforce of this size keeps manual stick welding relevant, while recurring labor constraints push employers toward wire-based processes.
By Coating, Rutile Dominates the Welding Electrodes Market and Basic (Low-Hydrogen) Grows Fastest
The Rutile segment dominates the Welding Electrodes Market owing to their ease of use, stable arc performance, and clean appearance of welds. Electrodes covered in rutile slag usually leave easily removed slag and convenient to handle, hence are ideal for general applications and for maintenance as well as construction. The fact that these can be used in many welding circumstances boosts their usage by industries and fabrication workshops. Availability and suitability in common structural steel applications also help explain their leadership in the market in routine welding processes.
The Basic (Low-Hydrogen) segment is expected to register the fastest growth owing to rising demands for good quality welds in major applications such as infrastructure and industrial applications. They provide protection against hydrogen-induced cracking if used in right storage conditions and proper application according to specified welding procedure. The fact that they work well in structural steel, pressure vessels, pipelines and industrial machinery makes their usage favorable in situations where high-strength weld joint is required.
⮞In March 2025, the U.S. Energy Information Administration stated that the Corpus Christi LNG facility will reach a total nominal capacity of 3.1 Bcf/d once all seven trains are operating. Pressure piping at terminals of this type depends on the low-hydrogen weld joints that basic electrodes deliver.
By Material, Mild Steel Dominates the Welding Electrodes Market and Nickel and Specialty Alloys Grows Fastest
The Mild Steel segment dominates the Welding Electrodes Market owing to the high usage of mild steel in construction, bridges, machines, automobiles, pipeline, and metalwork industries. This is due to the relatively higher weldability and easy availability of the material. Welding consumable for mild steel welding electrodes is readily available in the market and is compatible with various welding methods. Moreover, construction of new structures, production of industrial equipment, and their maintenance creates a huge ongoing demand for mild steel welding electrodes.
The Nickel and Specialty Alloys segment is expected to register the fastest growth since there is a rise in demand for products that can withstand corrosion and high temperature working environments. Nickel alloys are used in various industrial purposes including chemical processing, power generation, aerospace industry, marine equipment, and certain oil and gas applications. Increased development of manufacturing plants and industrial infrastructure is contributing to the rise in demand for specialty joining products. Besides, the need for durable equipment under extreme conditions is driving the demand for specialty alloy welding electrodes.
⮞In February 2026, the International Stainless Steel Forum reported that stainless steel melt shop production reached 64.2 million tonnes in 2025. A larger stainless output widens the base of fabrication work that uses stainless and nickel-bearing electrodes.
By End Use, Construction Dominates the Welding Electrodes Market and Aerospace and Defense Grows Fastest
The Construction segment dominates the Welding Electrodes Market on account of the extensive requirement for welding in the production of structural steel, bridge constructions, building construction, industrial construction and infrastructure projects. There are wide uses of stick electrodes and other consumables for the joining of steel parts in construction, installation and site repairs. The trend of urbanization and modernization of infrastructure and developments in the sectors of transport and industry will continue to drive demand for welding materials. In addition, maintenance of existing construction and construction activity in developing economies will support the consumption of welding products in civil engineering applications.
The Aerospace and Defense segment is expected to register the fastest growth on account of increasing defense procurement and investments in aircrafts, defense equipment manufacturing, spacecraft and advanced engineering and design that will drive demand for specialized joining technology. Parts made of titanium, nickel based super-alloys and other specialized metals need special types of welding technology. In addition, the strict quality requirements and the need for strong and light weight parts in aerospace manufacturing applications will support the use of specialized welding electrodes and consumables.
⮞In February 2026, China's Ministry of Industry and Information Technology reported that national shipyards completed 53.69 million deadweight tons of vessels in 2025. Hull block assembly at this scale consumes large tonnages of electrodes and wires.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
51.37 |
|
North America |
United States |
76.47 |
|
Europe |
Germany |
41.70 |
|
Latin America |
Brazil |
47.52 |
|
Middle East and Africa |
Saudi Arabia |
36.24 |
Asia Pacific Welding Electrodes Market Insights
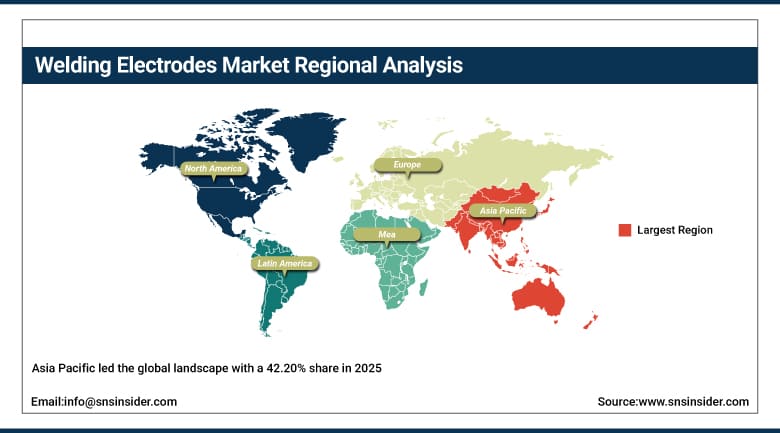
Asia Pacific led the global landscape with a 42.20% share in 2025 because the region hosts the largest steel mills, shipyards and heavy fabrication clusters in the world. China supplies a major part of regional volume through local plants that serve construction machinery, bridges and export vessels. India and Southeast Asia add momentum through highway, metro and refinery programs. Competitive local pricing keeps electrodes affordable for small contractors and allows manual welding to persist longer than in Western markets. Government-backed industrial corridors further concentrate demand.
Producers are investing in flux-cored and gas-shielded wire lines alongside rods to serve automotive and shipbuilding customers. Korean and Japanese groups concentrate on high-strength and low-hydrogen grades for shipyards while Chinese and Indian makers expand volume in mild steel rods. Tighter quality inspection on infrastructure projects is steering buyers toward certified brands. That shift supports premium low-hydrogen sales and rewards suppliers able to document batch consistency. Rising wage costs in coastal China also encourage fabricators to adopt semi-automatic wire processes. Indian producers are adding capacity to supply infrastructure contractors.
⮞In April 2026, OICA reported that Asia-Pacific vehicle production reached around 59.2 million vehicles in 2025. Expanding assembly lines extend demand for wire consumables across the regional automotive supply chain.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Welding Electrodes Market Insights
Pipeline integrity work, bridge rehabilitation and LNG export construction place North America at 22.30% of global sales in 2025. Mature fabricators in the United States and Canada favor certified low-moisture packaging and traceable lot documentation. Canada's heavy equipment and energy sector sustains steady rod and wire consumption alongside American shipyards and refineries. Maintenance welding on aging infrastructure remains a dependable base for stick electrodes. Fabricators also prefer vendor-managed inventory arrangements that keep project sites supplied without storage risk. Hardfacing and repair alloys for mining and quarry equipment contribute additional volume.
A shortage of experienced welders pushes shops toward semi-automatic processes. This moderates stick growth while lifting wire consumption. Defense shipbuilding and nuclear component work add demand for nickel-based and low-alloy grades with strict testing records. Distributors with regional warehouses hold an advantage, since fabricators expect next-day delivery of classified electrodes and rarely accept long lead times on project-critical consumables. Lead-time reliability is therefore a stronger purchase criterion here than in price-driven regions. Welder certification programs run by employers and unions also guide product choices toward well-known classified grades.
⮞In June 2025, the White House issued a proclamation raising tariffs on steel and aluminum imports to 50% under Section 232. Higher metal input costs reshape fabricator sourcing and tilt purchasing toward regionally produced consumables.
Europe Welding Electrodes Market Insights
Energy transition projects and shipbuilding drive specialized orders in Europe, where the market is mature but technically demanding. Germany anchors regional volume through machinery, automotive and steel-structure industries. Offshore wind foundations and hydrogen-ready pipelines require low-hydrogen and nickel grades with documented traceability. Buyers remain loyal to established metallurgical brands, and distributors keep wide stocks of classified electrodes to serve repair shops and contractors. Shipyards building cruise vessels, naval craft and offshore platforms contribute additional high-specification consumption. Italy and France follow Germany as substantial consumers.
Workplace exposure rules are shaping product development, and producers are reformulating alloyed rods for lower fume emissions. Aging industrial plant requires maintenance welding, which sustains the stick segment even as automated cells expand in automotive and rail. Imported rods add price pressure. Certification requirements in regulated work limit their reach, so premium suppliers with approvals for pressure equipment and shipbuilding hold their positions. Training of welders on low-fume practice is spreading through apprenticeships. Trade bodies in several countries maintain approval lists that suppliers must satisfy before bidding.
⮞In June 2026, Eurofer reported that apparent steel consumption in the European Union reached 134.4 million tonnes in 2025. Recovering steel use supports fabrication activity and replacement demand for electrodes.
Latin America and Middle East and Africa Welding Electrodes Market Insights
Latin America relies on Brazil and Mexico for most regional consumption, with mining equipment, automotive plants and pipeline maintenance as the main buyers. Steel output has softened across the region, which keeps contractors price sensitive and favors rutile rods sold through hardware and industrial distributors. Refinery turnarounds and agribusiness infrastructure supply a base of repair welding, and Mexican plants tied to North American manufacturing add demand for wire. Currency swings influence import-based purchasing, so local production and regional distributors carry additional weight. The shift toward nearshored manufacturing in Mexico is expected to broaden wire demand.
⮞In March 2026, Alacero reported that Latin American crude steel production reached 55.5 million tonnes in 2025. Fabricators in the region adjust electrode purchasing to this production level.
Middle East and Africa is projected to expand at a CAGR of 7.07% during 2026-2035, the fastest pace among all regions. Gulf economies are investing in oil, gas, petrochemical and construction capacity, and local manufacturing programs are pulling consumable production closer to project sites. Saudi Arabia leads regional demand, while African mining and power projects add further volume. Pipeline and storage tank construction favors low-hydrogen electrodes with documented qualification. Local content policies in the Gulf encourage international suppliers to establish regional plants, and training centers are being opened to expand the welder workforce.
Market Dynamics
Growth Drivers: Large infrastructure, shipbuilding and energy construction programs are raising the volume of structural welding worldwide.
Public works programs are lifting consumption of arc welding consumables in a measurable way. Bridges, rail corridors, ports and high-rise steel frames are fabricated from plate and sections that must be joined by certified welders. Shipyards in China and South Korea carry long order books that translate into sustained electrode purchases for hull blocks. Pipeline construction for oil, gas and water adds long runs of root and fill passes. These project types specify tonnage-based welding that cannot shift to other joining methods quickly.
Steel capacity expansion in emerging economies widens the customer base further. New mills create downstream fabricators for structures, pressure vessels and equipment, and those shops buy electrodes from the first day of operation. Energy infrastructure ranging from transmission towers to wind towers and refinery revamps extends the list of buyers. Governments link industrial policy to local content, so welding consumables are increasingly sourced near the project site. This combination sustains demand even when global steel output is flat. Rail and metro extensions reinforce this trend.
⮞In October 2025, India's Ministry of Steel stated that the country aims to reach 300 million tonnes of crude steel production capacity by 2030. Capacity growth on this scale supports a broad downstream fabrication base for electrodes.
Restraints: Process substitution toward semi-automatic welding and stricter fume exposure rules are limiting growth in manual stick consumption.
Factories adopt gas-shielded and flux-cored wires because continuous feeding raises deposition rates and cuts rework, and robotic cells accept only spooled consumables. Each conversion removes a block of stick demand that is rarely recovered. Training programs that favor wire processes further reduce the pipeline of stick specialists. A shortage of skilled welders speeds the move since supervisors prefer processes that tolerate less experienced operators. Producers of stick products therefore face flat volumes in mature plants even when overall steel fabrication holds steady.
Cost and quality pressures add to the difficulty. Excess capacity among regional producers erodes prices, counterfeit and unbranded rods undermine trust in certified brands, and low-hydrogen electrodes lose performance if they absorb moisture in storage. Swings in steel, nickel and ferroalloy prices complicate quotations for long contracts. Compliance with fume rules adds reformulation expense, particularly for stainless products. Smaller manufacturers with limited research budgets find these demands hard to meet. Buyers in price-led markets often accept lower grade imitations, which dilutes the premium that quality producers earn.
⮞In January 2025, the European Union directive on carcinogens at work lowered the exposure limit for hexavalent chromium in welding fumes to 0.005 mg/m3. Stainless electrode makers must reformulate or invest in fume control to keep serving regulated European customers.
Opportunities: Offshore wind, LNG and local manufacturing in fast-growing regions are opening new volume for specialty and low-hydrogen electrodes.
Wind and LNG construction create demand for thick-section and cryogenic welds. Tower sections, monopile foundations and nacelle frames require high-deposition consumables with strict toughness values, while LNG tanks and process piping call for nickel alloy electrodes. Suppliers holding approved procedures and technical support capture long-term contracts. Metal-cored wires attract fabricators seeking higher productivity than solid wire delivers, and they open a path for rod producers that can broaden their ranges. Early engagement with project engineers is decisive, since procedures are fixed long before steel is cut.
Local manufacturing in the Gulf and South Asia gives producers a way to shorten lead times, avoid import friction and meet local content rules. Bundled offers that pair welding equipment with consumables strengthen account loyalty and raise switching costs. Aluminum and advanced high-strength steel wires for electric vehicle platforms provide a further outlet for suppliers with research capability. Welder training delivered together with certified products extends the relationship from supply to service. Expanding repair and refurbishment of wind turbines also creates a service market.
⮞In May 2026, the Global Wind Energy Council reported that a record 178 gigawatts of wind turbine capacity was mechanically installed worldwide in 2025. Towers and foundations at this volume require heavy thick-section welding with high-deposition consumables.
Recent Developments:
-
August 2025, ESAB opened a new manufacturing facility in Al Ahsa, Saudi Arabia. The 6,028 square meter plant employs about 40 full-time associates and produces premium performance filler metals. The site brings supply closer to Gulf energy and infrastructure customers and shortens delivery times.
-
March 2026, Ador Welding announced a strategic collaboration with ITW Welding India covering Miller key products. The tie-up links a consumables network with welding equipment. It supports bundled offers to Indian fabricators and raises switching costs for buyers of both equipment and electrodes.
-
March 2025, voestalpine Böhler Welding developed a tailored welding wire with Linde Engineering for ammonia tanks. Ammonia handling is growing with fertilizer and hydrogen projects, so qualified consumables of this type open demand in energy transition fabrication.
-
November 2025, Hyundai Welding inaugurated a new welding consumables facility in Ponneri near Chennai, its first production unit in India. The plant makes flux-cored and gas metal arc wires for the Indian market and signals the rising weight of wire products in regional supply.
Welding Electrodes Market Key Players
• Lincoln Electric
• ESAB
• Hobart Brothers (ITW)
• voestalpine Böhler Welding
• Hyundai Welding
• Tianjin Bridge
• Kiswel
• Ador Welding
• D&H Secheron
• Royal Arc Electrodes
• Special Metals Welding Products
• Castolin Eutectic
• Nippon Steel Welding and Engineering
• Kobe Steel
Welding Electrodes Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 5.60 Billion |
| Market Size by 2035 | USD 9.17 Billion |
| CAGR | CAGR of 5.06% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (Stick Electrodes, Coiled Wires, Bare Electrodes, Flux-Cored Wires, and Others) • By Coating (Rutile, Basic (Low-Hydrogen), Cellulosic, Iron Oxide, Metal Powder, and Others) • By Material (Mild Steel, Stainless Steel, Cast Iron, Aluminum and Alloys, and Nickel and Specialty Alloys) • By End Use (Construction, Automotive, Aerospace and Defense, Shipbuilding, Energy and Power, Electronics, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Lincoln Electric, ESAB, Hobart Brothers (ITW), voestalpine Böhler Welding, Hyundai Welding, Tianjin Bridge, Kiswel, Ador Welding, D&H Secheron, Royal Arc Electrodes, Special Metals Welding Products, Castolin Eutectic, Nippon Steel Welding and Engineering, Kobe Steel |

Frequently Asked Questions
Lincoln Electric, ESAB, Hobart Brothers (ITW), voestalpine Böhler Welding and Kobe Steel are some of the key players in the Welding Electrodes Market, among others.
Offshore wind, LNG terminals and aerospace programs are opening demand for nickel alloy and low-hydrogen electrodes.
Large infrastructure, shipbuilding and energy construction programs are the major growth factor, as each project consumes substantial tonnages of certified electrodes and wires.
The Stick Electrodes segment dominated the Welding Electrodes Market with approximately 37.00% share in 2025 because rods work outdoors in all positions with low equipment cost.
Asia Pacific dominated the Welding Electrodes Market with approximately 42.20% share in 2025, owing to the concentration of steel mills, shipyards and construction activity in China, India and Southeast Asia.
