
Zoom Lens Market Report Scope & Overview:
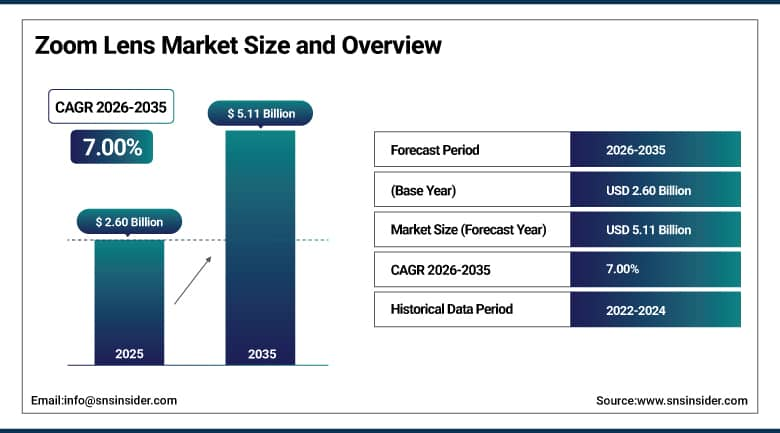
The Zoom Lens Market size was valued at USD 2.60 Billion in 2025 and is expected to reach USD 5.11 Billion by 2035, growing at a CAGR of 7.00% from 2026-2035.
The Zoom Lens Market covers lenses with a variable focal length, used in interchangeable-lens cameras, cinema cameras, surveillance and machine vision systems, medical imaging devices and vehicles. Buyers choose zoom lenses for flexibility, since one lens replaces several fixed focal lengths, and manufacturers compete on aperture, autofocus speed, stabilization, weight and price. Mirrorless camera adoption is the main driver for photography, while security, automotive and industrial users add demand for motorized and varifocal designs. Sensor makers and lens makers are moving toward lighter optics and third-party mounts, so independent brands now supply a rising share of lenses for Sony, Canon, Nikon and Fujifilm bodies.
⮞On October 14, 2026, Tamron announced the 16-50mm F2.8 A for APS-C mirrorless cameras in Sony E, Canon RF, Nikon Z and Fujifilm X mounts. The lens weighs about 305 g, uses a VXD linear autofocus motor and has a 55 mm filter size, with recommended prices of EUR 449 to EUR 499 depending on mount. Sony E and Canon RF versions ship at the end of October, Nikon Z in November and Fujifilm X in December. The multi-mount release shows how third-party makers now launch across all major systems at once.
To Get More Information On Zoom Lens Market - Request Free Sample Report
Zoom Lens Market Trends
-
Rising share of third-party zoom lenses across Sony, Canon, Nikon and Fujifilm mounts
-
Growth of lightweight constant-aperture zooms for APS-C mirrorless cameras
-
Adoption of linear autofocus motors and optical stabilization in compact zooms
-
Use of motorized and varifocal zoom lenses in surveillance and machine vision
-
Demand for zooms with cinema-grade optics from video creators and streamers
-
Wider use of aspherical elements and coatings to cut size and aberrations
U.S. Zoom Lens Market Size Outlook
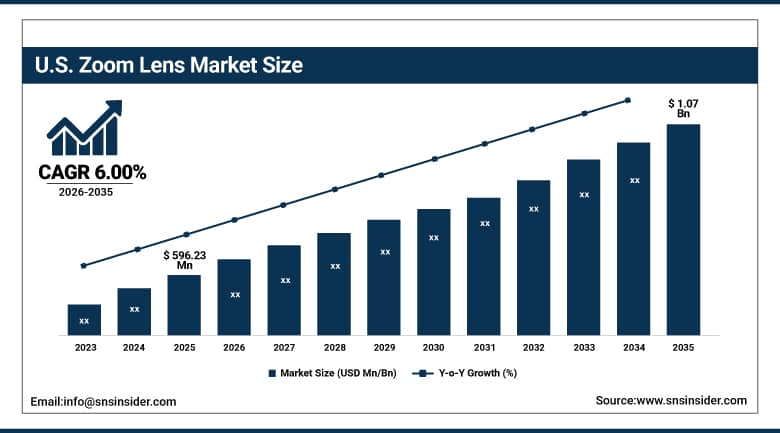
The U.S. Zoom Lens Market was valued at USD 596.23 Million in 2025 and is expected to reach USD 1.07 Billion by 2035, growing at a CAGR of 6.00% from 2026-2035.
The U.S. Zoom Lens Market is the largest national market in North America, supported by a large base of enthusiast and professional photographers, a deep content creation economy, a strong sports and wildlife photography culture and sizeable security and defense camera spending. Nearly all lenses are imported, mainly from Japan, China, Thailand and Taiwan, so pricing follows exchange rates and tariffs. Camera retailers, online marketplaces and rental houses shape purchases, and the used lens market is active. Independent brands have gained share by offering lower prices and wide mount support, while Canon, Nikon and Sony remain strongest in premium lenses.
⮞On October 8, 2026, Sigma announced the 50-120mm F2.8 DC OS Contemporary, a compact telephoto zoom for APS-C cameras, with an RF-mount version reported for Canon users. The same day the company announced its 16-300mm F3.5-6.7 DC OS Contemporary for Nikon Z mount, following the 20-60mm F2.8-4 DG Contemporary for full-frame mirrorless cameras on September 8. The releases target U.S. photographers who want a long-range zoom without moving to heavier full-frame systems.
Zoom Lens Market Segment Analysis
-
By Type, the Standard Zoom segment dominated the Zoom Lens Market with approximately 41.50% share in 2025, while the Telephoto Zoom segment is the fastest growing with a CAGR of approximately 8.10%.
-
By Optical Design, the Aspherical segment dominated the Zoom Lens Market with approximately 58.00% share in 2025, while the Hybrid segment is the fastest growing with a CAGR of approximately 9.00%.
-
By Application, the Photography segment dominated the Zoom Lens Market with approximately 46.00% share in 2025, while the Automotive segment is the fastest growing with a CAGR of approximately 10.40%.
-
By Sensor Format, the Full-Frame segment dominated the Zoom Lens Market with approximately 47.00% share in 2025, while the APS-C and Crop Sensor segment is the fastest growing with a CAGR of approximately 8.80%.
-
By End-User, the Individual Consumers segment dominated the Zoom Lens Market with approximately 39.00% share in 2025, while the Security Agencies segment is the fastest growing with a CAGR of approximately 9.10%.
By Type, Standard Zoom Dominates the Zoom Lens Market and Telephoto Zoom Grows Fastest
Standard zooms lead because they cover the most used focal lengths, typically from wide-angle to short telephoto, and are bundled with most camera bodies as kit lenses. A 24-70mm or 18-55mm style lens serves events, travel, portraits and video, which makes it the first purchase for new owners and a staple for professionals. Brands compete here on constant apertures, size and price, and launches such as Tamron's 16-50mm F2.8 A and 17-70mm F2.8 target this segment with compact designs.
Telephoto zooms are growing fastest because sports, wildlife, aviation and video creators want reach in lighter packages. Better stabilization, faster autofocus motors and new designs such as Sigma's 50-120mm F2.8 for APS-C make long zooms easier to carry. Mirrorless systems also track moving subjects better, which increases demand for telephoto lenses. Sales start from a smaller base than standard zooms and typically carry higher prices, which supports faster value growth through 2035.
By Optical Design, Aspherical Dominates the Zoom Lens Market and Hybrid Grows Fastest
The Aspherical segment leads the Zoom Lens Market owing to its capability to mitigate optical aberrations, produce clear images, and provide excellent optical performance irrespective of the different focal lengths. Aspheric lenses make it possible to limit spherical aberration and distortion while at the same time ensuring the production of portable and light weight zoom lenses with no impact on image quality. This is attributed to the rising use of aspheric lenses in professional photography, cinematography, surveillance, and advanced imaging technologies. Most camera and optics companies tend to integrate aspheric lenses in their premium and mid-range zoom lenses in order to enhance imaging efficiency.
The Hybrid Optical Design category in the Zoom Lens Market is forecasted to exhibit the highest growth rate owing to rising requirements for compact, light-weight, and cost-effective optical devices that ensure excellent imaging. Hybrid optical designs make use of a combination of optical materials or technologies of optical elements, including glass molded optics and aspherical lenses made from polymers, to enhance optical performance and manufacturing efficiencies. Increasing use of hybrid lenses in surveillance cameras, imaging modules in automobiles, industrial inspection equipment, and consumer electronics drives the market forward. Advancements in precision molding, optical coating, and manufacturing technology are boosting the durability and performance of hybrid lens modules.
By Application, Photography Dominates the Zoom Lens Market and Automotive Grows Fastest
Photography takes the lead because the majority of zoom lenses are consumed by interchangeable lens cameras, and many professionals have more than one lens in their possession. According to CIPA statistics, in 2025, Japan-based producers shipped 10.6 million interchangeable lenses, an increase from the 10.3 million lenses shipped in 2024. This is so because most of them are zoom lenses that are suitable for travel, sports, and video shooting.
Automotive is growing fastest from a smaller base as vehicles add cameras for driver monitoring, surround view and advanced driver assistance. Most use fixed lenses, but zoom and varifocal optics appear in forward-facing and in-cabin systems that need flexible fields of view, as well as in inspection and testing equipment. Higher camera counts per vehicle and demand for reliable lenses in wide temperature ranges support growth. Automotive suppliers are partnering with lens makers on designs that meet strict quality and durability standards.
By Sensor Format, Full-Frame Dominates the Zoom Lens Market and APS-C and Crop Sensor Grows Fastest
Full-frame lenses lead in value because they are larger, use more glass and sell at higher prices, with professional zooms such as 24-70mm F2.8 and 70-200mm F2.8 costing well above crop-sensor equivalents. Professionals, wedding and sports photographers and serious enthusiasts favor full-frame bodies, and mirrorless adoption has refreshed full-frame lens lineups. Manufacturers launch top-end zooms with constant apertures, which supports revenue even when unit volumes are lower than crop-sensor lenses.
APS-C and crop-sensor lenses are growing fastest as lower body prices and portable designs attract new buyers. CIPA data showed crop-sensor lens shipments rising in 2025 while full-frame shipments fell, partly because of weaker demand in China. Independent brands have responded with F2.8 zooms for Sony E, Canon RF, Nikon Z and Fujifilm X crop cameras, including Tamron's 16-50mm and Sigma's 50-120mm. Open mounts and lower prices should keep this segment growing faster than the market.
By End-User, Individual Consumers Dominates the Zoom Lens Market and Security Agencies Grows Fastest
Individual consumers take the lead since the biggest segment in terms of buyers of cameras and lenses includes hobbyists, tourists, families, and social media makers. The segment prefers flexible zooms as they replace multiple lenses, and they are motivated by prices, weights, and autofocus capabilities. The kits available online and in stores make zooms easily accessible to buy, while rentals and second-hand sales widen the availability of these products. Consumers are cyclical and dependent on the release of cameras and economic situation.
Security agencies are growing fastest as governments and private operators expand surveillance of cities, borders, transport hubs and critical infrastructure. These users buy motorized and varifocal zoom lenses for pan-tilt-zoom cameras that need to identify subjects at long range, often with infrared correction for night use. Higher camera resolution and artificial intelligence analytics require sharper optics, which raises the value of each lens. Public safety budgets and smart city programs in Asia Pacific and the Middle East add particular momentum.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
Japan |
31.50 |
|
North America |
United States |
78.00 |
|
Europe |
Germany |
27.40 |
|
Middle East & Africa |
United Arab Emirates |
32.60 |
|
Latin America |
Brazil |
48.50 |
Asia Pacific Zoom Lens Market Insights
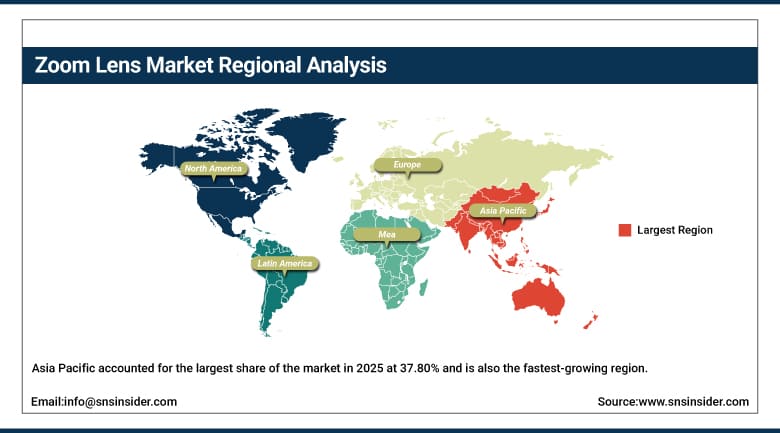
Asia Pacific accounted for the largest share of the market in 2025 at 37.80% and is also the fastest-growing region, advancing at a CAGR of 8.20% through 2035. Japan hosts Canon, Nikon, Sony, Fujifilm, Tamron, Sigma, Panasonic and OM Digital, and China, Thailand and Taiwan supply manufacturing and assembly. China and India add large consumer and security demand.
The region combines design leadership with production scale, and CIPA reports that Japanese makers shipped 10.6 million interchangeable lenses in 2025. Chinese brands such as Viltrox and TTArtisan are expanding quickly with low-priced mirrorless zooms. Weaker full-frame demand in China in 2025 shows sensitivity to consumer spending, but video creation, surveillance and smart city projects support long-term growth.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Zoom Lens Market Insights
North America held 29.40% of the market in 2025 and is growing at a CAGR of 6.30% through 2035. The United States accounts for most regional value, with a large base of photographers, professional studios and sports and news organizations. Canada contributes through wildlife and outdoor photography and a growing creator community.
Nearly all lenses are imported, so tariffs and exchange rates influence retail prices. Sigma, Tamron and other independent brands compete strongly through online retailers, while Canon, Nikon and Sony lead in professional channels. Rental companies and a large used market extend product life, which moderates new-unit growth but keeps demand for new designs high.
Europe Zoom Lens Market Insights
Europe held 22.00% of the market in 2025 and is growing at a CAGR of 6.20% through 2035. Germany, the United Kingdom, France and Italy lead through professional photography, a strong cinema industry and industrial imaging. European optical specialists such as Carl Zeiss, Schneider Kreuznach, Leica and Angénieux supply high-end photo, cinema and industrial zooms.
Tamron's 16-50mm F2.8 A was priced from EUR 449 at launch, showing intense competition for crop-sensor buyers. Regulation on product safety and sustainability shapes materials and packaging, and demand growth is moderate because of mature camera ownership, but cinema and machine vision applications support steady expansion.
MEA & Latin America Zoom Lens Market Insights
The Middle East and Africa held 5.60% of the market and is growing at a CAGR of 7.40%. The United Arab Emirates and Saudi Arabia lead through security infrastructure, tourism, media and smart city projects, with South Africa and Egypt adding demand from photography and broadcast. Most products are imported through regional distributors.
Latin America held 5.20% of the market and is growing at a CAGR of 6.80%. Brazil and Mexico lead through consumer photography, events and growing creator communities, with Argentina, Chile and Colombia contributing smaller volumes. Import duties and currency swings raise prices and limit premium lens sales, but demand for affordable independent zooms and security cameras supports growth.
Market Dynamics
Growth Drivers: Mirrorless Adoption, Creator Economy and Security Camera Upgrades
Mirrorless camera adoption is the main driver. Brands have shifted lens development to mirrorless mounts, and owners buy new zooms to match faster autofocus, stabilization and video features. Each new mount generation triggers replacement purchases, and lens sales per body are rising among enthusiasts who want constant-aperture zooms. Manufacturers keep releasing new designs, including multiple releases from Sigma and Tamron in 2026, which keeps the upgrade cycle active.
The creator economy and security upgrades add momentum. Video creators, streamers and vloggers need versatile lenses that handle photo and video, while cities and businesses install higher-resolution cameras with motorized zoom optics. Open mounts allow independent makers to serve many camera brands, widening the addressable market. Together these buyers support stable volume growth across consumer, professional and commercial segments.
Restraints: Smartphone Cameras, Tariffs and Mature Camera Ownership
Smartphone cameras restrain growth by satisfying casual photographers with multi-lens modules and computational zoom. This reduces entry-level camera sales and therefore kit zoom sales, and younger consumers may never buy a dedicated camera. Lens makers respond by emphasizing image quality and creative control, but the casual segment remains under pressure.
Both tariffs and ownership contribute to the risks. Lenses are manufactured in Asia and marketed in North America and Europe, so tariffs and currency fluctuations influence the final price of the product and the demand for it. Lens collections owned by photographers and second-hand market presence increase replacement intervals. Poor demand for full frame cameras in China in 2025, according to CIPA figures, is an example of changing sentiments.
Opportunities: APS-C Zooms, Automotive Optics and Third-Party Mount Support
APS-C zooms offer a significant opportunity, as crop-sensor lens shipments rose in 2025 while full-frame shipments dipped. Compact F2.8 zooms from Tamron and Sigma priced from about EUR 449 to USD 749 appeal to buyers who want performance without full-frame cost. Launches across Sony E, Canon RF, Nikon Z and Fujifilm X at once widen reach and reduce development cost per mount.
Automotive optics and third-party mount support provide further opportunities. Cars need more cameras for driver monitoring and assistance, and lens makers with high-volume precision molding can supply them. Meanwhile, broader access to Canon RF and Nikon Z mounts lets independent firms sell to larger customer bases. Companies that combine optical quality, light weight and competitive prices should gain share.
Recent Developments:
-
2026: Sigma announced the 20-60mm F2.8-4 DG Contemporary, a standard zoom for full-frame mirrorless cameras.
-
2026: Tamron announced the 17-70mm F2.8 Di III-A VC RXD for Canon RF and Nikon Z mounts at USD 749, available from July 2, 2026.
-
2026: Tamron's financial report indicated plans to launch 10 new lenses during the year, while CIPA data showed Japanese makers shipped 10.6 million interchangeable lenses in 2025.
Zoom Lens Companies are
-
Canon Inc.
-
Sony Group Corporation
-
FUJIFILM Holdings Corporation
-
OM Digital Solutions Corporation
-
Panasonic Holdings Corporation
-
Sigma Corporation
-
Carl Zeiss AG
-
HOYA Corporation (PENTAX)
-
Schneider Kreuznach
-
Kenko Tokina Co., Ltd.
-
Leica Camera AG
-
Cooke Optics Limited
-
ARRI AG
-
Angénieux (Thales Group)
-
Samyang Optics Co., Ltd.
-
Shenzhen Viltrox Technology Co., Ltd.
-
Venus Optics (Laowa)
-
Computar (CBC Co., Ltd.)
Zoom Lens Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 2.60 Billion |
| Market Size by 2035 | USD 5.11 Billion |
| CAGR | CAGR of 7.00% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | Agencies, Healthcare Providers, and Others), • By Type (Standard Zoom, Wide-Angle Zoom, Telephoto Zoom, Macro Zoom, Others) • By Optical Design (Spherical, Aspherical, Hybrid Optical Design, Others) • By Application (Photography, Surveillance and Security, Cinematography, Medical Imaging, Industrial Inspection, Automotive, Others) • By Sensor Format (Full-Frame, APS-C and Crop Sensor, Micro Four Thirds, Others) • By End-User (Individual Consumers, Professional Photographers and Filmmakers, Security Agencies, Healthcare Providers, Others |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Canon Inc., Nikon Corporation, Sony Group Corporation, FUJIFILM Holdings Corporation, OM Digital Solutions Corporation, Panasonic Holdings Corporation, Tamron Co., Ltd., Sigma Corporation, Carl Zeiss AG, HOYA Corporation (PENTAX), Schneider Kreuznach, Kenko Tokina Co., Ltd., Leica Camera AG, Cooke Optics Limited, ARRI AG, Angénieux (Thales Group), Samyang Optics Co., Ltd., Shenzhen Viltrox Technology Co., Ltd., Venus Optics (Laowa), Computar (CBC Co., Ltd.) |

Frequently Asked Questions
Key players include Canon, Nikon, Sony, Fujifilm, OM Digital, Panasonic, Tamron, Sigma, Carl Zeiss, HOYA, Schneider Kreuznach, Kenko Tokina, Leica, Cooke Optics, ARRI, Angénieux, Samyang, Viltrox and Laowa.
Key opportunities include compact APS-C F2.8 zooms, automotive and machine vision optics, and multi-mount launches by independent makers across Sony, Canon, Nikon and Fujifilm systems.
The major growth factor is mirrorless camera adoption, which drives replacement of lenses, along with demand from video creators and security camera upgrades.
By Type, the Standard Zoom segment dominated the market with approximately 41.50% share in 2025, owing to its coverage of the most used focal lengths and its role as a kit lens.
Asia Pacific dominated the market with a share of 37.80% in 2025, supported by Japanese camera and lens makers, regional manufacturing and large consumer and security demand.
