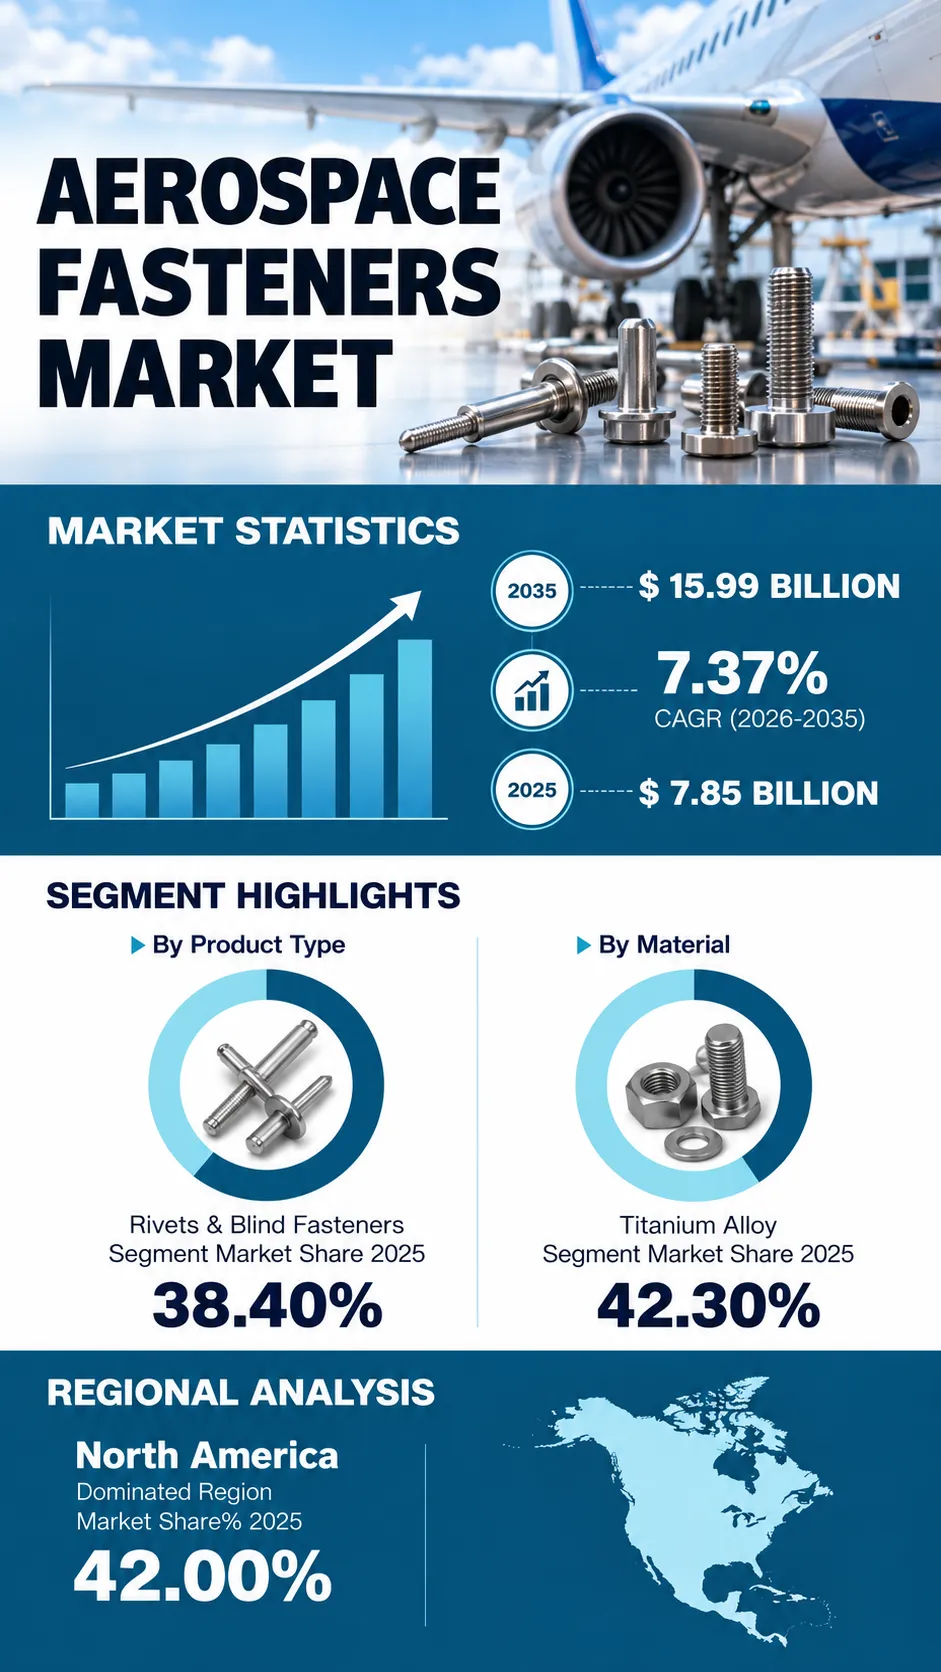
The global Aerospace Fasteners Market is set for significant expansion as rising aircraft production and defense modernization continue to reshape aerospace hardware procurement worldwide. “According to a recent study by SNS Insider, the global Aerospace Fasteners Market size valued at USD 7.85 billion in 2025, is anticipated to grow to USD 15.99 billion by 2035, registering a CAGR of 7.37% over the 2026–2035 forecast period.”
There have been notable changes within aerospace fastening technology over time, due to which many manufacturers who aim at improving strength and lightweight performance can take advantage of this trend. This includes the need for more advanced titanium and composite-compatible materials that will provide aircraft OEMs with the ability to reduce structural weight while maintaining stringent safety standards. This applies in situations where aerospace fasteners support commercial aircraft, military aircraft, and emerging eVTOL and space launch applications. Manufacturers are constantly working hard to ensure that their fastening solutions perform better than before in order to meet various structural integrity and weight reduction requirements.
To Get Detailed Insights on the Aerospace Fasteners Market – Request a Sample Report
Composite-Compatible and Cryogenic-Rated Fasteners Create New Demand
The aerospace fasteners market has evolved from conventional metal fastening hardware to increasingly specialized, application-specific fastening solutions. The growing investment in composite-compatible polymer materials, cryogenic-rated fastener development, and embrittlement-resistant hydrogen aircraft solutions across manufacturers of all sizes has required the development of more advanced and versatile fastening products.
New material and manufacturing technologies can increase strength-to-weight performance, improve corrosion and temperature resistance, and allow for expansion into increasingly diverse commercial, defense, eVTOL, and space launch applications. This gives aircraft OEMs and MRO providers the possibility to reduce structural weight while maintaining the stringent safety standards required across the industry.
Fastener manufacturers, aircraft OEMs, and MRO providers are increasingly cooperating thanks to the growing interest in developing future solutions for lightweight, high-performance aerospace fastening technology.
Key Market Findings Highlight High-Growth Segments
The rivets and blind fasteners segment dominated all categories in the aerospace fasteners market share with a 38.40% share due to extensive use joining sheet metal components across fuselage, wings, and control surfaces. The fastest growing category is expected to be screws which will grow at a CAGR of 8.20% through 2035, owing to growing demand for removable, precision-torqued fastening solutions.
By material, titanium alloy accounted for 42.30% of market share due to superior strength-to-weight ratio and corrosion resistance. Composite-compatible polymer fasteners will see the fastest growth in revenue generation at a 9.60% CAGR, driven by rising CFRP content in next-generation and eVTOL aircraft.
Based on application, commercial aviation generated 55.90% of market revenue thanks to sustained record order backlogs at Boeing and Airbus. On the other hand, military aircraft will be the segment recording the fastest revenue growth at an 8.70% CAGR, supported by sixth-generation fighter and advanced trainer programs.
Distributive end-use trends are changing as well. OEM procurement accounted for the largest revenue share owing to sustained new aircraft production. But aftermarket and MRO will turn out to be the fastest-growing end-use category through 2035, on the back of robust maintenance, repair, and overhaul demand supporting replacement and upgrade activity.
Weight Reduction, Corrosion Resistance, and Application Diversity Gain Importance
In this regard, aircraft OEMs and MRO providers have been looking at fastener products that would deliver more consistent structural performance while requiring less weight and offering greater corrosion and temperature resistance.
Innovation in titanium alloy processing, composite-compatible polymer development, and cryogenic-rated material science has been making it possible for companies to come up with products that can operate effectively across increasingly demanding commercial, defense, and emerging aviation applications. In addition to that, increasing emphasis on eVTOL and space launch application development is also making it possible for manufacturers to find solutions that support the industry's ongoing diversification beyond traditional aviation. Such trends are likely to become even more prominent in the future.
North America Emerges as the Largest Market with 42% Regional Revenue Share Amid Record Order Backlogs
The North America region represented the largest share of regional market revenue in 2025 at 42%, driven by record single-aisle jet backlogs and robust defense modernization investment. On the other hand, Asia-Pacific is set to grow the fastest at a 9.70% CAGR during the forecast period through 2035, propelled by BRICS-focused expansion in commercial and defense aircraft manufacturing.
Leading Companies Drive Innovation and Competition
The environment continues to stay very dynamic since players continue innovating on titanium processing and composite-compatible materials as well as forming partnerships in order to enhance their position in the industry. Some of the major companies that operate in the global aerospace fasteners market are Howmet Aerospace, Precision Castparts Corp, LISI Aerospace, Stanley Black & Decker, TriMas Corporation, National Aerospace Fasteners Corporation, B&B Specialties, SAT Aerospace, Arconic Corporation, and TFI Aerospace Corporation.
An SNS Insider analyst Santosh Bhul commented, "The growing convergence of record commercial aircraft backlogs and emerging eVTOL and space launch activity is creating unprecedented demand for advanced, lightweight fastening technology. Manufacturers that successfully combine titanium processing innovation, composite-compatible material development, and application-specific expertise will be best positioned to capitalize on emerging opportunities across commercial, military, and next-generation aviation segments."
About the Author

Get in touch