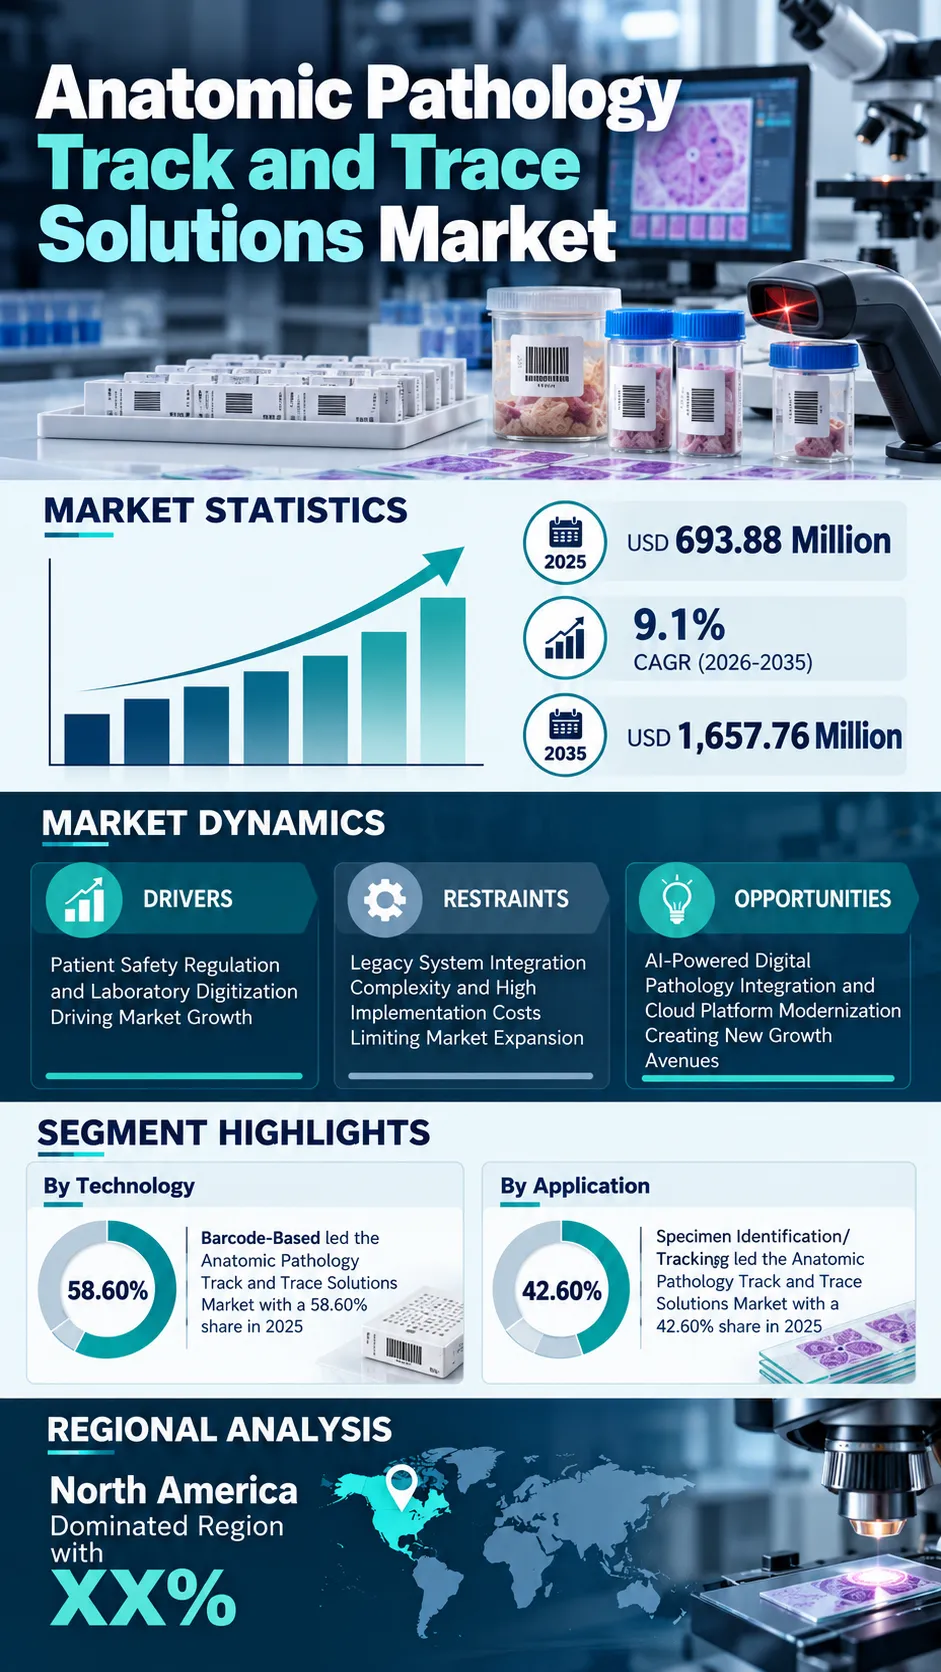
The global Anatomic Pathology Track and Trace Solutions Market is set for steady expansion as laboratories worldwide continue modernizing specimen traceability infrastructure. "According to a recent study by SNS Insider, the global Anatomic Pathology Track and Trace Solutions Market size valued at USD 693.88 million in 2025, is anticipated to grow to USD 1,657.76 million by 2035, registering a CAGR of 9.1% over the 2026-2035 forecast period."
There have been tremendous changes within laboratory informatics platform architecture over time due to which many vendors who aim at improving specimen traceability can take advantage of this trend. This includes the need for more unified, cloud-native systems that will provide laboratories with the ability to eliminate pre-analytical errors. This applies in situations where anatomic pathology track and trace solutions are used across hospital laboratories, independent reference laboratories, and academic medical centers.
Vendors are constantly working hard to ensure that their track and trace systems perform better than before in order to meet various needs of pathology laboratories worldwide.
To Get Detailed Insights on This Market – Request a Sample Report
Specimen Traceability Ecosystems Create New Demand
The anatomic pathology track and trace solutions market has evolved from basic barcode identification to more advanced RFID and AI-integrated digital pathology use cases. The growing investment in cloud-native platform consolidation, hybrid hardware-software bundling, and digital pathology scanner integration for a variety of applications has required the development of more efficient and reliable tracking systems.
New designs of track and trace solutions can increase identification accuracy, reduce specimen errors, and allow for broader multi-site laboratory network scalability. This gives vendors the possibility to be more effective when serving hospital and reference laboratories and doing better regulatory compliance support.
Laboratory informatics vendors, hospital systems, and independent reference laboratories are increasingly cooperating thanks to the growing interest in developing future solutions for specimen traceability and patient safety.
Key Market Findings Highlight High-Growth Segments
The barcode-based segment dominated all categories in the anatomic pathology track and trace solutions market share with a market revenue share of 58.60% in 2025 due to its established, cost-effective specimen identification foundation.
The fastest growing category is expected to be RFID-based solutions which will grow at a CAGR of 10.80% through 2035. This will be possible owing to the increasing demand for contactless, batch-readable specimen identification.
By application, specimen identification and tracking held the largest share of total market revenue of 42.60% in 2025 due to its foundational role in chain of custody management. The slide tracking segment will see the fastest growth in revenue generation at a CAGR of 10.60%.
Based on end user, hospital laboratories generated a share of 44.60% of market revenue in 2025 thanks to extensive infrastructure and established informatics adoption. On the other hand, independent and reference laboratories will be the segment recording the fastest revenue growth at a CAGR of 10.90%.
Distributive trends are changing as well. Software solutions accounted for a 48.00% revenue share in 2025. But hardware will turn out to be the fastest-growing product category through 2035, on the back of new laboratory digitization initiatives requiring physical identification infrastructure.
Traceability, Compliance, and Digital Integration Gain Importance
In this regard, laboratories have been looking at track and trace systems that would make their specimen management more traceable and require less identification error risk and be more digitally integrated.
Innovation in cloud-native platform architecture, RFID technology, and AI-powered digital pathology integration has been making it possible for companies to come up with systems that can meet increasingly demanding regulatory and patient safety expectations. In addition to that, increasing emphasis on multi-site network scalability and workflow automation is also making it possible for companies to find solutions that optimize laboratory efficiency.
Such trends are likely to become even more prominent in the future.
North America Emerges as the Largest Market Amid Rising Digitization Demand
The North America region represented the largest regional market in 2025, owing to advanced healthcare infrastructure and the increasing need for digitization and specimen traceability across over 9,500 pathology labs in the region. In addition, Asia Pacific is expected to be the fastest-growing market during the forecast period, propelled by increasing healthcare investments and diagnostic chain expansion across the region's fast-growing laboratory digitization industries.
On the other hand, Europe represented a meaningful share of global market revenue in 2025, aided by hospital laboratory digital integration and strong regulatory frameworks governing laboratory accreditation.
Leading Companies Drive Innovation and Competition
The environment continues to stay very dynamic since players continue innovating on products and platforms as well as forming partnerships in order to enhance their position in the industry.
Some of the major companies that operate in the global anatomic pathology track and trace solutions market are Clinisys Inc., CompuGroup Medical SE & Co. KGaA, Computype Inc., Zebra Technologies Corporation, XiFin Inc., LigoLab Information Systems LLC, NovoPath Inc., Sakura Finetek USA Inc., Leica Biosystems Nussloch GmbH, and Roper Technologies Inc.
An SNS Insider Analyst Parry Kardani commented, "The rapid consolidation of laboratory informatics platforms onto unified, cloud-native architectures is creating unprecedented demand for high-reliability specimen traceability solutions. Vendors that successfully combine platform consolidation, AI-powered digital pathology integration, multi-site scalability, and advanced identification technology will be best positioned to capitalize on emerging opportunities across hospital, reference, and academic laboratory applications."
About the Author
Get in touch