
Anatomic Pathology Track and Trace Solutions Market Report Scope & Overview:
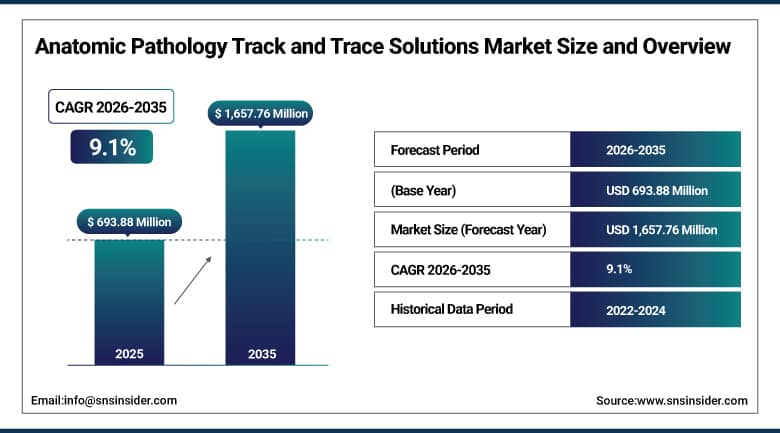
The global Anatomic Pathology Track and Trace Solutions Market was valued at USD 693.88 Million in 2025 and is expected to reach USD 1,657.76 Million by 2035, growing at a CAGR of 9.1% from 2026 to 2035.
The anatomic pathology track and trace solutions consist of a combination of both hardware and software systems that have been engineered to enable monitoring of biological specimens within the laboratory process from accessioning through to diagnosis and ensure proper identification and chain of custody control during the entire process. The marketplace features barcode and RFID penetration above 70% in the processes involving slides and cassettes, software modules in 45% of new system purchases and hybrid hardware/software systems in 52% of multisite laboratories.
Clinisys is building the Clinisys Laboratory Solution, a cloud-native platform designed to consolidate its legacy Sunquest, PowerPath, CoPathPlus, and Orchard product lines into a single unified laboratory and specimen tracking system, following a run of mergers that consolidated much of the anatomic pathology informatics market under one umbrella, reflecting the scale of platform consolidation reshaping how hospital and reference laboratories manage specimen traceability worldwide.
Market Size and Forecast
- Market Size in 2026E: USD 756.90 Million
- Market Size by 2035: USD 1,657.76 Million
- CAGR: 9.1% from 2026 to 2035
- Fastest Growing Region: Asia Pacific
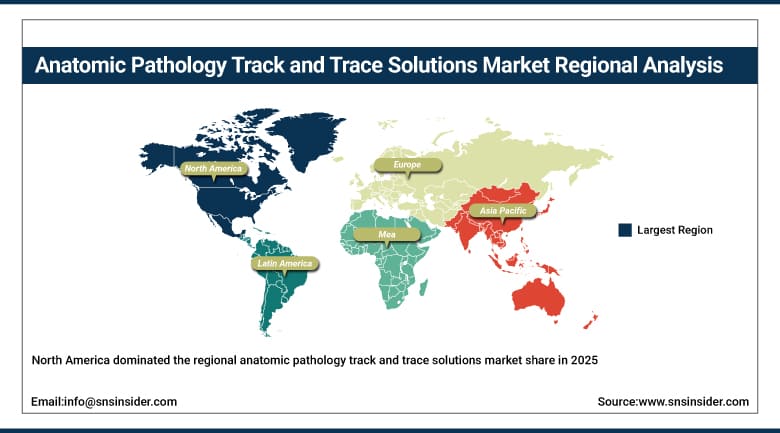
- Largest Region: North America
To Get More Information On Anatomic Pathology Track and Trace Solutions Market - Request Free Sample Report
Anatomic Pathology Track and Trace Solutions Market Trends
- Growing barcode and RFID penetration now exceeds 70% across slide and cassette workflows in modern anatomic pathology laboratories.
- Rising hybrid hardware-software bundle adoption, now used by 52% of multi-site laboratories, continues to reinforce integrated deployment preferences.
- Expanding cloud-native platform consolidation is unifying legacy laboratory information system brands into single, modernized architectures.
- Increasing digital pathology integration continues to enable AI-powered diagnostic accuracy alongside traditional specimen tracking capabilities.
- Growing regulatory requirements for laboratory accreditation continue compelling facilities to adopt automated identification technologies to lower liability risk.
U.S. Anatomic Pathology Track and Trace Solutions Market Outlook
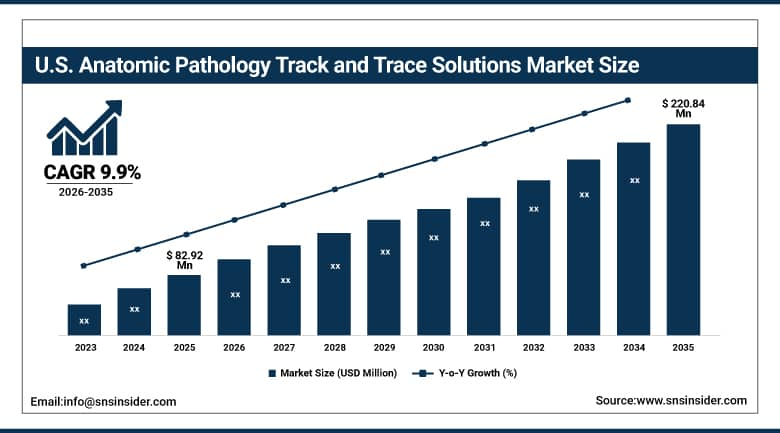
The U.S. Anatomic Pathology Track and Trace Solutions Market was valued at USD 82.92 Million in 2025 and is projected to reach USD 220.84 Million by 2035, growing at a CAGR of 9.9% during 2026-2035.
The increasing need for digitization, regulatory compliance, and specimen traceability across over 9,500 pathology labs in North America continues to drive market expansion. Leading platform providers continue to expand cloud-based pathology tracking capability addressing rising demand from hospital and reference laboratories. Growing digital pathology scanner integration continues to reinforce sustained domestic market development nationwide.
NovoPath's SaaS laboratory information system, delivered on Microsoft's cloud infrastructure and certified SOC 2 Type II, integrates with more than 150 electronic medical record systems and remains platform-agnostic with respect to digital viewers, scanners, and third-party tools, with labs reporting meaningful capacity gains including handling significant case volume growth without proportionally increasing staff.
Anatomic Pathology Track and Trace Solutions Market Segment Analysis
- By Technology, Barcode-Based led the Anatomic Pathology Track and Trace Solutions Market with a 58.60% share in 2025, while RFID-Based is the fastest-growing technology segment with a CAGR of 10.80% from 2026-2035.
- By Application, Specimen Identification/Tracking led the Anatomic Pathology Track and Trace Solutions Market with a 42.60% share in 2025, while Slide Tracking is the fastest-growing application segment with a CAGR of 10.60% from 2026-2035.
- By End User, Hospital Laboratories led the Anatomic Pathology Track and Trace Solutions Market with a 44.60% share in 2025, while Independent & Reference Laboratories is the fastest-growing end user segment with a CAGR of 10.90% from 2026-2035.
- By Product, Software led the Anatomic Pathology Track and Trace Solutions Market with a 48.00% share in 2025, while Hardware is the fastest-growing product segment with a CAGR of 9.40% from 2026-2035.
By Technology, Barcode-Based Dominated the Market While RFID-Based Is the Fastest-Growing Segment
The Barcode-Based segment had a market revenue share of 58.60% in the Anatomic Pathology Track and Trace Solutions Market in 2025, attributed to the fact that barcode technology acts as an efficient foundation for specimen identification through slides, cassettes, and tissue blocks due to its well-established cost-effectiveness. Barcode and RFID adoption in this market remains above 70%, with barcode technology being adopted more than RFID in the slide and cassette processes to ensure the dominance of this technology.
The RFID-Based segment is expected to have the highest Compound Annual Growth Rate (CAGR) of 10.80% throughout the forecast period of 2026-2035, fueled by increased demand from laboratories for contactless specimen identification technology which is more efficient than line-of-sight barcode technology. Hybrid hardware-software solution adoption remains at 52%, further driving the growth of this segment in comparison to conventional barcode technology.
By Application, Specimen Identification/Tracking Dominated the Market While Slide Tracking Is the Fastest-Growing Segment
Specimen Identification/Tracking application category accounted for a leading share of 42.60% in the Anatomic Pathology Track and Trace Solutions Market revenue in 2025 owing to its critical importance in ensuring correct specimen identification and proper chain of custody starting from the time of entering specimens into the laboratory workflow process. Specimen tracking remains the basic application that supports lab accreditation requirements, making this application a leader in the global market.
The Slide Tracking application is anticipated to grow at the fastest CAGR of 10.60% over the forecast period 2026-2035 mainly owing to the adoption of tracking solutions aimed at minimizing specimen identification mistakes and improving workflow efficiency in anatomic pathology laboratories. Growing use of digital pathology scanners, where exact slide-level traceability becomes important, continues to drive above-average growth of this application.
By Product, Software Dominated the Market While Hardware Is the Fastest-Growing Segment
The Software segment led the Anatomic Pathology Track and Trace Solutions Market with a revenue share of 48.00% in 2025, experiencing significant traction due to the rising adoption of digital pathology solutions that improve workflow efficiencies and ensure data integrity. Software modules continue to be embedded in more than 45% of new deployments, sustaining this product category's dominant position across the broader market worldwide.
The Hardware segment is expected to register the fastest CAGR of 9.40% during the forecast period 2026-2035, driven by growing barcode printer, RFID reader, and labeling system installation accompanying new laboratory digitization initiatives. Rising multi-site laboratory network expansion requiring physical identification infrastructure continues to reinforce this segment's above-average growth trajectory relative to the more established software category.
Regional Analysis
|
Region |
Country |
Regional Share (2025) |
|---|---|---|
|
North America |
United States |
90.10% |
|
Europe |
Germany |
42.20% |
|
Asia Pacific |
China |
55.20% |
|
Middle East & Africa |
UAE |
20.60% |
|
Latin America |
Brazil |
22.60% |
North America Anatomic Pathology Track and Trace Solutions Market Insights
North America dominated the regional anatomic pathology track and trace solutions market share in 2025 because of the presence of advanced healthcare infrastructure and developed regulatory framework, along with rising digitization and requirement of specimen tracking among more than 9,500 pathology laboratories present in the region. Platform consolidation among the leading laboratory informatics companies further enhances the dominance of North America in the overall anatomic pathology track and trace solutions market.
United States represented significant market share of the North America region in 2025 owing to presence of major laboratory informatics companies such as Clinisys, NovoPath, and LigoLab. Canada is playing a key role in regional market growth due to growing adoption of laboratory digitization and rising regulatory requirements in the country's pathology laboratories.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Anatomic Pathology Track and Trace Solutions Market Insights
Europe represented a meaningful share of the global anatomic pathology track and trace solutions market in 2025, supported by hospital laboratory digital integration and strong regulatory frameworks governing laboratory accreditation and specimen traceability. Growing independent histopathology lab automation continues to reinforce steady regional demand for track and trace solutions across the broader European landscape.
Germany led the European market with a 42.20% regional share in 2025, driven by hospital laboratory digital integration and expanding independent histopathology lab automation. The United Kingdom, France, and the Netherlands are also contributing meaningfully to regional growth, supported by growing digital pathology adoption across major European healthcare systems.
Asia Pacific Anatomic Pathology Track and Trace Solutions Market Insights
Asia Pacific is forecasted to experience the fastest growth during the forecast period 2026-2035, due to increasing healthcare investments, diagnostic chain expansion, and growing adoption of laboratory digitization initiatives across China, Japan, and India. Rising cancer diagnostic testing volume continues to reinforce the region's above-average growth trajectory relative to more mature Western markets.
China accounted for approximately 55.20% of the Asia Pacific market in 2025, propelled by diagnostic chain expansion and growing healthcare infrastructure investment. Japan, India, and South Korea are also contributing meaningfully to regional growth, with India benefiting from expanding hospital laboratory network digitization.
Middle East & Africa and Latin America Anatomic Pathology Track and Trace Solutions Market Insights
The Middle East & Africa region is exhibiting steady growth as healthcare infrastructure investment and laboratory modernization initiatives continue expanding across the Gulf states. Latin America is similarly benefiting from expanding diagnostic laboratory networks and growing regulatory compliance requirements across major regional economies.
The UAE led the Middle East & Africa market with a 20.60% regional share in 2025, supported by growing healthcare infrastructure investment and expanding laboratory modernization initiatives. Brazil represented 22.60% of the Latin American market in 2025, driven by expanding diagnostic laboratory networks, with Mexico also contributing to regional growth through rising laboratory digitization interest.
Market Dynamics
Growth Drivers: Patient Safety Regulation and Laboratory Digitization Driving Market Growth
The Anatomic Pathology Track and Trace Solutions Market is being driven primarily by the rising global incidence of chronic diseases that demand tissue diagnostics and the imperative need to eliminate pre-analytical errors that endanger patient safety. Rigorous regulatory requirements for laboratory accreditation continue compelling facilities to adopt automated identification technologies to lower liability risks, while increasing volume of diagnostic tests performed in anatomic pathology laboratories continues to sustain demand for specimen tracking infrastructure.
Growing barcode and RFID penetration now exceeds 70% across slide and cassette workflows in modern anatomic pathology laboratories. Rising hybrid hardware-software bundle adoption continues to reinforce integrated deployment preferences among multi-site laboratories. Expanding cloud-native platform consolidation is further unifying legacy laboratory information system brands into single, modernized architectures, reinforcing sustained industry investment.
Restraints: Legacy System Integration Complexity and High Implementation Costs Limiting Market Expansion
Despite positive underlying demand dynamics, the market is characterized by significant challenges linked to the complexity of integrating legacy systems, since bringing together different legacy laboratory information system solutions on single cloud-native platforms still takes many years even for the largest companies. The high cost of implementation in connection with the enterprise-level track and trace systems infrastructure persists as an inhibitor of adoption in small independent laboratories.
The increased level of competition within an ever-growing list of laboratory informatics providers, including due to mergers and acquisitions transactions, results in persistent market volatility when laboratories consider their long-term platform investments. Workflow disruption risks involved in switching from legacy to the new platform prevent some hospitals and reference laboratories from considering switching to a new solution.
Opportunities: AI-Powered Digital Pathology Integration and Cloud Platform Modernization Creating New Growth Avenues
Substantial opportunity exists in continued integration of AI-powered diagnostic accuracy tools alongside traditional specimen tracking capabilities, enabling laboratories to combine workflow automation with advanced diagnostic support. Companies that successfully commercialize unified, cloud-native platforms consolidating legacy laboratory information system functionality stand to capture significant share of category growth as fragmented multi-vendor environments seek modernization.
Growing independent and reference laboratory network expansion presents a further significant growth avenue, as the increasing number of cancer diagnostic tests performed outside hospital settings continues to drive demand for scalable, multi-site track and trace infrastructure. Expanding healthcare investment and diagnostic chain development across Asia Pacific also represent meaningful untapped opportunity for laboratory informatics providers.
Recent Developments:
- 2026: Clinisys PowerPath introduced support for foreign container IDs, helping eliminate re-labelling of materials and enabling integrated reporting for combined anatomic pathology and molecular results.
- 2026: LigoLab continued marketing an integrated Laboratory Information System plus revenue cycle management platform, appealing to pathology groups seeking operations and billing under one roof.
- 2026: CompuGroup Medical continued expanding its AP EASY cloud-deployed anatomic pathology platform alongside its LABDAQ and SCHUYLAB offerings for smaller and ambulatory labs.
Anatomic Pathology Track and Trace Solutions Market key players are:
- Clinisys, Inc.
- CompuGroup Medical SE & Co. KGaA
- Computype, Inc.
- Zebra Technologies Corporation
- Cerebrum Corp.
- XiFin, Inc.
- Sunquest Information Systems, Inc.
- LigoLab Information Systems, LLC
- NovoPath, Inc.
- Sakura Finetek USA, Inc.
- Leica Biosystems Nussloch GmbH
- Roper Technologies, Inc.
- General Data Healthcare
- Orchard Software Corporation
- Epic Systems Corporation (Beaker)
- Stryker Corporation (Novadaq)
- PathXL Ltd. (Philips)
- Netherlands Institute of Pathology
- Onclave Medical Systems
- InSourceLIS, Inc.
Anatomic Pathology Track and Trace Solutions Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 693.88 Million |
| Market Size by 2035 | USD 1,657.76 Million |
| CAGR | CAGR of 9.1% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Technology (Barcode-Based, RFID-Based, Hybrid Solutions) • By Application (Specimen Identification, Slide Tracking, Tissue Cassette/Block Tracking, Chain of Custody Management) • By End User (Hospital Laboratories, Independent & Reference Laboratories, Academic Medical Centers, Others) • By Product (Software, Hardware) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Clinisys, Inc.; CompuGroup Medical SE & Co. KGaA; Computype, Inc.; Zebra Technologies Corporation; Cerebrum Corp.; XiFin, Inc.; Sunquest Information Systems, Inc.; LigoLab Information Systems, LLC; NovoPath, Inc.; Sakura Finetek USA, Inc.; Leica Biosystems Nussloch GmbH; Roper Technologies, Inc.; General Data Healthcare; Orchard Software Corporation; Epic Systems Corporation (Beaker); Stryker Corporation (Novadaq); PathXL Ltd. (Philips); Netherlands Institute of Pathology; Onclave Medical Systems; InSourceLIS, Inc. |
Frequently Asked Questions
The Barcode-Based segment dominated the Anatomic Pathology Track and Trace Solutions Market in 2025, accounting for approximately 58.60% market share.
