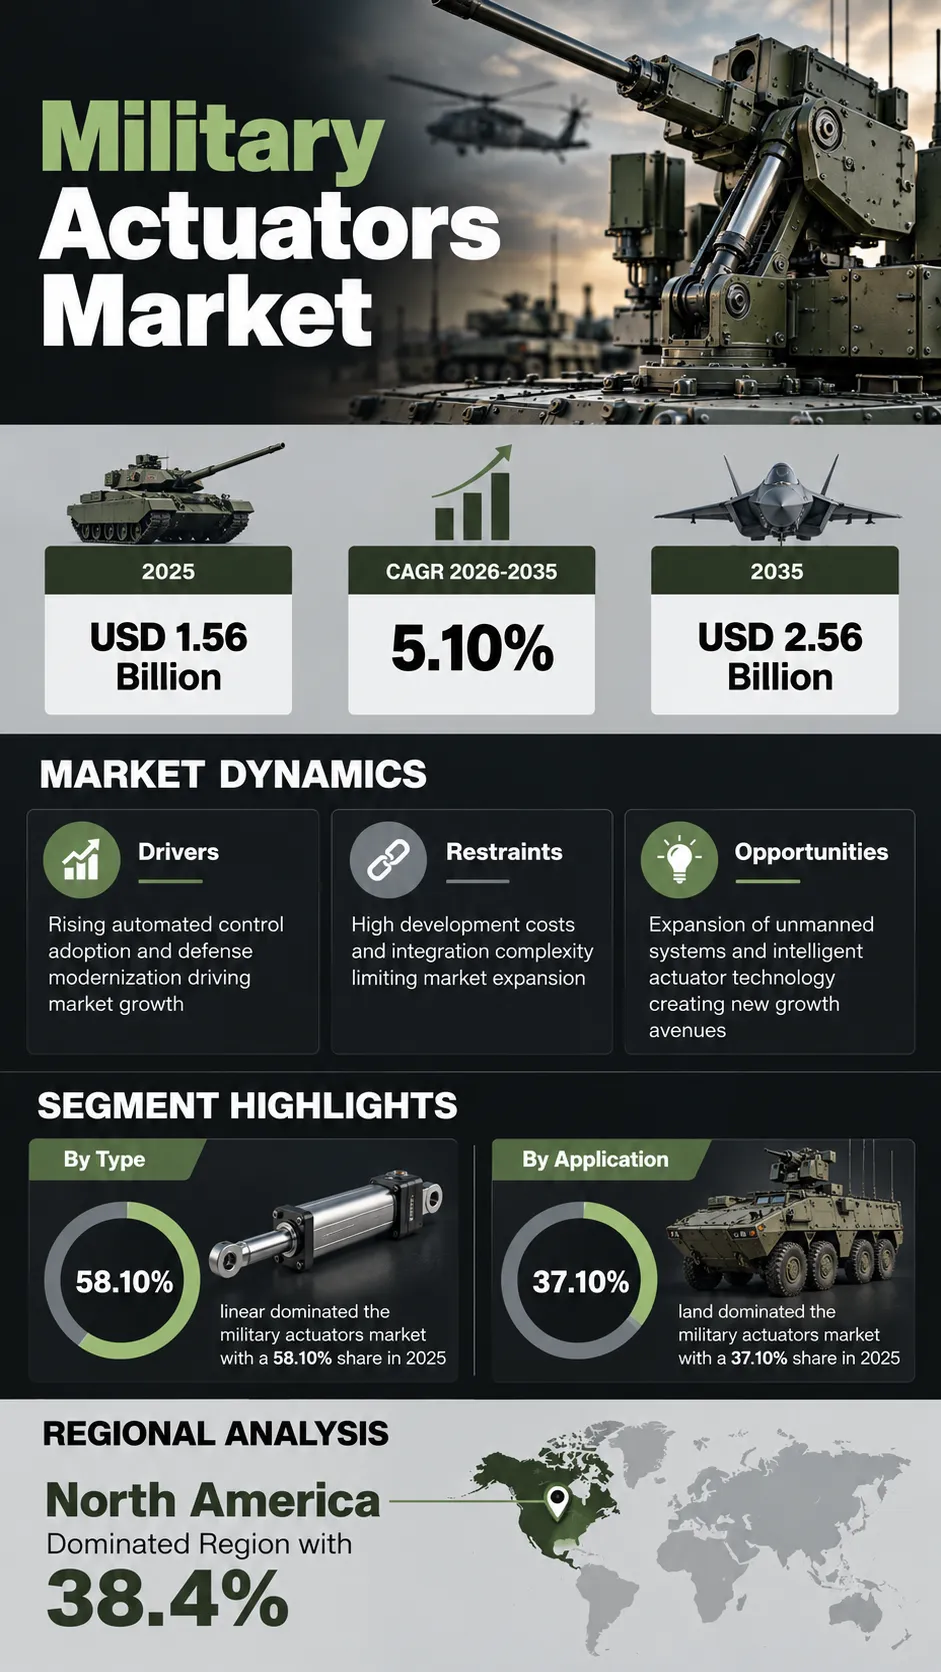
The global Military Actuators Market is set for steady expansion as automated control adoption and defense modernization continue to reshape motion control procurement worldwide. “According to a recent study by SNS Insider, the global Military Actuators Market size valued at USD 1.56 billion in 2025, is anticipated to grow to USD 2.56 billion by 2035, registering a CAGR of 5.10% over the 2026–2035 forecast period.”
There have been notable changes within actuator control technology over time, due to which many manufacturers who aim at improving precision and reliability can take advantage of this trend. This includes the need for more advanced electro-mechanical and intelligent actuator systems that will provide defense platforms with the ability to achieve precise, responsive motion control. This applies in situations where military actuators support land, air, and naval defense applications. Manufacturers are constantly working hard to ensure that their actuator systems perform better than before in order to meet various precision and reliability requirements.
To Get Detailed Insights on the Military Actuators Market – Request a Sample Report
Intelligent Actuators and Unmanned Systems Create New Demand
The military actuators market has evolved from conventional hydraulic and pneumatic systems to increasingly sophisticated, electro-mechanical and intelligent actuator technology. The growing investment in sensor integration, miniaturization, and unmanned platform-specific actuator development across manufacturers of all sizes has required the development of more capable and efficient motion control systems.
New actuator and control technologies can increase precision, improve energy efficiency, and allow for expansion into increasingly diverse land, air, and naval defense applications. This gives defense forces the possibility to achieve precise, reliable motion control while supporting the industry's broader shift toward automated and unmanned military systems.
Actuator manufacturers, defense contractors, and allied militaries are increasingly cooperating thanks to the growing interest in developing future solutions for advanced, application-specific motion control technology.
Key Market Findings Highlight High-Growth Segments
The linear actuators segment dominated all categories in the military actuators market share holding around 58.10% due to extensive use in missile launch systems and flight control surfaces. The fastest growing category is expected to be rotary actuators which will grow at a CAGR of 6.80%, owing to growing demand for precise rotational positioning across armament and targeting systems.
By application, land applications dominated the market due to extensive use in armored vehicles and ground systems. Air applications will see the fastest growth in revenue generation at a CAGR of 6.20%, driven by growing demand for unmanned aerial systems and advanced weapons platforms.
Based on system type, hydraulic actuators remain a dominant category owing to their reliability for positioning armored plates and guns. On the other hand, electric and electro-mechanical actuators will be the segment recording the fastest revenue growth at a 7.40% CAGR, supported by innovations enhancing performance and reliability.
Distributive component type trends are changing as well. Cylinders accounted for the largest revenue share owing to extensive use across hydraulic and pneumatic actuator systems. But servo valves and drives will turn out to be the fastest-growing component category through 2035, on the back of growing demand for precise, responsive control components.
Precision, Energy Efficiency, and Unmanned Platform Integration Gain Importance
In this regard, defense forces have been looking at military actuator systems that would deliver more consistent precision while requiring greater energy efficiency and unmanned platform compatibility.
Innovation in electro-mechanical design, sensor integration, and intelligent control technology has been making it possible for manufacturers to come up with systems that can operate effectively across increasingly diverse land, air, and naval applications. In addition to that, increasing emphasis on miniaturization for unmanned systems is also making it possible for defense platforms to find solutions that support compact, lightweight architecture requirements. Such trends are likely to become even more prominent in the future.
North America Emerges as the Largest Market with 38.4% Regional Revenue Share Amid Sustained Defense Spending
The North America region represented the largest share of regional market revenue in 2025 at 38.4%, driven by significant defense spending and technological advancements. On the other hand, the Asia Pacific region is anticipated to expand at the highest CAGR during the forecast period through 2035, propelled by rising defense budgets and increasing indigenous military modernization programs across China and India.
Leading Companies Drive Innovation and Competition
The environment continues to stay very dynamic since players continue innovating on electro-mechanical technology and intelligent actuator systems as well as forming partnerships in order to enhance their position in the industry. Some of the major companies that operate in the global military actuators market are Moog, Venture Mfg., Parker Hannifin, Kyntronics, Nook Industries, AMETEK, Ultra Motion, EME Elektro-Metall Export, Beaver Aerospace & Defense, and Honeywell International.
An SNS Insider analyst Sushant Kadam commented, "The growing shift toward automated, intelligent defense systems is creating sustained demand for precise, energy-efficient actuator technology. Manufacturers that successfully combine electro-mechanical innovation, sensor integration, and unmanned platform expertise will be best positioned to capitalize on emerging opportunities across land, air, and naval military actuator segments."
About the Author
Get in touch