
3D Printing Materials Market Report Scope & Overview:
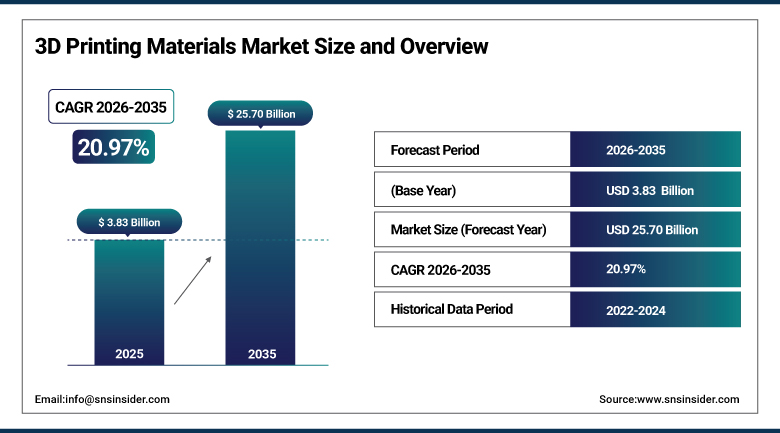
The 3D Printing Materials Market was valued at USD 3.83 Billion in 2025 and is expected to reach USD 25.70 Billion by 2035, growing at a CAGR of 20.97% from 2026-2035.
The demand for 3D Printing Materials Market is rising due to the increased use of additive manufacturing in the aerospace, automotive, health care, and industrial sector. The need for customized parts and lightweight materials is prompting the manufacturers to use specialty polymers, metals, ceramics, and composite materials. Healthcare makes use of 3D printing technology for making customized implants, prosthetics, and dental products. In the aerospace and automotive industry, the use of 3D printing is being used to reduce the wastage of materials and to decrease the time and improve the performance of the components. Also, the advancements in the formulation of materials, the accuracy in the printing process and production speed are driving commercial applications.
⮞In November 2025, Formnext in Frankfurt, organized by Mesago Messe Frankfurt, hosted 804 exhibitors, 61% of them from abroad, and 38,282 visitors over four days. The turnout reflects how widely additive manufacturing and its materials have spread across industry.
To Get more information 3D Printing Materials Market - Request Free Sample Report
3D Printing Materials Market Trends
-
Qualification of printed metal parts for aerospace, space and defense
-
Growth of recycled and scrap-to-powder feedstock
-
Expansion of regional atomization capacity for titanium and copper alloys
-
High-performance polymers and photopolymers for production parts
-
Medical-grade and food-contact approved resins
U.S. 3D Printing Materials Market Outlook
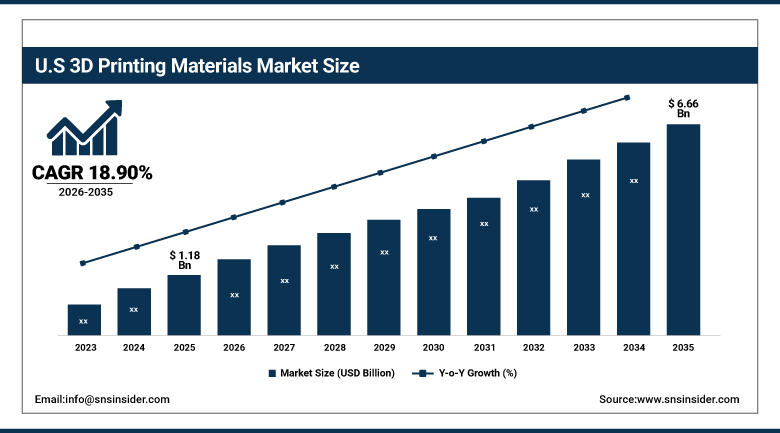
The U.S. 3D Printing Materials Market was valued at USD 1.18 Billion in 2025 and is expected to reach USD 6.66 Billion by 2035, growing at a CAGR of 18.90% from 2026-2035.
The U.S. 3D Printing Materials Market is the largest national market, supported by aerospace and defense programs, a strong medical device sector and a large base of machine makers and powder producers. The Department of Defense funds qualification of printed parts and powder supply. Shipbuilders and space agencies are writing requirements for metal additive manufacturing. Universities and national laboratories support materials research. Tariffs and raw material costs influence sourcing.
⮞In August 2026, the U.S. Navy's Submarine Industrial Base Program released new technical requirements for metallic additive manufacturing across submarine construction, maintenance and repair. The requirements aim to replace cast and wrought parts and support higher build rates.
3D Printing Materials Market Segment Analysis
-
By Material Type, the Polymers segment dominated the 3D Printing Materials Market with approximately 53.40% share in 2025, while the Metals segment is the fastest growing with a CAGR of approximately 23.42%.
-
By Form, the Powder segment dominated the 3D Printing Materials Market with approximately 42.70% share in 2025, while the Filament segment is the fastest growing with a CAGR of approximately 22.37%.
-
By End Use, the Aerospace and Defense segment dominated the 3D Printing Materials Market with approximately 24.73% share in 2025, while the Automotive segment is the fastest growing with a CAGR of approximately 21.72%.
-
By Application, the Prototyping segment dominated the 3D Printing Materials Market with approximately 46.30% share in 2025, while the Manufacturing segment is the fastest growing with a CAGR of approximately 26.77%.
By Material Type, Polymers Dominate the 3D Printing Materials Market and Metals Grow Fastest
Polymers lead because photopolymers, nylon powders and thermoplastic filaments work on the widest range of low-cost printers and suit prototypes, jigs and end-use parts. Desktop and industrial users buy them in volume, and material choices keep expanding. Engineers value the low machine cost and fast turnaround, and new grades add flame retardancy, flexibility and biocompatibility.
Metals are the fastest growing as aerospace, space, defense, energy and medical users move to printed production parts. Titanium, nickel, aluminum, copper and steel powders are being qualified for demanding service. Producers are adding atomization capacity and recycled feedstock to secure supply. Higher part values justify premium powders, and certified grades give buyers confidence.
⮞In November 2025, Henkel launched two Loctite 3D MED414 medical resins in red and clear and the Loctite 3D IND3785 white rigid industrial material. The launches show polymer suppliers targeting regulated and production uses.
By Form, Powder Dominates the 3D Printing Materials Market and Filament Grows Fastest
Powder leads because laser and electron beam powder bed systems, binder jetting and directed energy deposition all rely on it, across both polymers and metals. Production users prefer powders for dense, complex parts. Suppliers compete on particle size, flowability and purity, and reuse of unfused powder is a major cost and sustainability topic.
Filament is the fastest growing as low-cost extrusion printers spread through education, small business and industrial workshops. Engineering grades such as carbon-filled nylon, polyetheretherketone and polycarbonate are widening what filament can do. Spool-based supply is easy to handle and store, and online sales channels give makers fast access to new colors and properties.
⮞In November 2025, Arkema introduced Orgasol PA12 powders for powder bed fusion that it said can lower material variable costs by up to 50%. Lower material cost is aimed at pushing powder-based printing into larger production runs.
By End Use, Aerospace and Defense Dominates the 3D Printing Materials Market and Automotive Grows Fastest
Aerospace and defense leads because lightweight, complex and low-volume parts suit additive manufacturing and justify premium materials. Engine makers, airframers, satellite builders and defense programs are qualifying printed titanium, nickel and polymer parts. Strict certification means suppliers must document every powder batch, which favors established producers with traceability systems.
Automotive is the fastest growing as carmakers move from prototypes to tooling, spare parts and low-volume production. Electric vehicle platforms use printed brackets, cooling components and custom interior parts. Polymer and aluminum materials dominate early uses, and falling material costs support wider adoption. Motorsport and luxury brands lead before wider rollout.
⮞In May 2026, the U.S. International Trade Administration reported that the University of Brasília had built a prototype hybrid rocket engine using metal 3D printing. The report listed opportunities for alloys, powders and certification services in Brazil.
By Application, Prototyping Dominates the 3D Printing Materials Market and Manufacturing Grows Fastest
Prototyping leads because designers and engineers use additive manufacturing to test shapes and fit quickly and cheaply. Photopolymers and thermoplastics are used in large quantities for concept models and functional tests. Every new product program consumes materials for several iterations, and desktop printers have put the capability in thousands of design offices.
Manufacturing is the fastest growing as companies shift from models to finished parts used in aircraft, vehicles, medical devices and industrial equipment. Production demands consistent powder quality and process control. Qualification standards are maturing, and printers are built for repeatable output. Higher volumes of printed parts translate directly into larger recurring material purchases.
⮞In 2025, ASTM International issued standard F3616-25, a guide for measuring and classifying powder contamination in laser powder bed fusion. Shared quality methods support the use of printed parts in production.
Regional Insights
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
U.S. |
78.93 |
|
Europe |
Germany |
22.06 |
|
Asia Pacific |
China |
49.21 |
|
Latin America |
Brazil |
44.58 |
|
Middle East & Africa |
Saudi Arabia |
36.47 |
North America 3D Printing Materials Market Insights
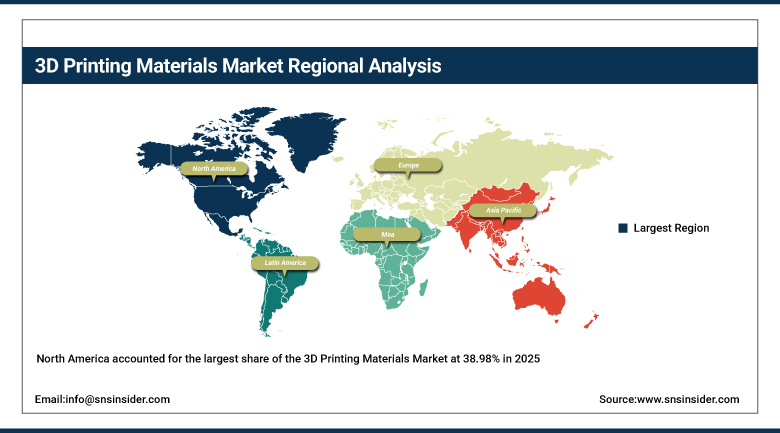
North America accounted for the largest share of the 3D Printing Materials Market at 38.98% in 2025, led by the United States and followed by Canada. Aerospace, defense, medical and energy users are shifting to printed production parts. The region hosts many machine makers, powder producers and research laboratories.
Government programs fund powder supply and part qualification, and companies are adding atomization capacity near end customers. Tariff changes and raw material costs affect pricing, and long qualification cycles slow some adoption. Canada supplies plasma-atomized titanium and aluminum powders to defense and aerospace customers.
⮞In April 2026, the U.S. Defense Logistics Agency awarded a Phase II contract to 6K Additive to convert military depot scrap into metal powders. The award supports secure powder supply within the country for defense programs.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe 3D Printing Materials Market Insights
Europe held about 27.20% of the 3D Printing Materials Market in 2025 and is led by Germany, the United Kingdom, France, Italy and Austria. Strong aerospace, automotive and medical industries drive demand, and the region is home to leading powder, polymer and ceramic suppliers.
Sustainability rules and funding programs encourage recycled powders and bio-based polymers. Collaboration between universities, machine makers and materials producers is common. High energy costs and strict qualification rules raise production costs, and competition from Asian suppliers is increasing in standard grades.
⮞The REPAM project, coordinated by KTH Royal Institute of Technology under Horizon Europe, runs from October 2024 to September 2027. It targets low powder yields, scrap-to-powder routes and powder reconditioning.
Asia Pacific 3D Printing Materials Market Insights
Asia Pacific is projected to be the fastest growing region in the 3D Printing Materials Market, at a CAGR of 25.02% over 2026-2035, and held about 26.82% share in 2025. China, Japan, India, South Korea and Australia lead. Government industrial policy, expanding electronics and automotive production and new aerospace programs lift demand.
Chinese producers are scaling powder and resin capacity and targeting Western markets with competitive prices. India is building additive manufacturing clusters, and Japan and South Korea focus on high-quality metals and ceramics. Intellectual property concerns and uneven standards are challenges for foreign buyers.
⮞In April 2026, China's Avimetal showed MT-CuCrZr copper powder with 300 tonnes per year of capacity at TCT Asia. The capacity points to local suppliers scaling specialty alloy powders.
MEA & Latin America 3D Printing Materials Market Insights
Latin America and the Middle East and Africa together hold about 7.00% of the 3D Printing Materials Market. In Latin America, Brazil, Mexico, Argentina and Colombia lead, using printing for aerospace, oil and gas, and medical parts. In the Middle East and Africa, Saudi Arabia, the United Arab Emirates and South Africa lead.
Gulf countries are building local manufacturing under national industrial strategies and partnering with global machine makers. Latin American users rely on imported materials, and training institutes and research centers are growing. Currency swings, import costs and a limited base of local suppliers hold back volumes.
⮞In December 2025, SENAI CIMATEC expanded its additive manufacturing bureau at CIMATEC Park in Camaçari, Brazil, with Petrobras. It now offers high-performance polymer printing and metal directed energy deposition.
Market Dynamics
Growth Drivers: Production Part Adoption and Government Industrial Programs Drive Growth in the 3D Printing Materials Market
The process of moving from prototyping to serial production is increasing the demand for 3D printing materials in aerospace, space, defense, energy, automotive, and medical industries. The need for a steady supply of reliable metal powders, polymers, resins, and wires is growing with manufacturers adopting printed parts into their commercial products.
Industrial government programs also contribute to this trend with support for additive manufacturing capabilities, labor force training, domestic feedstock production, and cluster development. Government procurement and funding programs can assist small manufacturers to obtain materials and equipment, thus lowering the entry barrier to adoption. Testing and certification of materials and component qualification facilitate adoption of new alloys and polymers.
⮞In March 2026, India's Ministry of Electronics and Information Technology discussed its National Strategy on Additive Manufacturing 2.0 at the 2nd National AM Symposium. The strategy aims to cut machine and material costs through clusters.
Restraints: Tariff Volatility and Powder Reuse Restrain Growth in the 3D Printing Materials Market
The fluctuations in tariffs introduce uncertainties in the supply chain of materials for 3D printing, especially for metallic powders and specialty feedstock that is imported from overseas. Tariffs on imports can cause additional costs of procurement, problems in dealing with suppliers, and pricing challenges for companies with operations in several countries.
Uncertain costs of inputs can slow down the purchase process and prompt the buyer to diversify suppliers, thereby increasing the number of qualification and inventory control procedures. Reusing the powder is also a constraint as the metal powder that was not fused during printing can be reused in future prints. But this depends on several factors such as the type of the alloy, printing method, environmental conditions, and the level of quality control. The high cost of equipment, materials, and certification also limits their use among small companies.
⮞In June 2026, the Metal Powder Industries Federation called tariff volatility a major disruptor and said reuse of build-bed powder reduced new additive powder purchases. It estimated combined metal injection molding and additive powder shipments rose about 5% in 2025.
Opportunities: Localized Powder Production and Defense Supply Chains Create Opportunities in the 3D Printing Materials Market
Local powder production presents a chance for materials suppliers who would like to increase their supply security and cut down on reliance on foreign sources. There is an increasing effort by both manufacturers and governments to make sure that titanium, nickel, copper, and other specialized alloys used in critical applications are available locally. Building new atomization plants and partnerships with regional producers could help.
Recycling of manufacturing waste to produce metal powders that meet the required criteria is another way of reducing waste and increasing efficiency. Defense supply chains represent yet another growth opportunity, since defense agencies have shown interest in on-demand production of spare parts for various military equipment. Certified materials, proper traceability, and certification could help suppliers win long-term contracts.
⮞In October 2025, NAMI, a joint venture of 3D Systems and Dussur in Saudi Arabia, reported a framework with Modern Isotopes Factory for up to 2,000 tungsten core components. Saudi Electric Company is taking a 30% stake.
Recent Developments
-
2026, Stratasys agreed to acquire Markforged from Nano Dimension for USD 42.5 million in cash. Nano Dimension keeps its metal binder jetting line, and closing is expected in the second half of 2026 pending approvals.
-
2026, Mimir agreed to acquire Sandvik's Osprey metal powder business, which supplies additive manufacturing and metal injection molding powders. The companies expect the deal to close in the third quarter of 2026.
-
2026, Amaero signed a supplier agreement for titanium powders and commissioned a third atomizer. The company said annual capacity reaches 200 tonnes of refractory powders and 480 tonnes of titanium powders with the added unit.
3D Printing Materials Companies are:
-
Stratasys Ltd.
-
Markforged
-
3D Systems Corporation
-
Arkema S.A.
-
Evonik Industries AG
-
6K Additive
-
Amaero Ltd.
-
EOS GmbH
-
Continuum Powders
-
CNPC Powder Group
-
AP&C (Colibrium Additive)
-
Tekna Holding ASA
-
Formlabs Inc.
-
Lithoz GmbH
-
Carpenter Technology Corporation
3D Printing Materials Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 3.83 Billion |
| Market Size by 2035 | USD 25.70 Billion |
| CAGR | CAGR of 20.97% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Material Type (Polymers, Metals, Ceramics, and Others) • By Form (Powder, Filament, and Liquid) • By End Use (Aerospace and Defense, Automotive, Healthcare, Consumer Products, and Others) • By Application (Prototyping, Manufacturing, and Tooling) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Stratasys Ltd., Markforged, 3D Systems Corporation, Arkema S.A., Henkel AG & Co. KGaA, Evonik Industries AG, 6K Additive, Amaero Ltd., EOS GmbH, Continuum Powders, CNPC Powder Group, AP&C (Colibrium Additive), Avimetal, Tekna Holding ASA, Formlabs Inc., Lithoz GmbH, Carpenter Technology Corporation |
Frequently Asked Questions
Key players include Stratasys, Markforged, 3D Systems, Arkema, Henkel, Evonik, 6K Additive, Amaero, EOS, Continuum Powders, CNPC Powder, AP&C, Avimetal, Tekna, Formlabs, Lithoz and Carpenter Technology.
Key opportunities include localized powder production, recycled and scrap-to-powder feedstock, defense supply chains and fast-growing Asia Pacific demand.
The move from prototyping to serial production of printed parts, together with government-funded qualification programs, is the main growth factor.
By Material Type, the Polymers segment dominated the market in 2025 with an estimated 53.40% share, supported by wide use of photopolymers and thermoplastics.
North America dominated the market with a share of 38.98% in 2025, driven by aerospace, defense and medical demand and a strong base of powder and machine suppliers.
