
Acrylate Market Report Scope & Overview
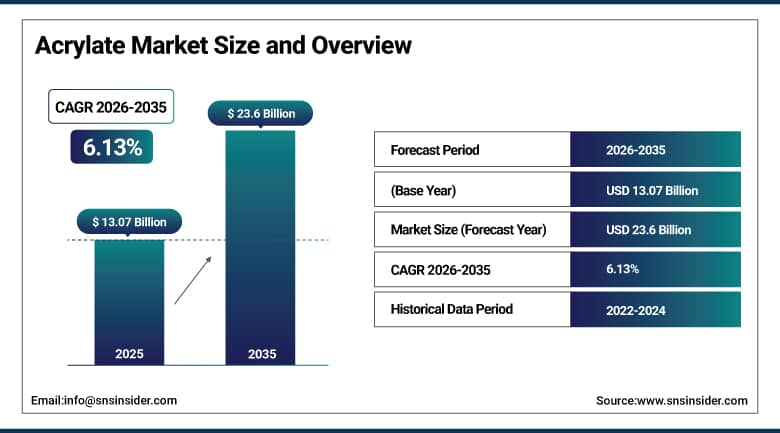
The Acrylate Market was valued at USD 13.07 billion in 2025 and is expected to reach USD 23.6 billion by 2035, growing at a CAGR of 6.13% from 2026–2035.
Acrylates are vital chemicals that serve as starting blocks in the production of plastics and elastomers, paints and lacquers, coatings, adhesives, textiles, and various other materials. Acrylates are predominantly manufactured from propylene and acrylic acid. These chemicals play an important role in the development of materials widely used in construction, automotive, packaging, and consumer goods. Among the current market trends is the transition from solvent-based formulations towards more eco-friendly water-based ones. It is being fueled by the regulation of emissions of volatile organic compounds. Construction growth in Asia and North America, the rising need for low-VOC coatings, as well as new advancements in specialty acrylates are driving the market.
Global demand for coatings continues to support acrylate consumption, with the global coatings industry producing approximately 45 million metric tons annually. Architectural coatings account for around 50% of total coatings demand, while industrial applications represent a major share of the remainder. Growing adoption of waterborne, low-VOC, and high-performance coatings is creating additional demand for acrylic and specialty acrylate technologies.
To Get More Information On Acrylate Market - Request Free Sample Report
Acrylate Market Trends
-
Growing adoption of water-based acrylate systems replacing solvent-based formulations in response to VOC emission regulations.
-
Rising demand from the construction industry for acrylate-based weatherproofing coatings and high-performance sealants.
-
The development of UV-curing acrylate polymers that meet fast curing times and high performance in electronics, 3D printing, and specialty coating applications.
-
The manufacture of bio-acrylics using sustainable sources, as the sector trends towards using eco-friendly raw materials.
-
The growing use of acrylic polymer dispersions in the textile industry as finishes and coatings.
-
The expansion of Asia-Pacific facilities by key players in the sector putting pricing pressure on Western firms.
-
The increased use of specialty acrylates in pressure sensitive adhesive applications in label, medical, and electronics assembly applications.
U.S. Acrylate Market Outlook
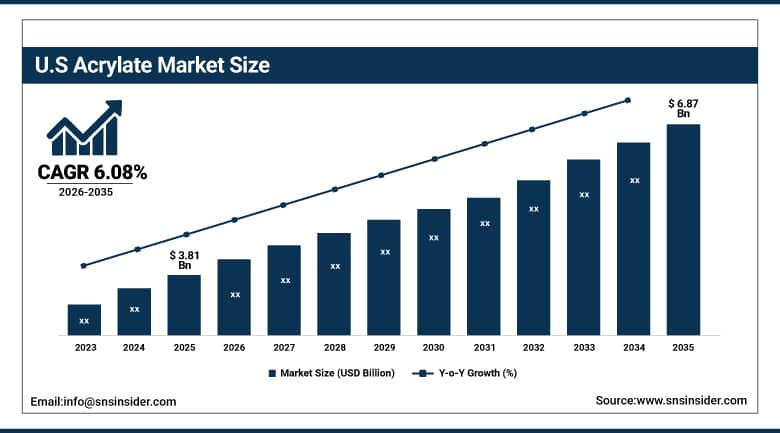
The U.S. Acrylate Market was valued at USD 3.81 billion in 2025 and is expected to reach USD 6.87 billion by 2035, at a CAGR of 6.08% from 2026 to 2035.
The U.S. acrylate market is among the most developed in the world, thanks to high demand from the paints & coatings industry, the adhesive industry, and the construction sector. The U.S. Infrastructure Investment and Jobs Act has boosted spending in construction and renovation activities, thereby boosting the use of acrylate sealants and coatings. U.S. manufacturers such as Dow Inc., BASF Corporation, and Arkema have been developing advanced low-VOC and biobased acrylates. Stringent environmental protection agency emission standards have hastened the move from solvent to water-based acrylate technologies.
According to the American Coatings Association, eco-friendly and low-VOC acrylate compositions constitute more than 30% of the new product introductions in the coatings industry of the United States. This trend is not only regulatory-driven but also represents a strategic advantage, especially for leading brands such as Sherwin-Williams and PPG.
Acrylate Market Segment Insights
-
Based on Type, Butyl Acrylate dominated the Acrylate Market with approximately 42.30% share in 2025, while 2-Ethylhexyl Acrylate is expected to be the fastest-growing segment with a CAGR of approximately 6.84% during 2026–2035.
-
Based on Application, Adhesives & Sealants dominated the Acrylate Market with approximately 35.30% share in 2025, while Paints & Coatings is expected to be the fastest-growing segment with a CAGR of approximately 6.52% during 2026–2035.
-
Based on Form, Water-Based acrylate systems dominated the Acrylate Market with approximately 55.67% share in 2025, while Solvent-Based systems are expected to register a CAGR of approximately 4.18% during 2026–2035.
-
Based on End Use, Paper & Packaging dominated the Acrylate Market with approximately 28.64% share in 2025, while Construction is expected to be the fastest-growing segment with a CAGR of approximately 6.71% during 2026–2035.
By Type, Butyl Acrylate leads the market, while 2-Ethylhexyl Acrylate is gaining demand in high-performance polymer applications.
The Butyl Acrylate segment dominates the Acrylate Market due to its extensive use as a key raw material in coatings, adhesives, sealants, textiles, and polymer formulations. Butyl acrylate provides flexibility, weather resistance, adhesion, and durability, making it suitable for a broad range of industrial and commercial applications. Its established manufacturing base and compatibility with different polymer systems have supported widespread adoption. Demand from construction, automotive, packaging, and consumer product industries continues to contribute to consumption, particularly where flexible and durable polymer properties are required.
The 2-Ethylhexyl Acrylate segment is expected to register strong growth during the forecast period, supported by its favorable performance characteristics in flexible coatings, adhesives, sealants, and specialty polymers. Its ability to provide flexibility, low-temperature performance, and weather resistance makes it valuable in applications requiring durable polymer systems. Increasing demand for high-performance coatings and adhesive formulations is encouraging manufacturers to utilize specialty acrylate monomers. Product development focused on improved durability, adhesion, and environmental performance is expected to create additional opportunities for this segment.
By Application, Adhesives & Sealants remain the leading application, supported by expanding demand for durable and flexible bonding solutions.
The Adhesives & Sealants segment dominates the Acrylate Market, supported by the extensive use of acrylate-based materials in pressure-sensitive adhesives, structural adhesives, tapes, and sealing formulations. Acrylates provide strong adhesion, flexibility, durability, and resistance to environmental conditions, making them suitable for construction, automotive, packaging, electronics, and consumer applications. Increasing demand for lightweight bonding solutions and improved assembly efficiency is further supporting the use of acrylate-based adhesive technologies across multiple industries.
The Paints & Coatings segment is expected to witness strong growth as manufacturers increasingly require coatings offering durability, weather resistance, adhesion, and improved surface protection. Acrylate-based coatings are widely used in architectural, automotive, industrial, and protective applications. Expansion of construction activity, infrastructure development, automotive production, and industrial manufacturing is supporting demand for high-performance coating materials. Continued development of water-based and low-VOC formulations is also creating opportunities for acrylate producers as industries move toward more environmentally compatible coating technologies.
By Form, Water-Based acrylate systems dominate as industries increasingly prioritize lower-emission and environmentally compatible formulations.
The Water-Based segment dominates the Acrylate Market, driven by increasing demand for coatings and polymer systems with lower environmental impact and reduced volatile organic compound emissions. Water-based acrylate formulations are widely used in paints, coatings, adhesives, and printing applications because they offer favorable application characteristics while helping manufacturers comply with increasingly stringent environmental requirements. Growing adoption across construction, packaging, automotive, and consumer product applications is strengthening demand for water-based systems.
The Solvent-Based segment continues to serve applications where specific performance characteristics, drying behavior, and substrate compatibility are required, although environmental regulations are encouraging a gradual shift toward alternative formulations. Manufacturers are increasingly investing in low-VOC and improved solvent-based technologies to maintain performance while addressing regulatory requirements. Demand remains supported by industrial coatings, specialty adhesives, and applications requiring high durability and chemical resistance. Product innovation and reformulation efforts are expected to help the segment remain relevant in specialized applications.
By End Use, Paper & Packaging represents a major demand area, while construction applications continue to expand with infrastructure development.
The Paper & Packaging segment represents an important demand area for acrylates, supported by the increasing use of acrylate-based coatings, adhesives, and barrier materials in modern packaging solutions. Acrylate formulations can enhance printability, surface protection, adhesion, and barrier performance, making them suitable for flexible packaging, labels, cartons, and specialty paper products. Growth in e-commerce, packaged food, consumer goods, and flexible packaging is increasing the requirement for high-performance materials that improve packaging functionality while maintaining efficient production processes.
The Construction segment is expected to witness strong growth due to increasing demand for adhesives, sealants, paints, coatings, and other polymer-based construction materials. Acrylates provide properties such as flexibility, adhesion, weather resistance, and durability that are valuable in both residential and commercial construction applications. Infrastructure development, urbanization, renovation activity, and demand for energy-efficient buildings are supporting consumption of advanced construction materials. The increasing adoption of durable and environmentally compatible coating and sealing solutions is expected to create further opportunities for acrylate-based products.
Regional Analysis:
|
Region |
Major Country |
Share within Region,2025 (%) |
|---|---|---|
|
North America |
United States |
68.00% |
|
Europe |
Germany |
28.00% |
|
Asia Pacific |
China |
52.00% |
|
Middle East & Africa |
UAE |
36.00% |
|
Latin America |
Brazil |
51.00% |
Asia Pacific Acrylate Market Insights
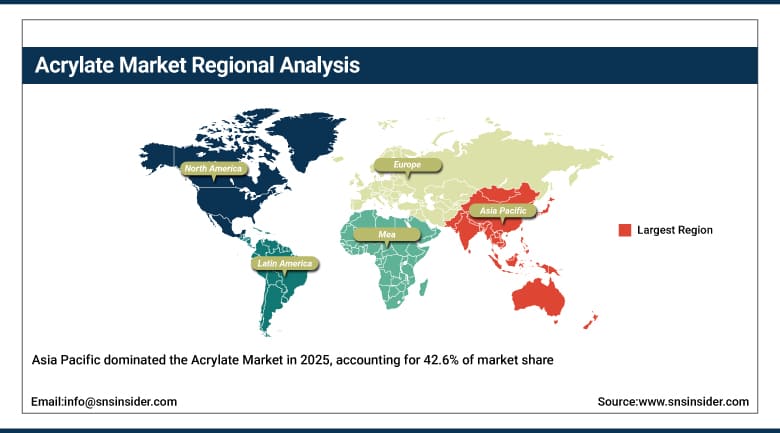
Asia Pacific dominated global acrylate production and consumption with 42.6% market share in 2025 and this leadership will continue through the forecast period. China is both the largest producer of propylene and acrylic acid and the largest consumer of downstream acrylates. The massive construction, textile, and packaging industries in China, India, and Southeast Asia provide the demand base. The region is also seeing growing demand for specialty acrylates as local electronic and automotive manufacturing grows more sophisticated.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Acrylate Market Insights
In North America, the acrylate market had a significant presence in 2025, which was due to the flourishing construction industry in the U.S., the thriving automotive industry, and the prominent position of chemical firms operating there. With the Implementation of the Infrastructure Investment and Jobs Act, the demand for acrylates in the building industry continues to grow. U.S. manufacturers are interested in producing bioacrylate materials that comply with EPA standards. Canada relies on its construction and paper industry.
Europe Acrylate Market Insights
The European market of acrylates is developed well but still very innovative. Tough regulations related to environmental friendliness of chemicals and paints based on them imposed by the EU (REACH and VOC), are driving forces that motivate creation of efficient water-based acrylate coatings. Germany, France, and the UK are the key countries in which demand is growing. Major suppliers from Europe developing such types of acrylates as speciality and bio-acrylates include BASF and Evonik.
Middle East & Africa and Latin America Acrylate Market Insights
The acrylates market in the Middle East is emerging owing to the expansion of the petrochemical complex in countries such as Saudi Arabia, UAE, and Qatar into the specialty chemicals industry. Although the Middle East region remains a relatively small consumer, it enjoys several raw materials benefits due to easy availability of petrochemical intermediates. On the other hand, Africa's market is nascent but witnessing growth due to increasing construction activities in economies like Nigeria and South Africa.
Brazil leads the Latin American market for acrylates owing to its strong automotive and construction industries that require considerable quantities of coatings and adhesives. Argentina, Mexico, and Colombia also have their fair share of demand. Growth in the Latin American acrylates market has been spurred by increased local paint & coating producers who are moving away from imports towards locally produced acrylate formulations.
Market Dynamics
Growth Drivers: Construction activity and the shift to water-based coatings are the core growth drivers
Globally, there is a huge investment being made in construction projects, especially in Asia Pacific and North America. Such investments create direct and constant demand for acrylate-based paints, adhesives, sealants, and waterproofing systems. Each new construction project requires acrylate-based products during its many different stages. In addition, environmental laws that prohibit solvent-based coatings are compelling manufacturers to switch from solvent-based acrylic paints to water-based acrylic paints, thereby increasing the addressable market for water-based acrylates.
The Green Deal in Europe and the building efficiency measures under the Inflation Reduction Act in the United States are contributing to a favorable trend for high-performance architectural coatings. New buildings require improved insulation paints and higher-quality exterior surface coating paints, which can only be provided by acrylate-based products.
Restraints: Raw material price volatility and feedstock concentration create supply risks
The acrylates industry faces substantial risks due to fluctuation in the costs of the raw materials used in production. For instance, both propylene and acrylic acid, which form the core feedstock, are petroleum derivatives, and their prices depend on those of crude oil. Moreover, the production of acrylic acid is done at only a few facilities around the world, and thus any disruption in production owing to environmental conditions, accidents, or maintenance activities poses serious supply issues.
Opportunities: Bio-based acrylates and specialty applications in electronics and 3D printing
The development of commercially viable bio-based acrylates offers a major growth opportunity as it addresses both sustainability goals and the need to reduce dependence on petroleum feedstocks. Companies that can produce high-purity bio-based acrylic acid at competitive cost will gain significant market advantage as ESG requirements tighten. On the specialty side, UV-curable acrylates for electronics encapsulation, 3D printing resins, and optical coatings are higher-value applications growing much faster than commodity coatings and adhesives.
Recent Developments
-
2025: Dow Inc. expanded its acrylic acid and acrylate production capacity at its Texas Gulf Coast facilities, adding 200,000 metric tonnes annually to serve growing demand from the North American coatings and adhesives markets.
-
2024: Arkema completed the acquisition of specialty acrylate resin producer Covestro's resins business, expanding its portfolio of high-performance acrylate products for industrial coatings, adhesives, and electronics applications.
-
2023 (September): BASF introduced commercial production of 2-Octyl Acrylate with 73% bio-based content confirmed by C-14 analysis, marking a significant step toward sustainable acrylate production at industrial scale.
Key Players
-
BASF SE
-
Dow Inc.
-
Arkema S.A.
-
Celanese Corporation
-
Allnex Group
-
Evonik Industries AG
-
Nippon Shokubai Co. Ltd.
-
Mitsubishi Chemical Corporation
-
LG Chem Ltd.
-
CNOOC and Shell Petrochemicals
-
Formosa Plastics Corporation
-
Toagosei Co. Ltd.
-
Sasol Limited
-
Sumitomo Chemical Co. Ltd.
-
Wanhua Chemical Group Co. Ltd.
-
Solvay S.A.
-
Jiangsu Jurong Chemical Co. Ltd.
-
H.B. Fuller Company
-
Sartomer
-
DSM
Acrylate Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 13.07 Billion |
| Market Size by 2035 | USD 223.6 Billion |
| CAGR | CAGR of 6.13% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (Butyl Acrylate, Methyl Acrylate, Ethyl Acrylate, 2-Ethylhexyl Acrylate, Others) • By Application (Adhesives & Sealants, Paints & Coatings, Textiles, Plastics, Paper & Packaging, Others) • By Form (Water-Based, Solvent-Based, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | BASF SE, Dow Inc., Arkema S.A., Celanese Corporation, Allnex Group, Evonik Industries AG, Nippon Shokubai Co. Ltd., Mitsubishi Chemical Corporation, LG Chem Ltd., CNOOC and Shell Petrochemicals, Formosa Plastics Corporation, Toagosei Co. Ltd., Sasol Limited, Sumitomo Chemical Co. Ltd., Wanhua Chemical Group Co. Ltd., Solvay S.A., Jiangsu Jurong Chemical Co. Ltd., H.B. Fuller Company, Sartomer, DSM |
Frequently Asked Questions
Key players include BASF SE, Dow Inc., Arkema S.A., Mitsubishi Chemical Corporation, and Evonik Industries AG.
Key opportunities include water-based coatings, low-VOC formulations, specialty acrylates, high-performance adhesives, and sustainable packaging solutions.
Key opportunities include water-based coatings, low-VOC formulations, specialty acrylates, high-performance adhesives, and sustainable packaging solutions.
The major growth factor is the rising demand for acrylate-based adhesives, coatings, and polymers across construction, automotive, packaging, and industrial applications.
Butyl Acrylate dominated by type with 42.30% share in 2025, while Adhesives & Sealants led by application with 35.30% share. Water-Based systems dominated by form.
