
AI in Precision Medicine Market Report Scope & Overview:
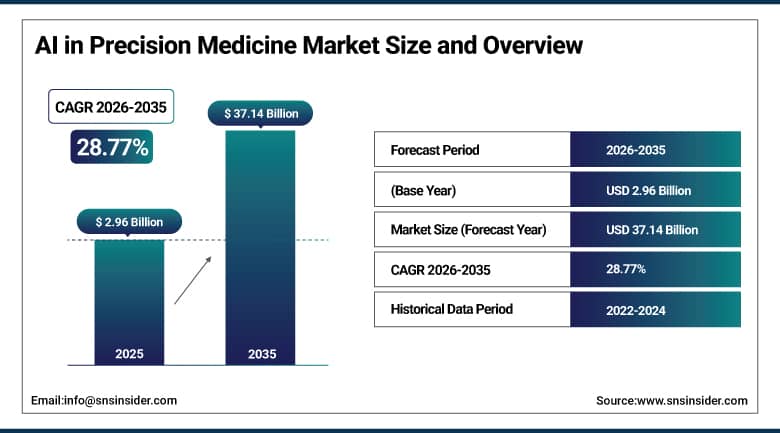
The AI in Precision Medicine Market was valued at USD 2.96 Billion in 2025 and is expected to reach USD 37.14 Billion by 2035, growing at a CAGR of 28.77% from 2026-2035.
The AI in Precision Medicine Market covers software, services and hardware that use machine learning to tailor diagnosis and treatment to a person's genes, tumor biology, lifestyle and clinical history. Algorithms read genomic sequences, pathology slides, medical images and health records to find patterns that guide drug choice and risk prediction. Falling sequencing cost, growing data sets and better computing power are the main enablers. Oncology leads adoption, and rare disease and neurology are expanding. Data privacy duties, uneven data quality and the need for regulatory validation remain obstacles. Providers, drug developers and diagnostic companies are all investing in the field.
⮞In May 2026, the World Health Assembly endorsed a resolution on precision medicine that commits member states to national policies, infrastructure and workforce, and asks the World Health Organization to prepare a global strategy. The decision signals growing government backing for data-driven personalized care.
To Get More Information On AI in Precision Medicine Market - Request Free Sample Report
AI in Precision Medicine Market Trends:
-
Foundation models trained on genomic, pathology and clinical data
-
AI-assisted digital pathology moving into routine cancer diagnosis
-
Liquid biopsy and multi-cancer detection tests paired with machine learning
-
Population genomics programs creating large, linked health data sets
-
Generative AI agents supporting variant interpretation and trial matching
U.S. AI in Precision Medicine Market Outlook:
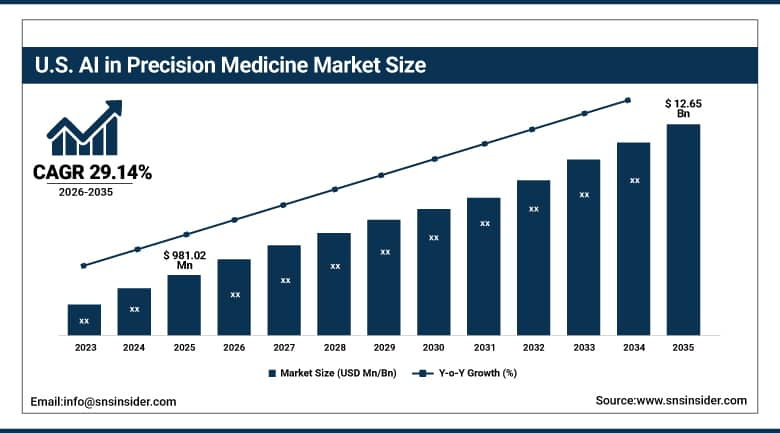
The U.S. AI in Precision Medicine Market was valued at USD 981.02 Million in 2025 and is expected to reach USD 12.65 Billion by 2035, growing at a CAGR of 29.14% from 2026-2035.
The U.S. AI in Precision Medicine Market is the largest national market, supported by large cancer centers, many genomic testing companies and a deep base of digital health investors. Hospitals use algorithms for tumor profiling, pathology review and risk scoring, while drug developers use them to select patients for trials. The Food and Drug Administration has cleared a growing list of software-based devices, which gives buyers more confidence. Payment for advanced tests is improving but remains uneven. Privacy rules and the need for diverse training data shape product design. Federal research programs also supply data at scale.
⮞In early 2026, the U.S. Food and Drug Administration reported that its drug center approved 46 novel drugs in 2025, and that 50% of them treat rare or orphan diseases. The mix of targeted and rare-disease approvals shows the pipeline that precision tools help to serve.
AI in Precision Medicine Market Segment Analysis:
-
By Component, the Software segment dominated the AI in Precision Medicine Market with approximately 41.50% share in 2025, while the Services segment is the fastest growing with a CAGR of approximately 31.26%.
-
By Technology, the Deep Learning segment dominated the AI in Precision Medicine Market with approximately 33.86% share in 2025, while the Natural Language Processing segment is the fastest growing with a CAGR of approximately 31.08%.
-
By Application, the Oncology segment dominated the AI in Precision Medicine Market with approximately 30.74% share in 2025, while the Neurology segment is the fastest growing with a CAGR of approximately 31.37%.
-
By End User, the Healthcare Providers segment dominated the AI in Precision Medicine Market with approximately 41.20% share in 2025, while the Pharma & Biotech segment is the fastest growing with a CAGR of approximately 30.77%.
By Component, Software Dominates the AI in Precision Medicine Market and Services Grows Fastest
Software leads because it holds the core intelligence of the field, including variant interpretation engines, pathology algorithms, risk models and data platforms. Hospitals, laboratories and drug developers license these tools on subscription or per-test terms, and updates add new capabilities without new hardware. Software also scales across customers at low marginal cost, which attracts investment. Integration with electronic records and laboratory systems makes products sticky once adopted. Vendors keep adding cloud features, workflow tools and reporting modules that raise the value of each license. Subscription pricing also gives vendors predictable revenue to fund research.
Services are the fastest growing component as providers and drug developers need help with data curation, model validation, clinical integration and ongoing monitoring. Few hospitals have in-house teams that can build and maintain algorithms, so they buy managed analytics, annotation and consulting. Pharmaceutical firms outsource patient selection and biomarker work to specialist providers. Regulators also expect documentation and post-market monitoring, which creates recurring service needs. Hardware, such as sequencers and scanners, remains essential but grows more slowly. Specialist firms with clinical staff are especially valued for this work.
⮞In May 2026, Caris Life Sciences said it had profiled more than 1.07 million cases, supporting its AI Insights and multimodal MI Clarity offerings. The scale of profiled data shows how services and software work together.
By Technology, Deep Learning Dominates the AI in Precision Medicine Market and Natural Language Processing Grows Fastest
Deep learning leads because it performs best on the image and sequence data that drive precision medicine. Neural networks read pathology slides, radiology scans and genomic sequences, and find patterns that older statistical methods miss. Vendors use these models to classify tumors, predict treatment response and flag rare variants. Large public and private data sets, along with cheaper computing, have made training practical. Foundation models extend the approach by learning from many data types at once and then being tuned for specific tasks. Hospitals also value that these models improve as more cases are added.
Natural language processing is the fastest growing technology as clinical notes, pathology reports and trial records hold much of the information needed for treatment decisions. Language models extract genes, stages and prior therapies from free text, match patients to trials and draft summaries for tumor boards. Generative tools are lowering the effort needed to organize unstructured records. Accuracy, traceability and privacy remain concerns, so vendors add checks and human review. Adoption is rising quickly as hospitals test assistants in daily workflow. Vendors are tailoring models to medical vocabulary to improve reliability.
⮞In May 2025, the National Institute for Health and Care Excellence backed the DERM autonomous skin cancer tool, which has been used at 26 NHS sites with more than 165,000 patients and a reported 99.8% negative predictive value for melanoma. The backing shows a growing path to payer acceptance for AI.
By Application, Oncology Dominates the AI in Precision Medicine Market and Neurology Grows Fastest
Oncology leads because cancer care already depends on molecular testing, imaging and pathology, which are well suited to machine learning. Tumor profiling guides targeted therapy and immunotherapy choices, and algorithms help interpret complex results. Drug developers use AI to find biomarkers and select trial participants. Payers and regulators have accepted several oncology tests, which supports revenue. The volume of new cases adds steady demand, and the field attracts the largest share of venture and corporate funding in the sector. Strong evidence from trials further supports use in this field.
Neurology is the fastest growing application as ageing populations raise the burden of Alzheimer's disease, Parkinson's disease and other conditions. AI is used to read brain scans, analyze blood and spinal fluid markers, and predict progression. New disease-modifying drugs increase the need to identify the right patients early. Digital biomarkers from wearables add further data. Research is still maturing, and validation is harder than in cancer, but investment is rising. Cardiology, respiratory and rare disease uses also advance steadily. Early diagnosis is therefore a key aim of new programs.
⮞In January 2026, the American Cancer Society projected 2,114,850 new cancer cases and 626,140 cancer deaths in the United States in 2026. The scale of disease keeps oncology at the center of demand.
By End User, Healthcare Providers Dominates the AI in Precision Medicine Market and Pharma & Biotech Grows Fastest
Healthcare providers lead because hospitals, cancer centers and laboratories apply the tools to patient care every day. They use AI to read pathology slides, interpret genomic reports, prioritize cases and support tumor boards. Health systems are building molecular and digital pathology programs, and many partner with technology vendors. Reimbursement for tests and the efficiency gains from faster reads support spending. Providers also hold the clinical data that make models better, which keeps them central to the ecosystem. Large systems can also test tools across many sites.
Pharma and biotech companies are the fastest growing end users as they apply AI across target discovery, biomarker development, trial design and companion diagnostics. Using algorithms to find patients most likely to respond can cut trial cost and raise the chance of approval. Partnerships with data and technology firms are growing, and some drug makers are buying diagnostic AI companies outright. Academic institutes and contract research organizations also use these tools, though their budgets are smaller. Success stories are encouraging more firms to build internal teams.
⮞In September 2025, the U.S. Office of the National Coordinator for Health Information Technology reported that 71% of non-federal acute care hospitals used predictive AI integrated with their electronic health records in 2024. The adoption level shows growing comfort with AI inside clinical systems.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
U.S. |
79.47 |
|
Europe |
Germany |
22.64 |
|
Asia Pacific |
China |
38.19 |
|
Latin America |
Brazil |
47.52 |
|
Middle East & Africa |
Saudi Arabia |
36.85 |
North America AI in Precision Medicine Market Insights
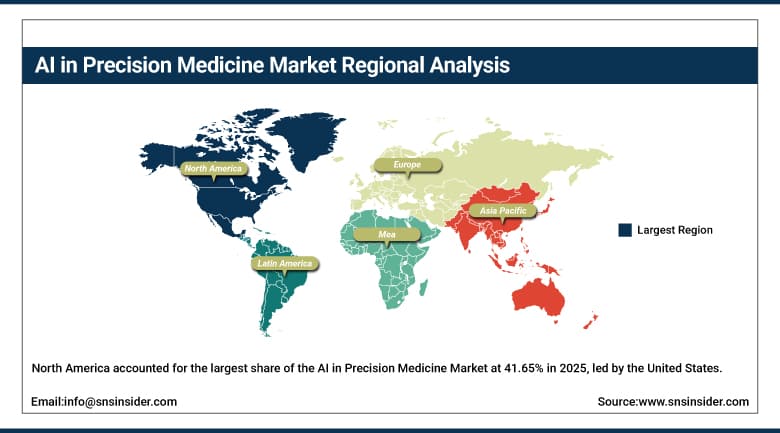
North America accounted for the largest share of the AI in Precision Medicine Market at 41.65% in 2025, led by the United States. The region has leading cancer centers, large genomic testing firms, strong venture funding and a concentration of cloud and chip companies. Canada adds demand through provincial genomics programs and research hospitals. Pharmaceutical headquarters in the region also bring a steady flow of partnerships with AI developers. Large health systems in the region often act as early adopters.
Data resources and regulation shape growth. Large national research programs give scientists access to genomic and health records at scale, and the Food and Drug Administration has set out a framework for clearing software that learns over time. Privacy law and cyber risk require careful handling of patient information. Payment for advanced testing is improving, though coverage varies by plan. Academic medical centers continue to publish validation studies that support wider clinical use. Investors in the region also remain active despite higher interest rates.
⮞In June 2026, the National Institutes of Health reported that its All of Us Research Program had enrolled more than 883,000 participants and released over 535,000 whole genomes. The data set is one of the largest linked genomic and health resources in the world.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe AI in Precision Medicine Market Insights
Europe AI in Precision Medicine Market in 2025 is led by Germany, the United Kingdom, France, Switzerland and the Nordic countries. National health systems fund genomic medicine programs, and strong pharmaceutical and diagnostic industries add demand. The United Kingdom has a long record in population genomics, while Germany and France are building hospital data platforms. Startups in London, Paris, Zurich and Copenhagen supply specialized software. Cross-border research networks add further depth.
Regulation is both a guide and a challenge. The European Union's rules on medical devices and artificial intelligence set clear duties for safety and transparency, which can lengthen development but also build trust. Data protection law governs how patient information can be shared across borders, so federated approaches are popular. Health technology assessment bodies are starting to evaluate AI tools for value, and shared European data spaces for health are in development. Smaller companies sometimes find compliance costly.
⮞In July 2025, Genomics England said it was completing a study of 100,000 newborn genomes and that its research library would hold over 500,000 whole genomes by 2030. The effort builds a data base that AI developers can use.
Asia Pacific AI in Precision Medicine Market Insights
Asia Pacific is projected to be the fastest growing region, with a CAGR of 30.35% during 2026-2035 and a 22.00% share in 2025. China, Japan, South Korea, India, Singapore and Australia lead. China has large genomics companies and a vast pool of hospital data, Japan and South Korea have strong imaging and device industries, and Singapore runs a national precision medicine program. India is growing as a center for software development and diagnostic services. Hospital chains in the region are adopting cloud tools quickly.
Programs implemented by governments and the large number of patients account for the speed. Quite a number of nations have introduced national genome projects and digital health records. The increase in cancer cases due to aging necessitates early detection and treatment. Firms in the regions are developing models based on Asian people, thus addressing the limitations posed by data obtained from Western patients. Divergent regulatory policies and reimbursement mechanisms in different markets hamper their adoption, although cloud adoption is becoming increasingly faster. Increased incomes also facilitate private financing.
⮞In August 2026, Singapore's National Precision Medicine program listed its second phase, PRECISE-SG100K, as covering about 100,000 residents. The scale supports local development of AI for genomics.
MEA & Latin America AI in Precision Medicine Market Insights
In Latin America, Brazil, Mexico, Argentina and Chile lead, with private hospital groups and research institutes adopting genomic and imaging AI. Public health systems face budget limits, but national cancer programs and academic partnerships are creating pilots. Language-specific data and local validation studies are growing needs. Private insurers are beginning to cover selected genomic tests.
In the Middle East, Saudi Arabia, the United Arab Emirates and Qatar are investing in genomic medicine, digital health and national data platforms as part of wider economic programs. Population genome projects and newborn screening are early anchors for AI. In Africa, South Africa leads, while projects elsewhere focus on infectious disease and limited-resource diagnostics. Shortages of trained specialists, uneven connectivity and funding gaps hold back wider adoption. International partnerships bring expertise and equipment into these markets.
⮞In August 2025, the Department of Health in Abu Dhabi launched a newborn genetic screening program using whole genome sequencing for more than 815 treatable childhood conditions. The program shows how Gulf health authorities are building genomic foundations.
Market Dynamics:
Growth Drivers: Genomic Data Growth and Clinical Sequencing Demand Drive Growth in the AI in Precision Medicine Market
Genomic data growth is the foundation of demand. Sequencing cost has fallen steeply, so hospitals, laboratories and national programs now generate far more data than people can analyze by hand. Algorithms turn raw sequences, images and records into usable findings, and each new data set improves model quality. Cancer centers rely on these tools to match patients to targeted drugs and trials, and drug makers use them to find biomarkers. The result is a cycle in which more data creates better tools and wider use. Cloud platforms make this analysis affordable for smaller institutions.
Policy support and clinical proof add momentum. Governments are funding national genomics programs and endorsing precision medicine as a health priority. Validation studies show gains in diagnostic accuracy and speed, and regulators have cleared a growing set of software-based devices. Payers are beginning to cover advanced tests when evidence is strong. Investment from technology firms, drug companies and venture funds supplies capital for platforms, while cloud computing makes sophisticated analysis available to smaller institutions. Medical societies are also publishing guidance that encourages appropriate use.
Restraints: Data Privacy Risk and Validation Hurdles Restrain Growth in the AI in Precision Medicine Market
There is risk of privacy of personal data. Data such as genomic data and health records are very sensitive, hence breaches may not only affect patients but providers are also penalized. Hospitals tend to be reluctant in sharing data with third-party developers, and international transfers may be limited by regulations. Security assessment takes time and adds up to costs in every deal. Misuse of genetic information by developers may also influence patient consent, which reduces the size and diversification of training datasets. Every project requires additional expenditure in terms of compliance personnel and legal review.
Validation and quality issues pose more restrictions. The model may operate less effectively in other populations or hospitals. Thus, developers need to prove their effectiveness in every setting. Validation and monitoring are required by regulators. It takes much longer to develop such a solution. Clinicians may not trust opaque algorithms, and the system is hard to integrate into old medical record software. Coverage of AI-assisted test is uneven, and some smaller hospitals may not have enough personnel to adopt the technology. Adoption of the technology is hindered due to these barriers even if the technology itself is good.
⮞In early 2026, HIPAA Journal reported, using data from the U.S. Department of Health and Human Services Office for Civil Rights, 710 healthcare data breaches of 500 or more records in 2025, affecting at least 61.56 million people. The scale of exposure explains provider caution around sensitive data.
Opportunities: Multi-Cancer Detection and Digital Pathology Create Opportunities in the AI in Precision Medicine Market
Multi-cancer detection and liquid biopsy offer a major opportunity. Blood tests that read tumor DNA fragments depend on machine learning to separate faint cancer signals from background noise. Success in regulatory review would open large screening markets, and each test generates data that improves later models. Companion diagnostics paired with new drugs add further demand. Health systems and employers may adopt screening programs if evidence on outcomes and cost is strong. Partnerships with large health systems help gather outcome data.
Digital pathology and generative AI present additional potential. As laboratories scan slides and store them digitally, algorithms can screen cases, quantify biomarkers and support pathologists facing shortages. Generative assistants can summarize records, draft reports and match patients to trials, lowering administrative load. Rare disease diagnosis, pharmacogenomics and emerging markets in Asia and the Gulf offer more room to grow. Partnerships between drug makers and AI developers can speed these uses into clinical practice. Pathologist shortages in many countries strengthen the case.
⮞In August 2026, GRAIL reported that it had submitted its premarket approval application for the Galleri multi-cancer test and that second quarter test volume exceeded 61,000, up 35%. The filing shows how close AI-assisted screening is to broader use.
Recent Developments:
-
In May 2026, Roche announced a definitive agreement to acquire PathAI, adding the AISight image management system and AI companion diagnostic algorithms, for USD 750 million upfront and up to USD 300 million in milestones. The deal is expected to close in the second half of 2026.
-
In January 2026, Freenome expanded its artificial intelligence work with NVIDIA, including a fragment-level deep learning model for cell-free DNA and an open cfDNA methylation foundation model. The company expects an FDA decision on its colorectal screening test in the second half of 2026.
-
In April 2026, Lunit received FDA clearance for Lunit INSIGHT DBT, its AI for 3D mammography, and reported use at more than 300 screening sites in the Americas. The clearance extends its breast cancer screening portfolio.
AI in Precision Medicine Market Key Players are:
-
Tempus AI, Inc.
-
Illumina, Inc.
-
SOPHiA GENETICS SA
-
Caris Life Sciences, Inc.
-
Owkin
-
PathAI, Inc.
-
Lunit Inc.
-
Freenome Holdings, Inc.
-
GeneDx Holdings Corp.
-
QIAGEN N.V.
-
DNAnexus, Inc.
-
F. Hoffmann-La Roche Ltd
-
Ibex Medical Analytics
-
NVIDIA Corporation
-
Google DeepMind
AI in Precision Medicine Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 2.96 Billion |
| Market Size by 2035 | USD 37.14 Billion |
| CAGR | CAGR of 28.77% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Component (Software, Services, and Hardware) • By Technology (Deep Learning, Machine Learning, Natural Language Processing, and Others) • By Application (Oncology, Neurology, Cardiology, Respiratory, and Others) • By End User (Healthcare Providers, Pharma & Biotech, Academic & Research Institutes, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Tempus AI, Inc., Illumina, Inc., SOPHiA GENETICS SA, Caris Life Sciences, Inc., Owkin, PathAI, Inc., Lunit Inc., Freenome Holdings, Inc., GeneDx Holdings Corp., QIAGEN N.V., DNAnexus, Inc., F. Hoffmann-La Roche Ltd, Ibex Medical Analytics, NVIDIA Corporation, Google DeepMind |

Frequently Asked Questions
Key players include Tempus AI, Illumina, SOPHiA GENETICS, Caris Life Sciences, Owkin, PathAI, Lunit, Freenome, GeneDx, QIAGEN, DNAnexus, Roche, Ibex Medical Analytics, NVIDIA and Google DeepMind.
Key opportunities include multi-cancer detection and liquid biopsy, digital pathology, generative AI assistants for records and trial matching, and growth in Asia and the Gulf.
Rapid growth in genomic and clinical data, falling sequencing cost and rising clinical validation are the main growth factors, supported by government programs.
By Component, the Software segment dominated the market in 2025 with an estimated 41.50% share, supported by its role as the core intelligence layer for diagnosis and treatment decisions.
North America dominated the market with a share of 41.65% in 2025, driven by leading cancer centers, genomic testing firms and strong funding.
