
Aseptic Packaging Market Report Scope & Overview:
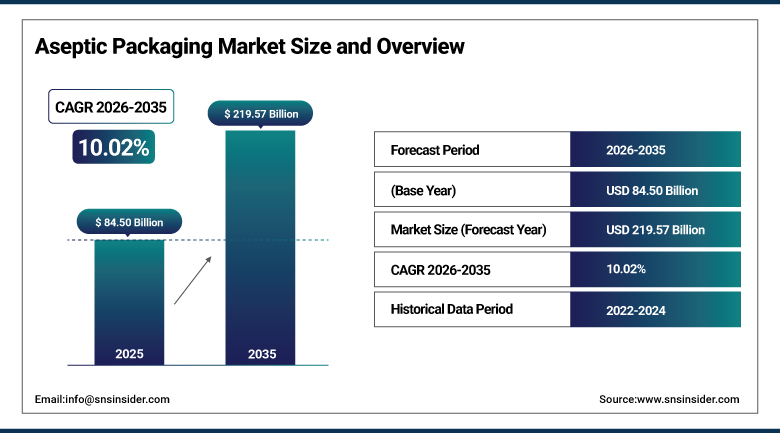
The Aseptic Packaging Market was valued at USD 84.50 Billion in 2025 and is expected to reach USD 219.57 Billion by 2035, growing at a CAGR of 10.02% from 2026-2035.
The Aseptic Packaging Market growth is being driven primarily by escalating demand for packaged food and beverage items that can be retained without refrigeration for extended periods while preserving flavor, texture, and nutritional content. Aseptic packaging is a specialized manufacturing method in which food, pharmaceutical, or other products are sterilized separately from the packaging material and then filled into pre-sterilized containers under sterile conditions, keeping the product sterile outside of refrigeration for at least six months in many applications. Rising consumption of packaged food and beverages across increasingly urbanized populations continues to expand demand for advanced aseptic packaging technologies across both developed and emerging markets. Growing emphasis on food safety, hygiene, and contamination-free packaging solutions continues to establish aseptic packaging as a preferred choice for manufacturers, while the introduction of eco-friendly and renewable packaging materials continues to reduce the format's environmental footprint relative to earlier generations of aseptic packaging technology.
On April 30, 2025, Amcor plc completed its merger with Berry Global Group, Inc., combining two major global packaging suppliers into a company generating approximately USD 23 billion in annualized sales across more than 400 locations in over 40 countries. The merger reflects the scale of consolidation occurring among global packaging suppliers as companies pursue combined manufacturing footprints, expanded material science capability, and greater supply chain redundancy to serve food, beverage, and pharmaceutical customers increasingly focused on geographic diversification and sustainability performance.
To Get more information Aseptic Packaging Market - Request Free Sample Report
Aseptic Packaging Market Trends
-
Rising adoption of renewable and recyclable aseptic carton materials to reduce reliance on aluminum foil barrier layers.
-
Growing partnership activity between packaging suppliers and beverage brands to co-develop sustainable aseptic formats.
-
Expanding use of aseptic packaging in plant-based beverage and dairy alternative product categories.
-
Increasing demand for ready-to-use aseptic vial and prefilled syringe formats in pharmaceutical manufacturing.
-
Rising automation and digitalization within aseptic filling lines to improve throughput and contamination control.
-
Growing regional manufacturing investment to reduce cold-chain dependence in emerging food and beverage markets.
U.S. Aseptic Packaging Market Outlook
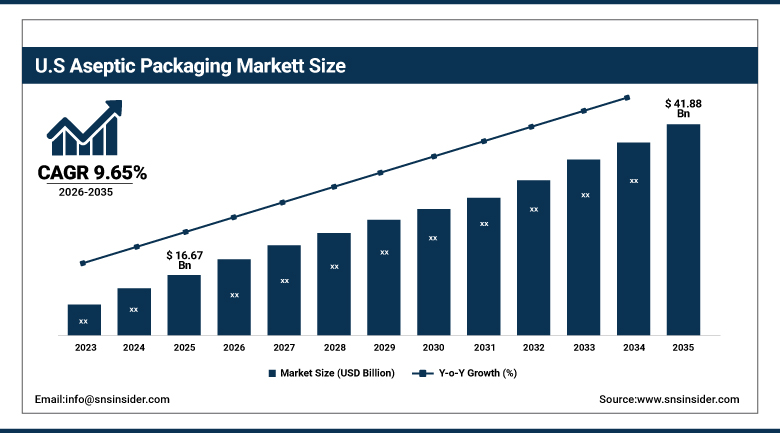
The U.S. Aseptic Packaging Market was valued at USD 16.67 Billion in 2025 and is expected to reach USD 41.88 Billion by 2035, growing at a CAGR of 9.65% from 2026-2035.
The growth of the U.S. Aseptic Packaging Market is consistently bolstered by consistent consumer preference for shelf stable dairy, juice, and plant-based beverages along with the existence of a strong domestic pharmaceutical industry which needs sterilized packaging options. The domestic packaging manufacturers have been working towards increasing the production capacity for decreasing dependency on the cold chain refrigeration system, thus serving the needs of the country’s huge ambient grocery retail channel. Increased consumer preference for plant-based beverages and functional nutrition products is continuously enlarging the market potential for aseptic carton/bottle packaging outside the traditional application of dairy products.
Elopak AS invested NOK 400 million in its Commerce, California facility to build capacity for direct consumption of ambient dairy and plant-based beverages in North America, reducing the company's dependence on trans-Atlantic supply chains to serve domestic customers. The investment illustrates how established aseptic carton suppliers continue to localize North American production capacity to better serve the region's growing demand for shelf-stable dairy and plant-based beverage packaging while improving supply chain resilience.
Aseptic Packaging Market Segment Analysis
-
By Type, the Cartons segment dominated the Aseptic Packaging Market with approximately 34.60% share in 2025, while the Bags & Pouches segment is the fastest growing with a CAGR of approximately 11.80%.
-
By Material, the Plastic segment dominated the Aseptic Packaging Market with approximately 44.60% share in 2025, while the Paper & Paperboard segment is the fastest growing with a CAGR of approximately 10.80%.
-
By Application, the Food & Beverage segment dominated the Aseptic Packaging Market with approximately 68.60% share in 2025, while the Pharmaceutical segment is the fastest growing with a CAGR of approximately 12.40%.
By Type, Cartons Dominates the Aseptic Packaging Market and Bags & Pouches Grows Fastest
Cartons are dominating the market as they are lightweight, cost effective, and have high resistance against contamination. Thus, they are the favored choice in large-scale dairy, juice, and plant-based beverages packaging. They are made from paper and paperboard, which makes them easier to recycle and adds value to their already dominant position as the largest aseptic packaging.
Bags and pouches account for the fastest-growing aseptic packaging segment as the use of flexible packaging formats continues to gain popularity for bulk food service, institutional catering, and certain consumer beverage applications due to cost and sustainability advantages over rigid formats. This growth is further bolstered by the increased demand for flexible aseptic packaging in emerging markets due to lower costs and simpler logistics.
By Material, Plastic Dominates the Aseptic Packaging Market and Paper & Paperboard Grows Fastest
Plastic has been dominating the market due to its versatility, durability, and contamination-resistant nature among various other types of aseptic packaging such as bottles, pouches, and pharmaceutical packages. Compatibility with high-speed packaging machinery as well as the consistent barrier properties of plastic continue to ensure plastic's dominance among all other materials despite the sustainability drive which advocates for more usage of paper and paperboard products.
Paper and paperboard products represent the fastest-growing material category, as sustainable carton-based aseptic packaging solutions have been gaining increasing popularity in dairy, beverages, pharmaceutical, and plant-based food products. The main driving force behind the growth of the material is the recycling advantages, lightness, and compatibility with ambient long-life packaging systems. This is also due to continued investments by packaging manufacturers into fully recyclable cartons with barrier layers other than aluminum foil.
By Application, Food & Beverage Dominates the Aseptic Packaging Market and Pharmaceutical Grows Fastest
The food and beverage applications hold the largest share of the market, given the size of the global packaged food and beverages industry, along with the high dependency of the beverages industry on aseptic packaging owing to the need for shelf stability of dairy, juice, and plant beverages without the requirement of refrigeration. The growing demand from emerging economies is further boosting the size of this segment due to the spread of ambient logistics capabilities to aseptic packaging.
The pharmaceutical applications form the fastest growing segment as the growing medical industry is in need of aseptic packaging for the containment of injectables, vaccines, and other such formulations. The growing production of vaccines and growing preference of ready to use pharmaceutical packaging is driving the growth of this segment at a higher pace than the overall market growth.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
43.60% |
|
North America |
United States |
82.60% |
|
Europe |
Germany |
28.60% |
|
Middle East & Africa |
United Arab Emirates |
25.40% |
|
Latin America |
Brazil |
30.20% |
North America Aseptic Packaging Market Insights
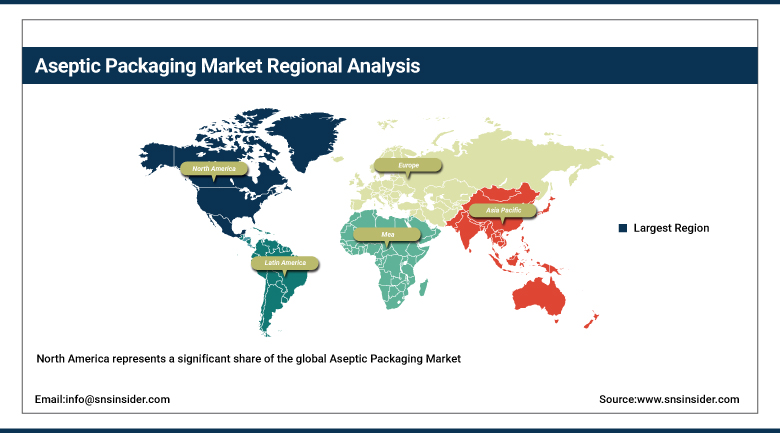
North America represents a significant share of the global Aseptic Packaging Market, anchored by the United States' advanced aseptic packaging capabilities, strong economic growth, and high demand from multiple end-use industries spanning dairy, beverage, and pharmaceutical manufacturing. The region's large ambient grocery retail channel continues to support strong demand for shelf-stable aseptic carton and bottle formats.
Canada and Mexico are contributing incremental demand as regional food and beverage manufacturing supply chains continue to integrate aseptic packaging capacity. Continued domestic investment in localized aseptic packaging production, aimed at reducing dependence on international supply chains, is expected to sustain steady regional growth through the forecast period.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Aseptic Packaging Market Insights
The European region constitutes a considerable portion of the global market for Aseptic Packaging, thanks to the substantial food and beverage manufacturing base in Germany and the concentration of leading aseptic packaging technology companies in Europe. The European companies are taking the lead in creating new forms of sustainable, recyclable aseptic carton packages in accordance with strict regional policies on packaging waste management and recyclability.
France, the UK, and Italy are contributing steadily to increasing demands for aseptic packaging in the region as food and beverage producers in the region expand the application of sustainable aseptic packaging from their premium products to mainstream products.
Asia Pacific Aseptic Packaging Market Insights
Asia Pacific was both the largest and fastest-growing regional market in 2025, expanding at a CAGR of approximately 11.20% from 2026 to 2035, driven by rapid urbanization activities and expanding manufacturing capabilities across the region. Rising per-capita purchases of packaged foods within urbanizing, middle-income populations continue to drive historically carton-underpenetrated markets toward broader aseptic packaging adoption across China, India, and Southeast Asian markets.
China's large domestic dairy, beverage, and pharmaceutical manufacturing base continues to anchor regional demand, while Japan and South Korea contribute additional scale through established food technology sectors. Continued expansion of ambient distribution infrastructure, combined with reduction of cold-chain refrigerated formats in favor of non-refrigerated ambient packaging across the region's food, dairy, and beverage distribution, is expected to sustain Asia Pacific's position as the largest and fastest-growing market through the forecast period.
MEA & Latin America Aseptic Packaging Market Insights
The Middle East & Africa market remains comparatively small but is expanding as growing food and beverage sector investment across the United Arab Emirates and Saudi Arabia sustains demand for shelf-stable packaging suited to the region's distribution and climate conditions. Regional manufacturing capacity remains limited, with much of the region's aseptic packaging supply continuing to be imported from Asian and European manufacturers.
Latin America's market is led by Brazil, where a substantial domestic dairy and beverage manufacturing base sustains steady demand for aseptic packaging across both food and pharmaceutical applications. Mexico is contributing significant growth as nearshoring-driven investment expands regional food and beverage manufacturing capacity. Across the region, adoption continues to expand as ambient distribution infrastructure reduces reliance on cold-chain logistics.
Market Dynamics
Growth Drivers: Packaged Food Demand and Food Safety Emphasis Fuels Market Growth
Increasing demands for packaged food products that can remain without refrigeration, while retaining taste, consistency, and nutrition are considered the main factors contributing to the expansion of Aseptic Packaging Market since the consumption of packaged foods and beverages is increasing amid growing urban populations which are expanding the market opportunities for technologically advanced aseptic packaging solutions. Such demands are also driven by the convenience of aseptic packaging among on-the-go consumers across developed and emerging markets.
Food safety, hygiene, and contamination-free packaging solutions are seen as another key driver behind the growth of the market since companies working in the food, beverage, and pharmaceutical sectors consider aseptic technology as the most efficient solution capable of keeping the product sterile even without refrigeration for an extended period of time. Increased production of vaccines and drugs is adding to this trend.
Restraints: High Initial Investment and Stringent Regulatory Requirements Hamper the Market Growth
High initial investment costs for aseptic packaging systems represent a meaningful restraint on market growth, as the specialized sterilization and filling equipment required for aseptic production demands substantial capital investment that can be prohibitive for smaller manufacturers, particularly in price-sensitive emerging markets. This cost consideration constrains the pace at which aseptic packaging technology can extend beyond well-capitalized global and regional manufacturers.
Stringent regulatory requirements governing aseptic packaging and filling processes represent a further restraint, as manufacturers must navigate complex, often region-specific compliance requirements around sterilization validation, material safety, and contamination control. This regulatory complexity is particularly pronounced for pharmaceutical applications, where evolving good manufacturing practice requirements continue to raise the qualification bar for both new and established aseptic packaging suppliers.
Opportunities: Sustainable Carton Innovation and Plant-Based Beverage Expansion Boost Market Expansion
Continued innovation in renewable and recyclable aseptic carton materials represents a substantial opportunity, as suppliers develop polymer-based and mono-material barrier alternatives to replace traditional aluminum foil layers while maintaining equivalent contamination protection. Suppliers that can achieve recyclability certification while preserving barrier performance are positioned to capture premium positioning from food and beverage brands pursuing sustainability commitments.
The continued expansion of plant-based beverage and dairy alternative product categories offers a further avenue for growth, as these products increasingly rely on aseptic packaging to achieve ambient shelf stability without refrigeration. Suppliers that can develop cost-competitive aseptic packaging formats suited to the specific viscosity and barrier requirements of plant-based beverages are well positioned to capture demand from this rapidly expanding product category.
Recent Developments:
-
2024: Tetra Pak partnered with Danone to co-develop a new line of fully renewable aseptic packaging aimed at reducing carbon footprint and enhancing sustainability in beverage packaging.
-
2024: Tetra Pak partnered with a leading European juice, soft drinks, and alcohol-free beverage company to create the new Tetra Prisma Aseptic 300 Edge beverage carton.
-
2025: Amcor launched its AmLite HeatFlex Recyclable platform, a mono-material high-barrier packaging solution for food and beverage applications supported by APR Critical Guidance recyclability qualification.
-
2024: Nipro PharmaPackaging launched its Direct-to-Fill glass vial platform, powered by Stevanato Group's EZ-fill technology, offering a high-quality ready-to-use aseptic packaging solution for pharmaceutical manufacturers.
Aseptic Packaging Market Key Players
-
Tetra Pak International S.A.
-
Amcor plc
-
SIG Group AG
-
Greatview Aseptic Packaging Co., Ltd.
-
IMA Group
-
SCHOTT Pharma AG & Co. KGaA
-
Robert Bosch GmbH
-
Becton, Dickinson and Company
-
IPI SRL (Coesia Group)
-
DS Smith PLC
-
Uflex Limited
-
Elopak AS
-
CDF Corporation
-
Smurfit Kappa Group
-
Mondi PLC
-
Printpack, Inc.
-
Sealed Air Corporation
-
Krones AG
-
Syntegon Technology GmbH
-
ProAmpac LLC
Aseptic Packaging Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 84.50 Billion |
| Market Size by 2035 | USD 219.57 Billion |
| CAGR | CAGR of 10.02% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (Cartons, Bags & Pouches, Bottles & Cans, Vials & Ampoules, Others) • By Material (Plastic, Paper & Paperboard, Metal, Glass, Others) • By Application (Food & Beverage, Pharmaceutical, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Tetra Pak International S.A., Amcor plc, SIG Group AG, Greatview Aseptic Packaging Co., Ltd., IMA Group, SCHOTT Pharma AG & Co. KGaA, Robert Bosch GmbH, Becton, Dickinson and Company, IPI SRL (Coesia Group), DS Smith PLC, Uflex Limited, Elopak AS, CDF Corporation, Smurfit Kappa Group, Mondi PLC, Printpack, Inc., Sealed Air Corporation, Krones AG, Syntegon Technology GmbH, ProAmpac LLC |
Frequently Asked Questions
Key players include Tetra Pak International S.A., Amcor plc, SIG Group AG, Greatview Aseptic Packaging Co., Ltd., Elopak AS, and IMA Group, among other global packaging suppliers.
Continued innovation in renewable and recyclable aseptic carton materials and continued expansion of plant-based beverage and dairy alternative product categories represent the primary opportunities.
Growth is primarily driven by escalating demand for shelf-stable packaged food and beverage products combined with growing emphasis on food safety, hygiene, and contamination-free packaging solutions.
By Type, Cartons dominated the market with approximately 34.60% share in 2025, reflecting their lightweight, cost-effective, and contamination-resistant properties across dairy and beverage applications.
Asia Pacific dominated the market with approximately 36.80% share in 2025, supported by rapid urbanization and expanding manufacturing capabilities across the region.
