
Automated Parking System Market Report Scope & Overview:
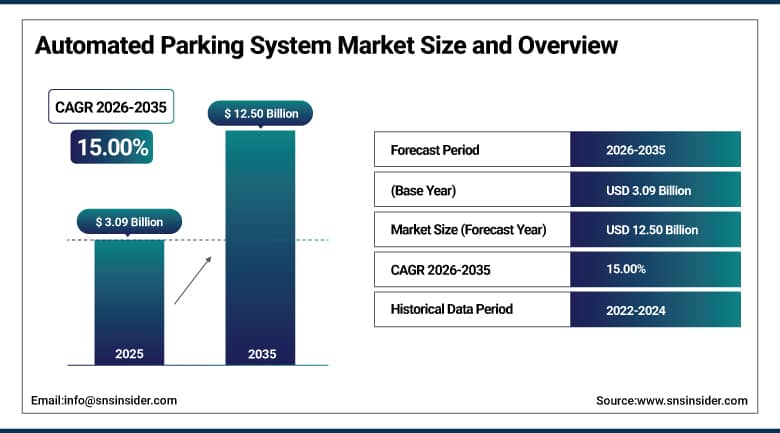
The Automated Parking System Market was valued at USD 3.09 Billion in 2025 and is expected to reach USD 12.50 Billion by 2035, growing at a CAGR of 15.00% from 2026-2035.
Automated parking solutions are considered one of the most fundamental types of modern urban infrastructure, which is composed of robotic pallets, shuttles, and lifts, alongside allocation software that stores cars vertically or horizontally without ramps and manual operation. The increasing number of privately owned passenger cars, urbanization processes, and limited available land for development in major cities ensure constant expansion of the pool of developers who need to use efficient parking infrastructure. Commercial developers, airports, and residential towers make use of such systems in order to reclaim parking capacity, reduce congestion, and increase the speed of car retrieval compared to traditional ramp garages. Future growth will be driven by integration with smart city projects, software-based allocation, and investments into urban transportation infrastructure by governments.
On March 14, 2024, Unitronics deployed a multi-level pallet transfer system in Tel Aviv featuring app-based access control and dynamic vehicle allocation calibrated to real-time traffic patterns. The company stated that the installation reflects growing demand for software-driven operational intelligence layered atop conventional mechanical retrieval hardware.
To Get More Information On Automated Parking System Market - Request Free Sample Report
Automated Parking System Market Trends:
-
Growing developer preference for shuttle and AGV-based retrieval architectures over hydraulic lift designs.
-
Rising integration of dynamic vehicle allocation software calibrated to real-time traffic and demand patterns.
-
Continued expansion of below-grade robotic installations eliminating ramp volume in dense urban plots.
-
Increasing electronic access and payment integration streamlining retrieval across commercial developments.
-
Rising preference for remote monitoring service contracts supporting guaranteed uptime commitments.
-
Growing entry of specialised software vendors pursuing transit-authority and municipal procurement contracts.
U.S. Automated Parking System Market Overview:
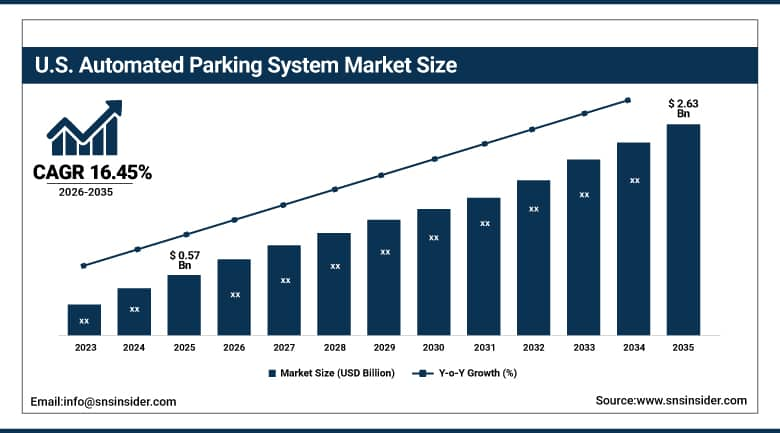
The U.S. Automated Parking System Market was valued at USD 0.57 Billion in 2025 and is expected to reach USD 2.63 Billion by 2035, growing at a CAGR of 16.45% from 2026-2035.
Domestic demand continues to be underpinned by acute land constraints in gateway cities and rapid adoption of shuttle-based retrieval hardware across both commercial and residential developments. Leading vendors continue to integrate their systems more closely with building access and payment platforms, reducing retrieval delays for end users, while municipal planning authorities keep folding automated parking into broader smart-infrastructure mandates.
On February 18, 2025, Westfalia Technologies, headquartered in York, Pennsylvania, published analysis showing that its Satellite automated storage architecture can substantially improve land utilization relative to conventional below-grade concrete garage construction. The company said the comparison isolates the ramp volume automated systems eliminate entirely.
Automated Parking System Market Segment Analysis:
-
By Automation Level, the Fully Automated segment dominated the market with a 63.80% share in 2025.
-
By Platform, the Palleted segment dominated the market with a 57.25% share in 2025, while the Non-Palleted segment is the fastest growing with a CAGR of 15.87% during 2026-2035.
-
By Structure Type, the Tower System segment dominated the market with a 37.45% share in 2025, while the Shuttle/AGV System segment is the fastest growing with a CAGR of 16.82% during 2026-2035.
-
By Component, the Hardware segment dominated the market with a 68.40% share in 2025, while the Software segment is the fastest growing with a CAGR of 17.60% during 2026-2035.
-
By End-Use, the Commercial segment dominated the market with a 41.70% share in 2025, while the Residential segment is the fastest growing with a CAGR of 16.30% during 2026-2035.
By Automation Level, Fully Automated Dominates the Market
Fully Automated systems dominated the market in 2025, a position built on their appeal for high-turnover commercial applications where no human driver enters the storage area at any point in the retrieval cycle. Developers favour these systems precisely because removing manual maneuvering allows denser vehicle packing and materially faster average retrieval times than partially automated alternatives, a combination that keeps the format central to new-build office towers, transit hubs, and large residential complexes even as component costs remain higher than simpler mechanical assistance formats.
Semi-Automated systems continue to serve a meaningful share of retrofit projects over the forecast period, where partial mechanical assistance paired with limited driver involvement avoids costlier structural modification to existing buildings. As component costs for fully automated architectures continue declining and operational track records lengthen across major markets, developers are expected to keep favouring full automation for new-build projects, gradually narrowing the addressable base for semi-automated formats.
By Platform, Palleted Dominates the Market and Non-Palleted Grows Fastest
Palleted platforms dominated the market in 2025. Decades of deployment have given system integrators and maintenance contractors deep familiarity with pallet-based retrieval mechanisms, sustaining predictable maintenance economics that continue to make this the default specification for large-scale commercial installations regardless of shifting technology trends elsewhere in the industry.
Non-Palleted platforms are projected to grow fastest over the forecast period. Growing developer interest in shuttle and robotic-arm mechanisms, which eliminate the additional mechanical step and maintenance burden that pallets introduce, continues to pull demand toward direct-lift architectures, particularly across space-constrained retrofit projects where configuration flexibility carries a premium over proven pallet-based reliability.
By Structure Type, Tower System Dominates the Market and Shuttle/AGV System Grows Fastest
Tower System structures dominated the market in 2025. Their suitability for above-ground urban plots, where vertical stacking delivers the greatest capacity gain relative to available land, combined with a long and well-documented deployment history across dense city centers, continues to give developers and financiers a comfortable basis for underwriting new tower installations.
Shuttle and AGV-based structures are projected to grow fastest over the forecast period. Their flexibility across both above-ground and below-grade configurations, paired with compatibility with increasingly sophisticated traffic-management software, continues to pull demand away from fixed tower architectures as metro rail expansions and mixed-use developments increasingly integrate parking nodes into broader transit infrastructure.
By Component, Hardware Dominates the Market and Software Grows Fastest
Hardware dominated the market in 2025. Every automated retrieval cycle, however sophisticated the coordinating software eventually becomes, still depends on a pallet, lift, or conveyor physically repositioning the vehicle, and this basic mechanical dependency continues to anchor hardware's leading position within the broader component mix even as software captures a growing share of new investment.
Software is expected to grow fastest among components over the forecast period. Rising demand for dynamic vehicle allocation, app-based access control, and predictive maintenance platforms continues to differentiate competing vendor offerings, as facility operators increasingly prioritize retrieval speed and remote monitoring capability alongside the proven mechanical reliability hardware has long provided.
By End-Use, Commercial Dominates the Market and Residential Grows Fastest
Commercial applications dominated the market in 2025. High vehicle turnover and constrained land availability across office towers, shopping complexes, airports, and hospitals continue to justify the premium cost of automated infrastructure, giving these facilities the clearest, most easily underwritten return-on-investment case within the broader end-use mix.
Residential applications are expected to be the fastest-growing end-use category over the forecast period. Rising apartment and condominium development in cities where minimum parking ratios and shrinking buildable land continue to squeeze conventional garage designs is pulling demand toward automated storage, a structural shift expected to keep reshaping end-use demand patterns well beyond the current forecast horizon.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 |
|
Asia Pacific |
China |
39.60% |
|
North America |
United States |
83.90% |
|
Europe |
Germany |
33.40% |
|
Latin America |
Brazil |
44.70% |
|
Middle East & Africa |
United Arab Emirates |
36.10% |
Asia Pacific Automated Parking System Market Insights
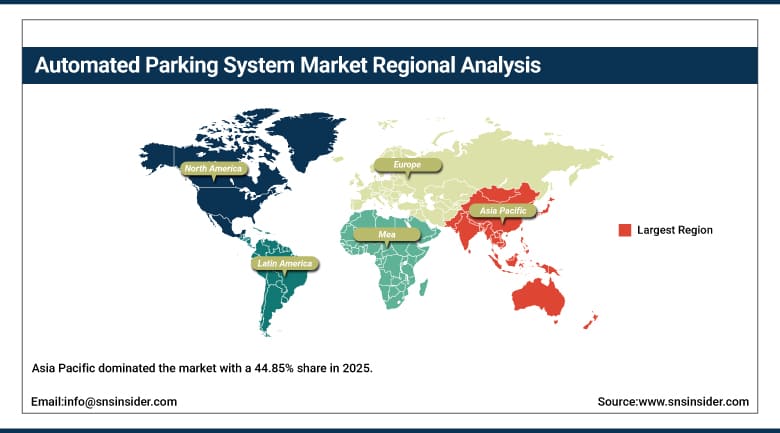
Asia Pacific dominated the market with a 44.85% share in 2025. Widespread on-street vehicle congestion, government-led urban mobility programs, and extensive high-density residential and commercial construction across the region continue to anchor this leadership position. China continues to anchor regional demand as developers expand compact, land-efficient parking infrastructure across both established metropolitan centers and rapidly growing secondary cities, supported by sustained government investment in modernising broader urban transportation networks.
Japan and South Korea contribute further depth through established, technically advanced construction sectors linking automated parking to multi-modal urban-mobility programs. India's expanding metro rail system continues adding meaningful regional growth as new transit nodes increasingly incorporate integrated parking facilities, positioning the wider region to sustain its lead through the forecast period even as North America grows faster in percentage terms.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Automated Parking System Market Insights
North America is projected to be the fastest-growing region, registering a CAGR of 16.45% during 2026-2035, supported by increasing adoption of smart parking solutions and rising demand for efficient space utilization across constrained urban plots. The United States shapes regional demand through strong activity from commercial developers, airport authorities, and residential tower operators facing shrinking buildable land in major gateway cities.
Canada contributes steady incremental demand as provincial urban planning authorities continue widening smart-infrastructure mandates across both established metropolitan areas and growing secondary cities. Continued municipal investment in space-efficient parking infrastructure is expected to keep North America ahead of other regions in percentage growth terms through the forecast period, even as Asia Pacific retains the larger overall revenue base.
Europe Automated Parking System Market Insights
Europe holds a meaningful share of the global market, underpinned by a dense concentration of established automated storage and retrieval manufacturers and continued redevelopment of historic city centers where land scarcity favours vertical parking over surface lots. Germany's substantial manufacturing base anchors regional demand, supported by decades of accumulated engineering expertise among home-market system manufacturers.
The United Kingdom, France, and other major European markets contribute consistent demand as national planning authorities keep extending automated parking specifications into routine urban redevelopment practice, reflecting the region's role as both an established manufacturing base and a mature, steadily growing end market.
MEA & Latin America Automated Parking System Market Insights
The Middle East & Africa market is supported by growing construction investment across the United Arab Emirates and Saudi Arabia, where extensive high-rise commercial and residential development continues to lift demand for space-efficient parking infrastructure across both public and private developments. Regional governments continue channeling substantial investment into modern urban infrastructure, including dedicated smart-city districts designed to reduce reliance on surface-level parking.
Latin America's market is anchored by Brazil, where a sizeable domestic construction sector sustains steady equipment demand across both commercial and residential developments. Mexico contributes further incremental growth as urban construction activity continues expanding across the broader region, though adoption of the most advanced shuttle-based systems across Latin America as a whole still lags meaningfully behind more established markets in North America and Europe.
Market Dynamics:
Growth Drivers: Urban Land Constraints and Smart City Integration
Rising urbanization and increasing vehicle ownership stand as the primary growth driver, reinforced by shrinking buildable land and municipal planning mandates that continue widening the base of developments requiring space-efficient parking infrastructure worldwide. The continued expansion of smart-city planning frameworks reinforces sustained long-term demand, as more municipalities fold automated parking directly into new development approval requirements across both developed and emerging urban centers alike.
Growing integration with transit infrastructure represents a second major driver, supported by government mobility funding initiatives and rising demand for parking capacity that extends well beyond standalone commercial developments into broader multi-modal transportation networks. Increasing prevalence of below-grade construction, paired with rising demand for systems capable of eliminating ramp volume entirely, continues to reinforce sustained market expansion across both established Western markets and rapidly developing cities.
Restraints: High Capital Costs and Integration Complexity
High capital costs remain a genuine restraint on market growth, as advanced systems built around shuttle-based retrieval and comprehensive allocation software continue to command premium pricing that smaller developers and price-sensitive markets can struggle to justify against tighter construction budgets. This cost barrier particularly affects retrofit projects in emerging markets, where the structural modification required for the most sophisticated available systems can meaningfully exceed what many developers can reasonably allocate.
Integration complexity with existing building infrastructure presents a further restraint, as the continued need to coordinate automated systems with legacy structural constraints keeps raising genuine questions around project timelines across differing regulatory regimes worldwide. This requires vendors operating internationally to sustain substantial ongoing compliance investment, spanning fire safety certification, structural approval processes, and jurisdiction-specific building codes that can meaningfully complicate deployment timelines.
Opportunities: Shuttle Technology Advancement and Transit Integration
Continued advancement of shuttle and robotic-arm retrieval technology offers a substantial opportunity, as vendors demonstrating validated, cost-competitive configuration flexibility across both above-ground and below-grade applications stand to capture meaningful new demand from developers seeking alternatives to fixed pallet-based tower systems. Developers increasingly view these architectures not as a novelty feature but as a genuine operational necessity capable of reducing maintenance burden while adapting to constrained or irregular plot geometries.
The continued integration of parking nodes within broader transit infrastructure presents a further avenue for growth, as cities continue expanding networks that incorporate automated parking directly at station nodes, giving vendors with established transit-authority relationships broader addressable reach without needing to compete purely on standalone commercial project bids.
Recent Developments:
-
In May 2024, Junction Industries acquired Skyline Parking AG, a Switzerland-based provider of automated vehicle storage and retrieval technology, extending the acquirer's advanced automation and infrastructure portfolio.
-
In February 2025, Klaus Multiparking America launched its kVario 8000 Series semi-automatic puzzle parking system, expanding the company's product lineup for the North American market.
-
In February 2025, TKH Security's Park Assist Solution was selected to provide automated parking guidance for a five-floor, 502-space parking structure, with the project expected to reach completion during the second quarter of 2025.
-
In March 2025, University Station, an apartment complex in Hollywood, Florida, selected TKH Security to implement its Park Assist automated parking guidance system across the complex's five-floor garage.
Automated Parking System Market Key Players:
-
Westfalia Technologies, Inc.
-
Unitronics (1989) (R.G.) Ltd.
-
Klaus Multiparking GmbH
-
Robotic Parking Systems, Inc.
-
City Lift Parking LLC
-
Wohr Parking Systems GmbH
-
Lodige Industries GmbH
-
ShinMaywa Industries, Ltd.
-
Skyline Parking AG
-
Dayang Parking Co.
-
FATA Automation, Inc.
-
ParkPlus, Inc.
-
Robopark BV
-
Parkmatic Systems, Inc.
-
Serva Transport Systems GmbH
-
Park Assist LLC (TKH Security)
-
Amano McGann, Inc.
-
IHI Corporation
-
Omnitec Group
-
MHE-Demag (S) Pte Ltd.
Automated Parking System Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 3.09 Billion |
| Market Size by 2035 | USD 12.50 Billion |
| CAGR | CAGR of 15.00% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Automation Level (Fully Automated and Semi-Automated) • by Platform (Palleted and Non-Palleted) • by Structure Type (Tower System, Shuttle/AGV System, Silo System, Puzzle System, and Rail Guided Cart System) • by Component (Hardware and Software) • by End-Use (Commercial, Residential, and Municipal/Public) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Westfalia Technologies, Inc., Unitronics (1989) (R.G.) Ltd., Klaus Multiparking GmbH, Robotic Parking Systems, Inc., City Lift Parking LLC, Wohr Parking Systems GmbH, Lodige Industries GmbH, ShinMaywa Industries, Ltd., Skyline Parking AG, Dayang, Parking Co., FATA Automation, Inc., ParkPlus, Inc., Robopark BV, Parkmatic Systems, Inc., Serva Transport Systems GmbH, Park Assist LLC (TKH Security), Amano McGann, Inc., IHI Corporation, Omnitec Group, MHE-Demag (S) Pte Ltd. |
Frequently Asked Questions
Key players include Westfalia Technologies, Inc., Unitronics (1989) (R.G.) Ltd., Klaus Multiparking GmbH, Robotic Parking Systems, Inc., Wohr Parking Systems GmbH, Lodige Industries GmbH, ShinMaywa Industries, Ltd., Skyline Parking AG, Park Assist LLC, and Amano McGann, Inc., among others.
Continued advancement of shuttle and robotic-arm retrieval technology and the continued integration of parking nodes within broader transit infrastructure represent the two most significant opportunities shaping the market's next phase of growth.
Growth is primarily driven by rising urbanization and increasing vehicle ownership, combined with shrinking buildable land and smart city initiatives that specify automated parking as a standard development component
By Structure Type, Tower System dominated the market with a 37.45% share in 2025, reflecting its suitability for above-ground urban plots and long deployment history.
Asia Pacific dominated the market with a 44.85% share in 2025, supported by widespread urban congestion and government-led mobility programs concentrated across China, Japan, and South Korea.
