
Automotive Airbag Fabric Market Report Scope & Overview:
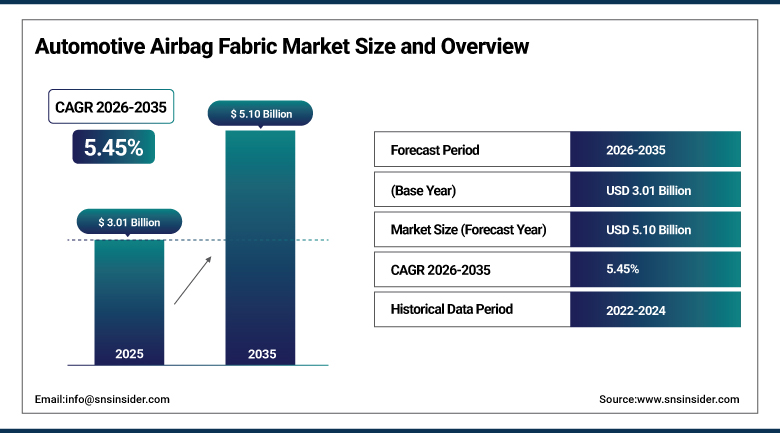
The Automotive Airbag Fabric Market was valued at USD 3.01 Billion in 2025 and is expected to reach USD 5.10 Billion by 2035, growing at a CAGR of 5.45% from 2026-2035.
Market expansion is being sustained by the steady tightening of occupant-safety regulation across both mature and emerging automotive markets, which continues to raise the minimum number of airbags mandated per vehicle and, correspondingly, the volume of specialized fabric required per unit produced. Robust SUV and light commercial vehicle production is reinforcing this trend, as larger vehicle platforms typically accommodate a greater number of airbag modules than compact passenger cars. Continuous advancement in high-tenacity weaving and silicone-coating technology is further improving gas-tight performance and fabric durability, supporting adoption of increasingly sophisticated restraint systems across premium and mainstream vehicle segments alike.
Autoliv announced in February 2025 the upcoming operation of a new airbag cushion and fabric manufacturing facility in Vietnam, designed to serve growing regional demand and strengthen production capacity across Asia. The investment reflects how closely airbag fabric supply chains are now tracking the geographic center of global vehicle production, with manufacturers positioning capacity in Southeast Asia well ahead of the region's anticipated growth in vehicle output.
To Get more information Automotive Airbag Fabric Market - Request Free Sample Report
Automotive Airbag Fabric Market Trends
-
Increasing standardization of six or more airbags across mainstream passenger vehicle trims, extending well beyond premium and luxury segments
-
Growing preference for polyester yarn among manufacturers pursuing lighter-weight, lower-carbon fabric alternatives to conventional polyamide
-
Rising adoption of silicone-elastomer coatings for their superior thermal resistance, flame resistance, and tear-strength characteristics
-
Expanding deployment of far-side and curtain airbag modules as automakers pursue higher safety ratings under evolving crash-test protocols
-
Growing integration of airbag fabric specifications into broader ADAS and connected-safety architecture on newly launched vehicle platforms
-
Continued regional capacity expansion by leading fabric manufacturers positioning production closer to fast-growing vehicle assembly hubs
U.S. Automotive Airbag Fabric Market Outlook
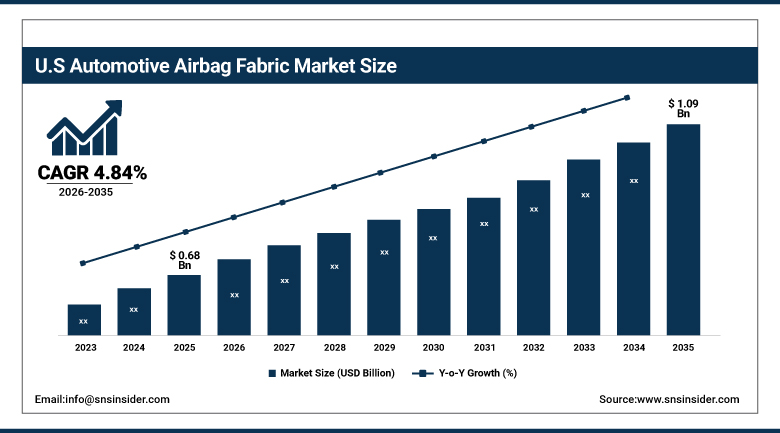
The U.S. Automotive Airbag Fabric Market was valued at approximately USD 0.68 Billion in 2025 and is expected to reach approximately USD 1.09 Billion by 2035, growing at a CAGR of approximately 4.84% from 2026-2035.
The demand environment in the U.S. has been influenced by its long-standing occupant protection guidelines at the federal level that have mandated a number of airbag modules on passenger vehicles for many years and are also supported by new crash test procedures introduced by private safety rating agencies. There is also domestic fabric volume demand resulting from the large production capacity for SUVs and light trucks in the country since these vehicle segments need more curtain and side impact airbags than compact cars.
Maruti Suzuki made six airbags standard across all variants of its Fronx model in December 2025, strengthening passive safety and enhancing occupant protection through improved restraint system architecture ahead of upcoming regulatory requirements. While the vehicle itself is manufactured in India, the decision reflects a broader global pattern of automakers standardizing airbag counts well ahead of mandatory compliance deadlines, a pattern increasingly visible across U.S.-market vehicle platforms as well.
Automotive Airbag Fabric Market Segment Analysis
-
By Airbag Type, the Front Airbag segment dominated the Automotive Airbag Fabric Market with approximately 37.83% share in 2025, while the Curtain Airbag segment is the fastest growing with a CAGR of approximately 7.50%.
-
By Fabric Type, the Flat Fabric segment dominated the Automotive Airbag Fabric Market with approximately 68.00% share in 2025, while the OPW Fabric segment is the fastest growing with a CAGR of approximately 6.80%.
-
By Yarn Type, the Polyamide segment dominated the Automotive Airbag Fabric Market with approximately 64.31% share in 2025, while the Polyester segment is the fastest growing with a CAGR of approximately 7.80%.
-
By Coating Type, the Coated segment dominated the Automotive Airbag Fabric Market with approximately 73.48% share in 2025, while the Uncoated segment is the fastest growing with a CAGR of approximately 4.61%.
-
By Vehicle Type, the Passenger Cars segment dominated the Automotive Airbag Fabric Market with approximately 66.33% share in 2025, while the Light Commercial Vehicles segment is the fastest growing with a CAGR of approximately 5.80%.
-
By Propulsion Type, the ICE segment dominated the Automotive Airbag Fabric Market with approximately 78.60% share in 2025, while the Electric segment is the fastest growing with a CAGR of approximately 7.40%.
By Airbag Type, Front Airbag dominates, Curtain Airbag grows fastest
The front airbag is still the basic safety device used in almost all passenger vehicles manufactured worldwide, a standard that has been in place consistently for decades in most of the major markets. This standardization and relative simplicity in fabrication requirements of the fabric in the front airbag continue to be factors behind its continued supremacy in the overall airbag fabric industry.
Curtain airbags have been on the rise due to the use of curtain airbags by manufacturers in meeting the stringent crash-test standards set by regulatory agencies and independent safety-rating firms for side impact and rollovers. This is mainly due to the fact that the elongated fabric used in the curtain airbags demands more intricate processing procedures than the front airbags fabric.
By Fabric Type, Flat Fabric dominates, OPW Fabric grows fastest
Flat fabric construction remains the conventional choice across the majority of airbag modules currently in production, owing to its established manufacturing processes and compatibility with standard cut-and-sew assembly methods used widely across the supply base.
One-piece woven, or OPW, fabric is gaining traction for its ability to produce a seamless, more structurally efficient airbag cushion without additional stitching, reducing potential failure points during rapid deployment. Automakers pursuing higher-performance curtain and side-impact modules are increasingly specifying OPW construction despite its comparatively higher production cost.
By Yarn Type, Polyamide dominates, Polyester grows fastest
Polyamide remains the preferred choice in most of the manufacturing of the fabric used in the airbags because of its heat and abrasion resistance, coupled with proven performance in critical deployment situations.
Polyester is also becoming popular in the automotive industry as car manufacturers look for lighter materials with reduced carbon footprint that can match the performance of polyamide in terms of standards. Technological developments in the manufacture of polyester fibers have reduced the performance gap with polyamide.
By Coating Type, Coated dominates, Uncoated grows fastest
Coated fabric remains the dominant specification, as silicone-elastomer coatings deliver the thermal resistance, flame resistance, and gas-tight sealing performance that safety-critical airbag deployment demands. Nearly all major automakers continue to rely on silicone-based coating systems for their primary restraint applications.
Uncoated fabric, while a smaller category overall, continues to find application in select lower-pressure airbag modules where coating costs can be avoided without compromising deployment safety, supporting its steady, if modest, growth trajectory relative to the broader coated segment.
By Vehicle Type, Passenger Cars dominates, Light Commercial Vehicles grows fastest
Passenger cars continue to represent the largest consumption base for airbag fabric, consistent with their outsized share of global vehicle production relative to commercial vehicle categories across nearly every major market.
Light commercial vehicles are expanding their airbag fabric consumption as fleet operators and regulatory bodies increasingly extend passenger-vehicle-grade safety standards to commercial platforms. Rising e-commerce-driven delivery fleet expansion is reinforcing this trend, as newly registered commercial vans increasingly ship with multi-airbag configurations previously reserved for passenger vehicles.
By Propulsion Type, ICE dominates, Electric grows fastest
Internal combustion engine vehicles continue to account for the majority of airbag fabric demand, a reflection of the substantially larger global vehicle parc still built around conventional powertrains, particularly across emerging economies where combustion vehicles remain the dominant new-vehicle choice.
Electric vehicles are emerging as the fastest-growing propulsion category, as EV platforms frequently launch with expanded standard safety packages intended to differentiate them competitively and offset the added structural mass of battery packs. Regulatory bodies in several major markets are also aligning EV-specific crash-safety requirements more closely with conventional vehicle standards, reinforcing this trend.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
42.30% |
|
North America |
United States |
80.60% |
|
Europe |
Germany |
26.40% |
|
Latin America |
Brazil |
34.20% |
|
Middle East & Africa |
UAE |
28.90% |
Asia Pacific Automotive Airbag Fabric Market Insights
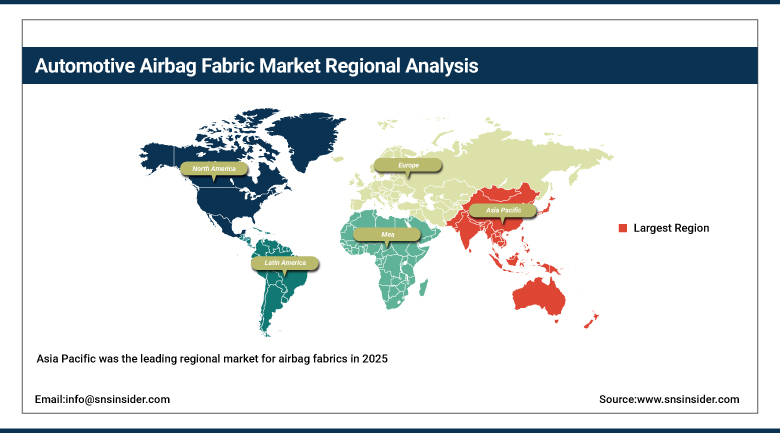
The Asia Pacific was the leading regional market for airbag fabrics in 2025 due to the presence of China as the biggest producer of automobiles in the world along with stringent safety regulations within the country, leading to an increase in the number of mandatory airbags fitted in each passenger vehicle registered. The trend of increasing regulatory momentum was more prominent in India where leading domestic producers such as Maruti Suzuki had already adopted the practice of fitting 6 airbags within their mass-produced models even before any deadline was set.
The fabric requirement in China is bolstered by the size of its own domestic automotive supply chain which increasingly consists of vertically integrated textile and coating capacity catering to domestic OEMs as well as exports. South Korea and Japan still lead in terms of technological advancement in fabric formulations for curtain airbags and far-side airbags. Southeast Asia will become a significant production base for the fabric going forward owing to the recently announced Vietnam factory of Autoliv.
Get Customized Report as per Your Business Requirement - Enquiry Now
North America Automotive Airbag Fabric Market Insights
North America represents a mature but consistently growing airbag fabric market, underpinned by federal occupant-protection standards that have mandated multiple airbag modules across passenger vehicles for an extended period. The United States accounts for the substantial majority of regional demand, supported by a large domestic SUV and light-truck production base that typically requires more extensive curtain and side-impact airbag coverage than compact vehicle platforms.
Canada contributes meaningful additional volume through its integrated automotive manufacturing sector, while Mexico continues to expand its role as a regional production hub serving both domestic demand and cross-border supply chains linking all three North American markets.
Europe Automotive Airbag Fabric Market Insights
Europe's airbag fabric demand is anchored substantially by Germany, home to several of the world's leading premium and luxury automakers whose vehicle platforms frequently specify more extensive airbag coverage, including far-side and knee airbag modules, than mass-market vehicles elsewhere. Regional demand is further reinforced by Euro NCAP's continually evolving crash-test protocols, which have progressively incentivized broader airbag deployment across vehicle categories.
France and Italy contribute additional volume through their respective domestic automotive manufacturing sectors, both of which continue to adapt product specifications to align with tightening EU passenger-safety requirements.
MEA & Latin America Automotive Airbag Fabric Market Insights
The Middle East and Africa region remains a comparatively small contributor to global demand, with the UAE accounting for the largest share of regional consumption through its growing premium vehicle retail sector, though broader regional growth continues to depend on the pace of automotive manufacturing infrastructure development across the wider region.
Latin America is led by Brazil, where expanding domestic vehicle production and tightening national crash-safety regulation are jointly supporting rising airbag fabric consumption. Mexico and Argentina contribute additional secondary demand tied to their respective automotive manufacturing sectors.
Market Dynamics
Growth Drivers: Tightening safety regulation and rising airbag counts fueling adoption
Stringent government crash-safety regulations represent the principal driver of market growth, as regulatory bodies across major automotive markets continue to raise minimum mandatory airbag counts and tighten crash-test performance thresholds that airbag fabric must satisfy. This regulatory trajectory has proven remarkably consistent across both mature and emerging markets, providing suppliers with a demand base that continues to expand independent of broader vehicle production cycles.
Rising consumer awareness of vehicle safety features constitutes a second significant growth driver, as independent crash-test ratings increasingly influence purchasing decisions and encourage automakers to standardize expanded airbag packages even ahead of formal regulatory mandates. Robust SUV and light commercial vehicle production continues to reinforce this trend, given these vehicle categories' typically higher airbag module counts.
Restraints: Raw material cost volatility and design complexity limiting margin stability
Fluctuating input costs for polyamide, polyester, and silicone coating materials represent a genuine restraint, as fabric manufacturers remain exposed to broader petrochemical commodity price movements that directly affect production economics across the supply chain. Manufacturers without long-term raw material agreements face particular exposure to these cost swings.
Increasing design complexity associated with curtain, far-side, and knee airbag modules adds a further restraint, as these specialized applications require more sophisticated weaving, coating, and quality-validation processes than conventional front airbag fabric, raising development costs and extending qualification timelines for new product introductions.
Opportunities: Lightweight material innovation and electric vehicle safety standardization opening new growth avenues
Continued advancement in lightweight, lower-carbon fabric formulations presents a meaningful opportunity for suppliers able to match polyamide's established performance characteristics using polyester or hybrid yarn constructions, particularly as automakers pursue vehicle-wide weight reduction to offset battery mass in electrified platforms.
Electric vehicle safety standardization represents a further opportunity, as automakers increasingly specify expanded airbag packages on EV platforms to differentiate competitively and align with evolving EV-specific crash-safety requirements. Suppliers capable of engineering fabric solutions optimized for EV-specific structural considerations are positioned to capture disproportionate share of this expanding segment.
Recent Developments:
-
In November 2025, Kia launched the 2026 Seltos with six airbags standard across all trims, alongside upgraded ADAS, larger infotainment displays, and enhanced safety electronics architecture, reflecting broader industry momentum toward standardized expanded restraint systems.
-
In 2025, multiple leading fabric manufacturers, including Hyosung and Toray, continued strategy-building initiatives aimed at strengthening product portfolios and expanding their competitive positioning across the global airbag fabric supply base.
Automotive Airbag Fabric Market Key Players
-
Autoliv Inc.
-
Joyson Safety Systems
-
Teijin Limited
-
Toray Industries, Inc.
-
Hyosung Corporation
-
Zhejiang Gohigh Technology Co., Ltd.
-
ZF Friedrichshafen AG
-
Toyoda Gosei Co., Ltd.
-
Kolon Industries, Inc.
-
Nishikawa Rubber Co., Ltd.
-
Trelleborg AB
-
Milliken & Company
-
Global Safety Textiles GmbH
-
Coats Group plc
-
Asahi Kasei Corporation
-
Continental AG
-
Hyundai Mobis Co., Ltd.
-
Ashimori Industry Co., Ltd.
-
Xiamen Xiangyu Automobile Airbag Co., Ltd.
-
SRI Perumal Textile Mills Pvt. Ltd.
Automotive Airbag Fabric Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 3.01 Billion |
| Market Size by 2035 | USD 5.10 Billion |
| CAGR | CAGR of 5.45% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Airbag Type (Front, Side, Curtain, Knee, Far-Side, Others) • by Fabric Type (Flat Fabric, OPW Fabric) • by Yarn Type (Polyamide, Polyester) • by Coating Type (Coated, Uncoated) • by Vehicle Type (Passenger Cars, Light Commercial Vehicles, SUVs & MPVs) • by Propulsion Type (ICE, Electric) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Autoliv Inc., Joyson Safety Systems, Teijin Limited, Toray Industries, Inc., Hyosung Corporation, Zhejiang Gohigh Technology Co., Ltd., ZF Friedrichshafen AG, Toyoda Gosei Co., Ltd., Kolon Industries, Inc., Nishikawa Rubber Co., Ltd., Trelleborg AB, Milliken & Company, Global Safety Textiles GmbH, Coats Group plc, Asahi Kasei Corporation, Continental AG, Hyundai Mobis Co., Ltd., Ashimori Industry Co., Ltd., Xiamen Xiangyu Automobile Airbag Co., Ltd., SRI Perumal Textile Mills Pvt. Ltd. |
Frequently Asked Questions
Leading companies include Autoliv Inc., Joyson Safety Systems, Teijin Limited, Toray Industries, Inc., and Hyosung Corporation, among other major airbag fabric and safety restraint manufacturers.
Opportunities include lightweight, lower-carbon fabric formulation innovation and electric vehicle safety standardization driving expanded airbag packages on EV platforms.
Growth is driven by stringent government crash-safety regulations, rising consumer awareness of vehicle safety features, and robust SUV and light commercial vehicle production.
Front Airbag dominates by airbag type with approximately 37.83% share, Flat Fabric dominates by fabric type with roughly 68.00% share, Polyamide dominates by yarn type with about 64.31% share, and Passenger Cars dominates by vehicle type with approximately 66.33% share; Curtain Airbag, OPW Fabric, Polyester, and Light Commercial Vehicles are the fastest-growing segments within their respective categories.
Asia Pacific is the largest and fastest-growing regional market, led by China, supported by tightening crash-safety regulation and the region's substantial vehicle production base.
