
Automotive Seats Market Report Scope & Overview:
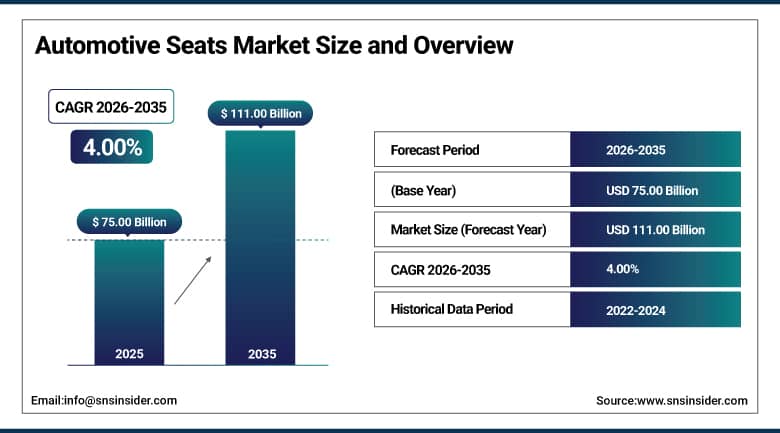
The Automotive Seats Market was valued at USD 75.00 Billion in 2025 and is expected to reach USD 111.00 Billion by 2035, growing at a CAGR of 4.00% from 2026–2035.
Automotive seats form an integral part of any vehicle, comforting the driver and passengers while also serving as a genuine safety component that has to perform correctly in a crash rather than just look good on a showroom floor. Comfort and personalization are fast gaining preference among buyers, pushing manufacturers to layer heating, ventilation, massage, and memory functions into seats that a decade ago offered little beyond manual adjustment. The rise of electric vehicles has added a further engineering wrinkle, since lighter seat structures directly extend range, forcing suppliers to cut weight without sacrificing the comfort features buyers increasingly expect as standard rather than premium extras.
Lear Corporation began integrating its ComfortMax seating technology into General Motors vehicles starting in the second quarter of 2025, bringing faster heating and ventilation response times to a broader range of trim levels rather than reserving the feature for flagship luxury models. New comfort features are moving from luxury trims into higher-volume vehicles faster than many expect, a shift that reflects how much seat suppliers now compete on the same kind of rapid feature rollout cycle that used to define smartphone software updates rather than the multi-year redesign cycles automotive interiors traditionally ran on.
To Get More Information On Automotive Seats Market - Request Free Sample Report
Automotive Seats Market Trends
-
Powered comfort features, including heating, ventilation, massage, and memory settings, continue moving from luxury trims into mid-range and higher-volume vehicles as suppliers compete on faster feature rollout cycles.
-
Lightweight seat structures continue advancing as electric vehicle manufacturers push suppliers to cut weight from every component, since lighter seats directly translate into extended vehicle range.
-
Recycled and sustainable material adoption continues expanding across seat trim and structural components, driven by automaker carbon reduction commitments and, increasingly, formal end-of-life vehicle circularity regulation.
-
Autonomous driving-oriented seating concepts, including relaxation and swivel-capable designs, continue advancing as manufacturers anticipate a future where seats serve passengers rather than exclusively drivers focused on the road.
-
Haptic feedback integration into seats continues emerging as a genuine safety and driver-support technology, moving beyond a niche comfort feature into mainstream advanced driver assistance system architecture.
U.S. Automotive Seats Market Outlook
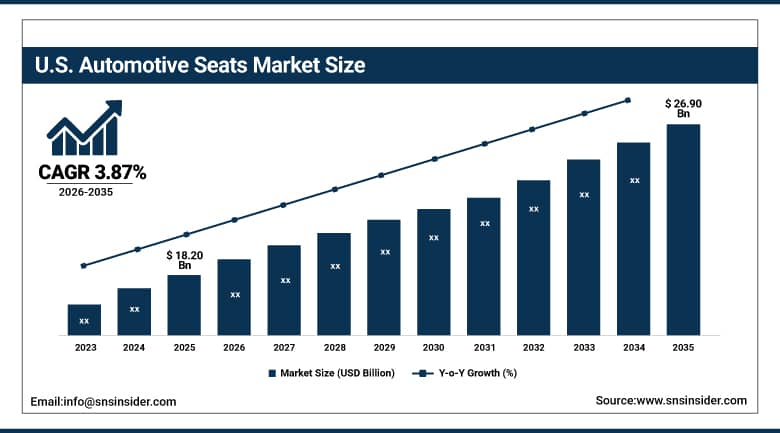
The U.S. Automotive Seats Market was valued at approximately USD 18.20 Billion in 2025 and is expected to reach approximately USD 26.90 Billion by 2035, growing at a CAGR of approximately 3.87%.
U.S. demand is characterized by the rise in consumer demand for comfort, ergonomic features, and safety in all types of automobiles, coupled with an increase in urbanization and subsequent traffic congestion, which has led to higher consumer demand for seats that provide increased comfort even in smaller, more urbanized cars. An increasing use of light weight materials and technology incorporation, such as ventilated seats and massaging seats that have been seen before only in high-end luxurious automobiles, has kept driving U.S. demand.
Adient plc introduced lightweight, sustainable seating solutions using recycled materials in May 2025, specifically targeting automakers' carbon reduction goals across the United States and Canada. The company, formerly Johnson Controls' automotive seating division before separating in 2016, remains one of the largest American-headquartered seat suppliers competing directly against Lear domestically, and its push toward recycled-material seating reflects growing pressure from U.S. and Canadian automakers to demonstrate genuine sustainability progress in vehicle interiors, not just powertrains.
Automotive Seats Market Segment Analysis
-
By Seat Type, the Bucket Seat segment dominated the Automotive Seats Market with approximately 52.40% share in 2025, and is also the fastest growing with a CAGR of approximately 5.80%.
-
By Material Type, the Synthetic Leather/Leatherette segment dominated the Automotive Seats Market with approximately 48.20% share in 2025, while the Genuine Leather segment is the fastest growing with a CAGR of approximately 6.20%.
-
By Technology, the Standard/Manual Seats segment dominated the Automotive Seats Market with approximately 57.80% share in 2025, while the Powered Seats segment is the fastest growing with a CAGR of approximately 7.40%.
-
By Vehicle Type, the Passenger Vehicles segment dominated the Automotive Seats Market with approximately 75.00% share in 2025, while the Commercial Vehicles segment is the fastest growing with a CAGR of approximately 6.20%.
-
By Sales Channel, the OEM segment dominated the Automotive Seats Market with approximately 82.60% share in 2025, while the Aftermarket segment is the fastest growing with a CAGR of approximately 5.80%.
By Seat Type, bucket seat dominates and grows fastest
The bucket seats dominated the seat type market in 2025 because of the high level of comfort, good ergonomic nature, and rising demand in high-end and performance automobiles in almost all segments of automobiles. The bucket seats provide individual seats with higher lateral support and are thus favored by consumers in passenger vehicles, SUVs, pickup trucks, and luxury crossovers as consumers look forward to enjoying comfort, side support, and security.
The bucket seats also represented the highest-growth seat type category due to consumer preference for comfort, ergonomic nature, and sportiness, particularly in luxury cars, SUVs, and performance cars. The advancement in automobile technology has brought about the installation of adjustable lumbar support, heat and cold support, and memory systems in bucket seats, which have added to the appeal of the bucket seats.
By Material Type, synthetic leather dominates, genuine leather grows fastest
Synthetic leather and leatherette comprised the largest market share in the material type segment in 2025 owing to its premium appearance and cost-effective nature as compared to real leather. Also, synthetic leather was superior in terms of durability compared to regular fabric on seats. It is due to the aforementioned reasons that synthetic leather remains the preferred choice of material for the premium market.
Genuine leather is experiencing the fastest growth owing to increasing demand for luxury cars, and hence, premium interiors from developed and developing countries where consumers upgrade themselves to premium segments. In addition, with car manufacturers trying to differentiate themselves through genuine leather usage in premium cars and luxury cars, the trend for fast-paced growth continues.
By Technology, standard seats dominates, powered seats grows fastest
Standard, manually adjusted seats held the majority share of the technology segment in 2025, remaining the practical default across entry-level and mid-range vehicles where cost sensitivity outweighs the marginal convenience powered adjustment offers. That combination of lower cost and mechanical simplicity keeps standard seats the dominant technology category across the broader global vehicle parc, particularly in price-sensitive emerging markets.
Powered seats are growing fastest as heating, ventilation, massage, and memory functions continue moving from luxury trims into higher-volume, mid-range vehicles faster than previous technology generations migrated downmarket. Rising consumer expectations for comfort features as standard rather than premium equipment continues reinforcing this above-average growth trajectory relative to the broader, standard-seat-dominated technology mix.
By Vehicle Type, passenger vehicles dominates, commercial vehicles grows fastest
Passenger vehicles held the large majority of the vehicle-type segment in 2025, driven by high global production volumes and increasing consumer preference for advanced comfort and safety features in cars, SUVs, crossovers, and premium sedans. Rising needs for premium interiors and advanced seating technology are leading to more seating content per passenger vehicle irrespective of price range, keeping passenger vehicles the dominant vehicle-type category by a wide margin over commercial applications.
Commercial vehicles are growing fastest as demand remains steady due to rising logistics, e-commerce, and fleet renewal activity, with fleet managers increasingly investing in seating technology including air suspension and fatigue-reducing features such as lumbar support. Growing driver retention and safety concerns among commercial fleet operators continue reinforcing this above-average growth trajectory relative to the broader, passenger-vehicle-dominated vehicle-type mix.
By Sales Channel, OEM dominates, aftermarket grows fastest
OEM sales accounted for the large majority of the sales-channel segment in 2025, reflecting how automotive seats are overwhelmingly factory-installed components specified during vehicle design and assembly rather than purchased separately by consumers. That deep integration between seat design and overall vehicle engineering keeps OEM channels the dominant distribution pathway across nearly every seat category and vehicle segment.
Aftermarket sales are growing fastest as an aging global vehicle fleet generates rising demand for seat replacement, reupholstery, and aftermarket comfort upgrades beyond original factory specifications. Growing vehicle parc size across both developed and emerging markets continues reinforcing this above-average growth trajectory as more vehicles age past their original seat's practical service life.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
42.60% |
|
North America |
United States |
81.40% |
|
Europe |
Germany |
25.60% |
|
Latin America |
Brazil |
35.80% |
|
Middle East & Africa |
Saudi Arabia |
30.20% |
Asia Pacific Automotive Seats Market Insights
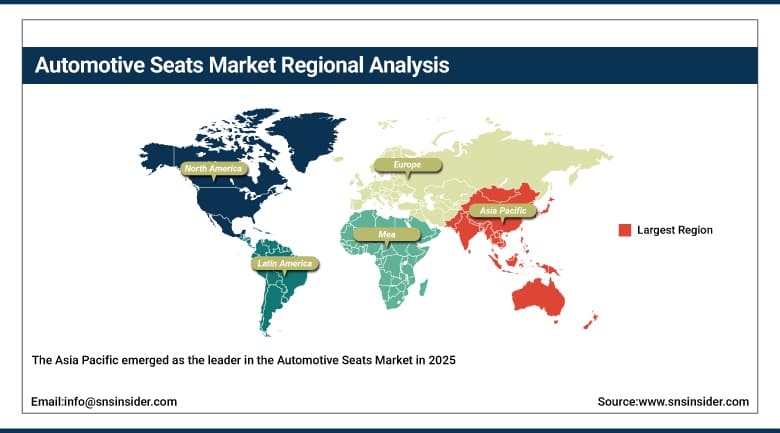
The Asia Pacific emerged as the leader in the Automotive Seats Market in 2025 due to rapid technology innovation, the increasing need for luxury automobiles, the introduction of high safety standards, and increasing passenger comfort and ergonomic concerns. The China electric vehicle revolution, the quick growth of compact SUVs in India, and the continuous investments in seat electronics by Japanese companies all continue to fuel the dominance and growth of this region in terms of its largest automotive manufacturing countries.
The huge automotive manufacturing capacity in China provides the region with a lot of underlying demand for automotive seats, with China expected to achieve 45% penetration of EVs in new car sales. In India, the policies of government to subsidize electric three wheelers and delivery vans have resulted in growing demand for durable and maintenance-free trimming. Japan continues to unveil relaxation seats that move like a swing chair and have personal audio systems.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Automotive Seats Market Insights
North America represents a substantial automotive seats market, with the United States accounting for the large majority of regional demand through rising demand for premium and comfort seating features across passenger and commercial vehicles alike. Passenger vehicles dominate the regional market given relatively higher production levels in both the U.S. and Canada, alongside growing consumer preference for SUVs, crossovers, and premium sedans.
Canada contributes additional demand through its own vehicle manufacturing and commercial fleet sector, while Mexico's market continues expanding alongside growing nearshoring-driven automotive manufacturing investment. Cross-border supply relationships tie much of North American demand together, with major seat manufacturers typically serving all three markets through shared production networks.
Europe Automotive Seats Market Insights
Europe is a developed, technologically advanced automotive seats industry driven by safety regulations, use of lightweight materials, and incorporation of electronic adjustment systems in one of the world's biggest centers for automobile manufacturing in Europe. Germany is the driving force behind the demand for seats in Europe with its extensive automobile manufacturing industry and various seat manufacturers with strong knowledge of comfort and safety technology.
France and Italy are among those countries which are adding volumes in this region, as both countries have huge automobile manufacturing industries that are being influenced by the European Union's 2025 agreement regarding the recyclability of vehicles at their end-of-life phase. The focus on sustainability of seat materials in Europe is influencing the product development process here more than anywhere else in the world.
MEA & Latin America Automotive Seats Market Insights
The Middle East and Africa represent a smaller but strategically developing automotive seats market, with Saudi Arabia driving demand through substantial infrastructure investment and expanding vehicle ownership tied to the country's broader economic diversification goals. Growth elsewhere in the region remains tied closely to the pace of broader automotive manufacturing and vehicle ownership infrastructure development.
Latin America is a growing market led by Brazil, where expanding vehicle production and rising consumer demand for comfort features continue driving demand for advanced automotive seating. Mexico and Argentina contribute meaningful secondary demand, tied to their own growing automotive manufacturing sectors serving both domestic and export-oriented vehicle markets.
Market Dynamics
Growth Drivers: Rising vehicle production and comfort feature demand fueling adoption
Rising vehicle production worldwide is one of the clearest forces behind rising automotive seats demand, as growing automotive manufacturing across both developed and emerging economies continues expanding the addressable market for seating systems across passenger and commercial vehicle segments simultaneously. Increasing global demand for SUVs and luxury cars, especially in developing countries, continues reinforcing this demand base as these vehicle categories typically specify more seating content per unit than economy segments.
Growing consumer preference for enhanced comfort adds a second major driver, as buyers increasingly expect heated, ventilated, and powered seating adjustment as standard equipment rather than premium extras reserved for flagship trim levels. The need for foldable and adjustable seating configurations in SUVs, which allow for flexible cargo and passenger space, continues reinforcing this demand base across the broader vehicle market.
Restraints: Raw material price volatility and lightweighting cost pressure limiting margin stability
Fluctuating steel, foam, and leather prices add real cost unpredictability for manufacturers, since seat producers remain exposed to broader commodity market swings that directly affect production costs across every material category and vehicle segment. Manufacturers without long-term material supply contracts are particularly exposed to these swings, which can compress margins even when finished-seat demand remains steady.
Lightweighting cost pressure adds a further restraint, as electric vehicle manufacturers increasingly demand weight reduction from every component supplier, requiring seat manufacturers to invest in advanced materials and structural engineering that can meaningfully raise production costs relative to conventional steel-frame designs. That investment burden falls disproportionately on smaller suppliers without dedicated materials science and engineering capability.
Opportunities: Sustainable material innovation and autonomous-ready seating design opening new growth avenues
Sustainable material innovation offers manufacturers a genuine path to capturing premium business from automakers chasing credible carbon reduction commitments and complying with tightening end-of-life vehicle circularity regulation across major markets. Companies that build strong recycled-content and disassembly-friendly design capability are positioned to capture disproportionate growth as regulatory and brand-owner sustainability pressure both continue building.
Autonomous-ready seating design represents a second significant opportunity, as manufacturers develop relaxation-oriented, swivel-capable, and haptic-feedback-enabled seats anticipating a future where passengers rather than exclusively drivers occupy vehicle cabins. Companies that build genuine autonomous-ready seating expertise are positioned to capture premium pricing from automakers seeking differentiation as autonomous driving technology continues maturing.
Recent Developments:
-
March 2024: Toyota Boshoku Corporation announced development of autonomous driving-related technologies, including Relax & Safety Seats for enhanced passenger comfort and an Active Driver Engagement System to reduce fatigue.
-
July 2025: Toyota Boshoku Corporation expanded its next-generation cabin concepts across Japan and Southeast Asia, focusing on smart interior integration.
-
2025: Forvia continued developing its VIBE haptic seat technology, under contract since 2023, with launch planned toward the end of 2025.
-
Fiscal Year 2025: Adient reported that approximately 70% of its new business in China came from Chinese OEMs, reflecting the company's deepening localization strategy in the region.
Automotive Seats Market Key Players
-
Adient plc
-
Lear Corporation
-
Toyota Boshoku Corporation
-
Faurecia SE (FORVIA)
-
Magna International Inc.
-
TS Tech Co., Ltd.
-
NHK Spring Co., Ltd.
-
Grupo Antolin
-
Continental AG
-
Aisin Corporation
-
Denso Corporation
-
Gentherm Incorporated
-
Kongsberg Automotive ASA
-
Hyundai Transys Inc.
-
Freedman Seating Company
-
Grammer AG
-
Recaro Automotive Seating
-
IFB Automotive Private Limited
-
DK Group
-
Yanfeng Automotive Systems
Automotive Seats Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 75.00 Billion |
| Market Size by 2035 | USD 111.00 Billion |
| CAGR | CAGR of 4.00% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Seat Type (Bucket Seat, Bench Seat, Split Bench Seat, Stow-and-Go/Retractable Seat, Others) • by Material Type (Genuine Leather, Synthetic Leather/Leatherette, Fabric, Others) • by Technology (Standard/Manual Seats, Powered Seats, Ventilated Seats, Others) • by Vehicle Type (Passenger Vehicles, Commercial Vehicles), Sales Channel (OEM, Aftermarket) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Adient plc, Lear Corporation, Toyota Boshoku Corporation, Faurecia SE (FORVIA), Magna International Inc., TS Tech Co., Ltd., NHK Spring Co., Ltd., Grupo Antolin, Continental AG, Aisin Corporation, Denso Corporation, Gentherm Incorporated, Kongsberg Automotive ASA, Hyundai Transys Inc., Freedman Seating Company, Grammer AG, Recaro Automotive Seating, IFB Automotive Private Limited, DK Group, Yanfeng Automotive Systems |
Frequently Asked Questions
The Asia Pacific region dominated the Automotive Seats Market in 2025 with approximately 44.20% share, driven by rapid technological advancements and rising demand for luxury vehicles.
Key players in the Automotive Seats Market include Adient plc, Lear Corporation, Toyota Boshoku Corporation, Faurecia SE (FORVIA), and Magna International Inc., among others.
Key opportunities in the Automotive Seats Market include sustainable material innovation meeting end-of-life vehicle circularity regulation and autonomous-ready seating design with relaxation and haptic-feedback capability.
The market is driven by rising vehicle production worldwide, combined with growing consumer preference for enhanced comfort features including powered heating, ventilation, and memory settings.
The Bucket Seat segment dominated the Automotive Seats Market, accounting for approximately 52.40% market share.
