
U.S. Pharmacy Benefit Management (PBM) Market Report Scope & Overview:
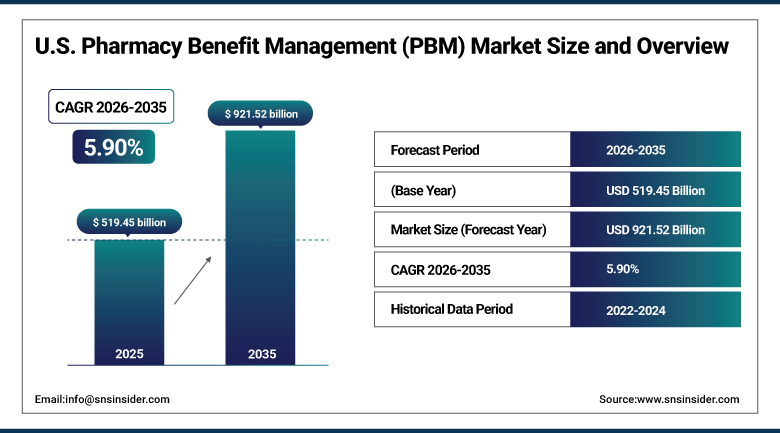
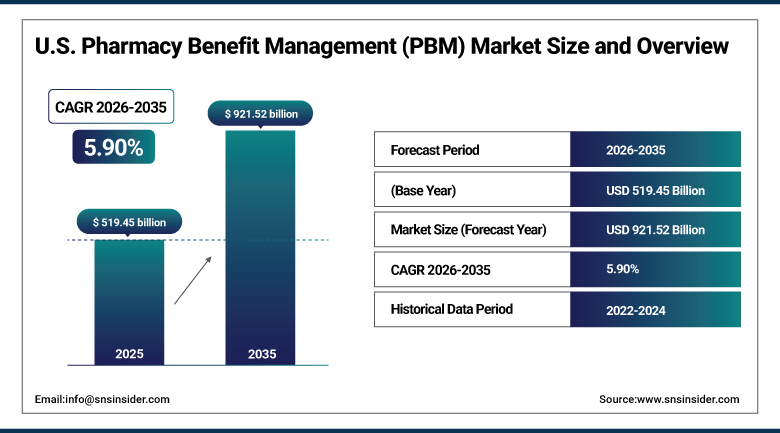
The U.S. Pharmacy Benefit Management Market was valued at USD 519.45 Billion in 2025 and is expected to reach USD 921.52 Billion by 2035, growing at a CAGR of 5.90% from 2026 to 2035.
The U.S. pharmacy benefit management market is growing at a steady pace owing to the rise in healthcare spending having a significant impact on market growth, increasing numbers of populations insured under commercial insurance, and rising access to public health insurance programs. Pharmacy Benefit Management is described as a collective term referring to a number of firms that act as intermediaries between pharmacies, insurers and drug companies, having a very important part in obtaining and negotiating the cost of drugs for insurance firms. Moreover, growth in the market is being stimulated by the increased use of AI-driven cost optimization tools, the importance of value-based care models, increase in specialty drug management and increasing digitization of the pharmacy benefit platforms.
Specialty medicines accounted for 54% of hospital drug spend in 2025, pressuring payers to adopt PBM models that integrate clinical expertise with utilization controls, with the popularity of GLP-1 agonists for diabetes and obesity potentially lifting that therapeutic class toward USD 100 billion in spending within five years, requiring tighter formulary rules and step-therapy edits across the industry.
Market Size and Forecast
- Market Size in 2026E: USD 554.90 Billion
- Market Size by 2035: USD 921.52 Billion
- CAGR: 5.90% from 2026 to 2035
- Fastest Growing Region: West
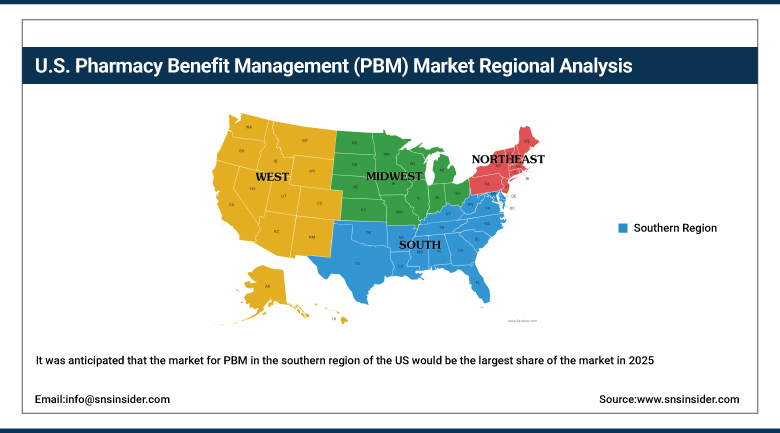
- Largest Region: South
To Get more information U.S. Pharmacy Benefit Management (PBM) Market - Request Free Sample Report
The U.S. Pharmacy Benefit Management (PBM) Market Trends
- Rising adoption of AI-powered cost optimization tools is enabling PBMs to more accurately forecast drug utilization trends and identify opportunities for formulary and rebate strategy optimization.
- Growing emphasis on value-based care models is driving PBMs to increasingly tie reimbursement and formulary placement decisions to patient outcomes rather than volume-based metrics alone.
- Increasing regulatory scrutiny of drug pricing and PBM rebate practices is driving broader adoption of transparent, pass-through pricing arrangements across the industry.
- Expanding specialty drug management capability is becoming increasingly critical as GLP-1 agonists and other high-cost specialty therapeutics continue capturing a growing share of overall pharmacy benefit spending.
- Strategic partnerships among PBMs, health plans, and digital health platforms are supporting development of increasingly integrated, data-driven pharmacy benefit management solutions.
The U.S. Pharmacy Benefit Management (PBM) Market Outlook
The U.S. Pharmacy Benefit Management (PBM) Market was valued at USD 519.45 Billion in 2025 and is projected to reach USD 921.52 Billion by 2035, growing at a CAGR of 5.90% during 2026–2035.
The country's leading health plans and employer groups continue to expand pharmacy benefit management program investment, driven by sustained growth in commercial insurance enrollment and rising access to public health insurance programs including Medicare and Medicaid. Growing disruption from independent, transparent-pricing PBMs and cash-pay pharmacy alternatives, combined with intensifying FTC scrutiny of the largest PBM rebate and pricing practices, continues to reshape the competitive landscape across the country's substantial and highly concentrated pharmacy benefit management industry, which remains dominated by a small number of vertically integrated national players.
The U.S. Pharmacy Benefit Management industry comprises of about 87 companies and has witnessed a CAGR of 3.9% during the period from 2020 to 2025. The U.S. PBM industry will face further disruption in the coming years since cash pay pharmacies and independent PBMs have been creating issues for the existing model of vertical integration.
The U.S. Pharmacy Benefit Management (PBM) Market Segment Analysis
- By Business Model, standalone PBM dominated the U.S. pharmacy benefit management (PBM) market with a 60.00% share in 2025, while healthcare insurance provider is the fastest-growing business model segment with a CAGR of 7.20% from 2026–2035.
- By Services, specialty pharmacy services dominated the U.S. pharmacy benefit management (PBM) market with a 44.60% share in 2025, while retail pharmacy networks is the fastest-growing services segment with a CAGR of 7.60% from 2026–2035.
- By End-User, federal/government programs dominated the U.S. pharmacy benefit management (PBM) market with a 38.60% share in 2025, while commercial is the fastest-growing end-user segment with a CAGR of 7.40% from 2026–2035.
- By Health Plan, commercial health plans dominated the U.S. pharmacy benefit management (PBM) market with a 46.80% share in 2025, while medicare plans is the fastest-growing health plan segment with a CAGR of 8.20% from 2026–2035.
By Business Model, standalone PBM dominated the U.S. pharmacy benefit management (PBM) market, while healthcare insurance provider is the fastest-growing segment.
The standalone PBM sub-segment occupied the leading position in the U.S. Pharmacy Benefit Management market, with a maximum market share of 60.00% in 2025. The standalone PBM remains the leading business model sub-segment because of its size advantage in negotiating rebates and managing formularies; thus, making the big national companies able to use their large number of covered lives to negotiate better prices for drugs from the manufacturers.
The healthcare insurance provider segment is expected to generate significant revenue growth throughout the forecast period, growing at an estimated CAGR of 7.20%. Growing integration of pharmacy benefit management functions directly within health insurance provider organizations is driving strong segment growth, as insurers increasingly seek to capture pharmacy margin internally rather than outsourcing to independent PBM intermediaries.
By Services, specialty pharmacy services dominated the U.S. pharmacy benefit management (PBM) market, while retail pharmacy networks is the fastest-growing segment.
The specialty pharmacy services segment dominated the U.S. pharmacy benefit management market in 2025, holding the largest share among PBM service categories. Specialty pharmacy services remain the dominant category owing to the rapidly growing share of pharmacy spend attributable to high-cost specialty and biologic medications, requiring sophisticated clinical management, prior authorization, and distribution capability that continues to anchor PBM revenue growth.
The retail pharmacy networks segment is expected to witness significant growth during the predicted timeframe. Growing consumer demand for broader retail pharmacy access and network flexibility is driving rising segment growth, as PBMs continue expanding preferred and narrow network arrangements designed to balance member convenience with cost containment objectives across increasingly complex retail pharmacy landscapes.
By End-User, federal/government programs dominated the U.S. pharmacy benefit management (PBM) market, while commercial is the fastest-growing segment.
The federal/government programs segment is expected to dominate the U.S. pharmacy benefit management market during the anticipated forecast period. Federal and government programs, encompassing Medicare Part D and other public insurance initiatives, remain a dominant end-user category owing to the substantial and growing enrollment base covered under federal health insurance programs serving the country's aging population.
The commercial segment is projected to demonstrate the highest market growth in 2025, with continued strong momentum expected across the forecast period. The rise in populations insured under commercial insurance and rising access to public health insurance, along with growing numbers of payers assigned to PBM arrangements, continues to drive strong commercial segment growth across the employer-sponsored insurance market.
By Health Plan, commercial health plans dominated the U.S. pharmacy benefit management (PBM) market, while medicare plans is the fastest-growing segment.
The commercial health plans segment dominated the U.S. pharmacy benefit management market owing to the substantial scale of employer-sponsored insurance coverage across the country, representing the largest single health plan category served by PBMs and continuing to anchor the majority of overall pharmacy benefit management contract volume nationwide.
The medicare plans segment is expected to register the fastest CAGR of 8.20% during the forecast period 2026-2035. Growing enrollment in Medicare Advantage and Medicare Part D plans tied to the country's aging population, combined with rising specialty drug utilization among Medicare beneficiaries managing chronic and complex conditions, is driving strong segment growth across Medicare-focused PBM contracts.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
South |
Texas |
38.60% |
|
West |
California |
27.60% |
|
Midwest |
Illinois |
24.80% |
|
Northeast |
New York |
26.80% |
|
Other Territories |
Puerto Rico |
12.40% |
South Region U.S. Pharmacy Benefit Management Market Insights
It was anticipated that the market for PBM in the southern region of the US would be the largest share of the market in 2025 because of the large population size in the southern region and the increasing number of people taking up employer-sponsored health insurance programs.
Texas is the leading state within the South region, driven by extensive employer-sponsored health plan coverage and growing Medicaid managed care enrollment. Other states such as Florida and Georgia are also contributing to regional growth through expanding commercial insurance enrollment and rising specialty drug utilization across their growing populations.
Get Customized Report as per Your Business Requirement - Enquiry Now
West Region U.S. Pharmacy Benefit Management Market Insights
The West region is expected to register the fastest regional CAGR during the forecast period. It is due to the high number of technology sector employers in this area, presence of leading digital health and PBM disruptor companies, and the increasing demand from consumers for transparency and technologically-driven pharmacy benefits management.
California is the leader in this region because of its large population and the presence of leading employer-based health plans. Other states such as Washington and Colorado are also contributing to regional growth through expanding commercial insurance enrollment and rising adoption of digital-first PBM platforms.
Midwest Region U.S. Pharmacy Benefit Management Market Insights
The Midwest region was a major contributor to the U.S. pharmacy benefit management market in 2025. This is attributed to the region's strong presence of leading national PBM headquarters and substantial employer-sponsored insurance enrollment across the region's diverse industrial and healthcare employer base.
Illinois is one of the major states in the Midwest owing to its strong healthcare industry presence and substantial commercial insurance enrollment. Other states such as Ohio and Michigan are also contributing to regional growth through expanding Medicaid managed care enrollment and rising employer-sponsored health plan coverage.
Northeast Region U.S. Pharmacy Benefit Management Market Insights
The Northeast region continues to contribute substantially to the U.S. pharmacy benefit management market, supported by strong presence of leading health insurance and PBM company headquarters and substantial commercial insurance enrollment across the region's dense metropolitan population centers.
New York is one of the major states in the Northeast owing to its substantial population base and strong presence of leading health insurance companies. Other states such as Massachusetts and Connecticut, home to major health insurance company headquarters, are also contributing to regional growth through expanding specialty drug management capability.
Market Dynamics
Growth Drivers: Rising healthcare spending and specialty drug management demand driving market growth
The rise in healthcare spending has had a significant impact on the market's growth, as increasing numbers of populations insured under commercial insurance and rising access to public health insurance continue to expand the addressable base of covered lives requiring pharmacy benefit management services. With the rising number of assigned insurances, several payers are increasingly assigned to PBM arrangements, which represents a primary driving factor for continued market expansion across both commercial and government-sponsored health plan segments.
The growing use of AI cost optimization tools, increasing focus on value-based care approaches, growing specialty drugs management, and increased regulatory oversight over drug prices remain trends influencing the industry’s development. Growing digitalization of pharmacy benefit platforms, rising GLP-1 and specialty medication utilization pressuring payers to adopt more sophisticated formulary and utilization management strategies, and expanding Medicare and Medicaid managed care enrollment are further supporting demand across the forecast period.
Restraints: Regulatory scrutiny and rebate transparency pressure limiting market expansion
One of the main barriers to market growth is intensifying FTC inquiries and regulatory scrutiny of leading PBM rebate and pricing practices, which continue to raise questions about industry transparency and could meaningfully reshape how the largest, vertically integrated PBMs operate going forward.
Also, the increasing disruptions by cash pay pharmacies and independent pricing transparent PBMs have been adding additional pressure on the long-established rebate-based model that has been earning big bucks for PBMs in the past. In addition to that, the increasing complexity of managing more complex specialty drugs formularies like GLP-1 drugs and biologics is yet another area where PBMs need significant investment.
Opportunities: Expansion of transparent pricing models and specialty drug management creating new growth avenues
The growth of cash-pay pharmacies and independent, transparent-pricing PBM entrants represents both a competitive challenge and a substantial opportunity, as this disruption is expected to accelerate industry transformation toward more transparent, pass-through pricing arrangements that could reshape competitive dynamics across the broader PBM landscape.
There is a considerable growth opportunity in the continued development of AI-powered predictive cost analytics and formulary management tools that help payers navigate increasingly complex specialty drug spending trends. The increase in the demand will be substantial because of the rising Medicare Advantage and managed Medicaid care plans due to the elderly population and the growing number of individuals enrolled in health insurance programs.
Recent Developments:
- 2025: CVS Caremark expanded its transparent pricing PBM model, offering employer and health plan clients enhanced visibility into drug acquisition costs and rebate pass-through arrangements amid growing regulatory scrutiny.
- 2025: Evernorth Health Services, parent of Express Scripts, expanded its GLP-1 medication management program, offering payers enhanced clinical utilization controls for rapidly growing diabetes and obesity therapeutic spending.
- 2026: OptumRx launched an updated AI-driven formulary management platform, offering health plan clients enhanced predictive cost analytics for navigating increasingly complex specialty drug spending trends.
- 2026: Capital Rx expanded adoption of its transparent, pass-through PBM pricing model among employer and health plan clients seeking alternatives to traditional rebate-driven PBM arrangements.
The U.S. Pharmacy Benefit Management (PBM) Market key players are:
- CVS Health Corporation (CVS Caremark)
- The Cigna Group (Express Scripts/Evernorth Health Services)
- UnitedHealth Group Incorporated (OptumRx)
- Humana Inc. (Humana Pharmacy Solutions)
- Prime Therapeutics LLC
- MedImpact Healthcare Systems, Inc.
- Elixir Rx Solutions, LLC
- Navitus Health Solutions, LLC
- EmpiRx Health LLC
- Capital Rx, Inc.
- Rightway Healthcare, Inc.
- Abarca Health, LLC
- SmithRx, Inc.
- Elevance Health, Inc. (IngenioRx)
- Centene Corporation
- Molina Healthcare, Inc.
- WellDyneRx, LLC
- PerformRx, LLC
- Envision Rx (ProAct, Inc.)
- Change Healthcare Inc. (UnitedHealth Group)
U.S. Pharmacy Benefit Management (PBM) Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 519.45 Billion |
| Market Size by 2035 | USD 921.52 Billion |
| CAGR | CAGR of 5.90% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Business Model (Standalone PBM, Healthcare Insurance Provider, Insurance Companies & Retail Pharmacies) • By Services (Specialty Pharmacy Services, Retail Pharmacy Networks, Mail-Order Pharmacy Services, Claims Processing) • By End-User (Federal/Government Programs, Commercial, Medicaid) • By Health Plan (Commercial Health Plans, Medicare Plans, Medicaid Plans) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | CVS Health Corporation (CVS Caremark), The Cigna Group (Express Scripts/Evernorth Health Services), UnitedHealth Group Incorporated (OptumRx), Humana Inc. (Humana Pharmacy Solutions), Prime Therapeutics LLC, MedImpact Healthcare Systems, Inc., Elixir Rx Solutions, LLC, Navitus Health Solutions, LLC, EmpiRx Health LLC, Capital Rx, Inc., Rightway Healthcare, Inc., Abarca Health, LLC, SmithRx, Inc., Elevance Health, Inc. (IngenioRx), Centene Corporation, Molina Healthcare, Inc., WellDyneRx, LLC, PerformRx, LLC, Envision Rx (ProAct, Inc.), Change Healthcare Inc. (UnitedHealth Group) |
Frequently Asked Questions
The U.S. Pharmacy Benefit Management Market is expected to grow at a CAGR of 5.90% from 2026 to 2035.
The U.S. Pharmacy Benefit Management Market was valued at USD 519.45 Billion in 2025.
The market is driven by rising healthcare spending, increasing numbers of populations insured under commercial insurance, and rising access to public health insurance programs.
The Standalone PBM segment dominated the U.S. Pharmacy Benefit Management Market in 2025, accounting for approximately 60.00% market share.
The South region dominated the U.S. Pharmacy Benefit Management Market in 2025.
