
Building Information Modeling Market Report Scope & Overview:
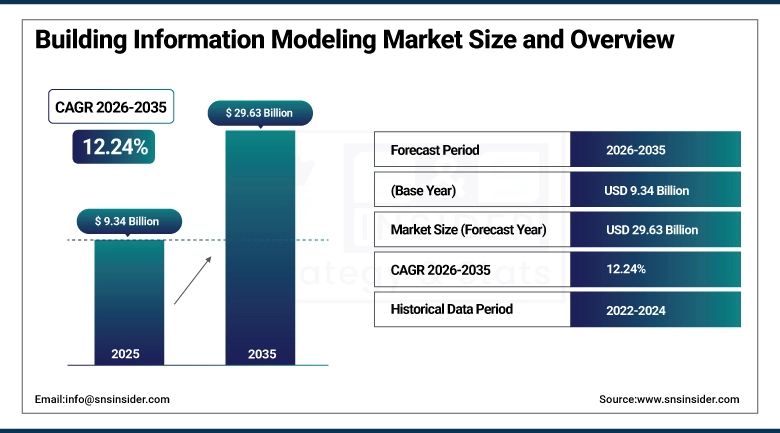
The Building Information Modeling Market size was valued at USD 9.34 Billion in 2025 and is projected to reach USD 29.63 Billion by 2035, registering a CAGR of 12.24% from 2026 to 2035.
The Building Information Modeling Market continues to expand as architecture, engineering and construction firms increasingly replace 2D drafting workflows with intelligent 3D model-based design, coordination and documentation. Rising infrastructure investment, growing public-sector mandates requiring BIM on government-funded projects, and mounting pressure to reduce design clashes and rework are pushing adoption beyond large contractors into mid-sized firms. Growing integration between BIM platforms and downstream construction-management, scheduling and cost-estimation software is widening the addressable use case beyond design into full project-lifecycle coordination.
Software and solutions vendors continue layering cloud-based collaboration, clash detection and AI-assisted design-review capability onto established desktop modeling tools, while dedicated services providers are capturing a growing share of demand from firms that lack in-house BIM expertise. Deployment is gradually shifting from on-premises installations toward cloud-hosted platforms as distributed project teams increasingly require real-time, multi-party access to a shared model. Growing adoption across construction and operation phases, beyond the traditional design-stage use case, is further widening the market's addressable project-lifecycle scope.
⮞In 2024 Dassault Systèmes bolstered its 3DEXPERIENCE platform with enhanced BIM capabilities and cloud-based collaboration tools for complex infrastructure projects, mirroring the wider industry shift to unified model-coordination platforms hosted on the cloud.
To Get more information On Building Information Modeling Market - Request Free Sample Report
Building Information Modeling Market Trends
-
Cloud-hosted BIM platforms continue gaining share over traditional on-premises deployments.
-
Public-sector BIM mandates on government-funded infrastructure projects continue expanding globally.
-
AI-assisted clash detection and design-review tools continue shortening coordination cycles.
-
Services providers continue gaining share as mid-sized firms seek outsourced BIM expertise.
-
Adoption beyond design into construction and operations phases continues widening use cases.
-
Integration between BIM platforms and downstream construction-management software continues deepening.
US Building Information Modeling Market Size Outlook
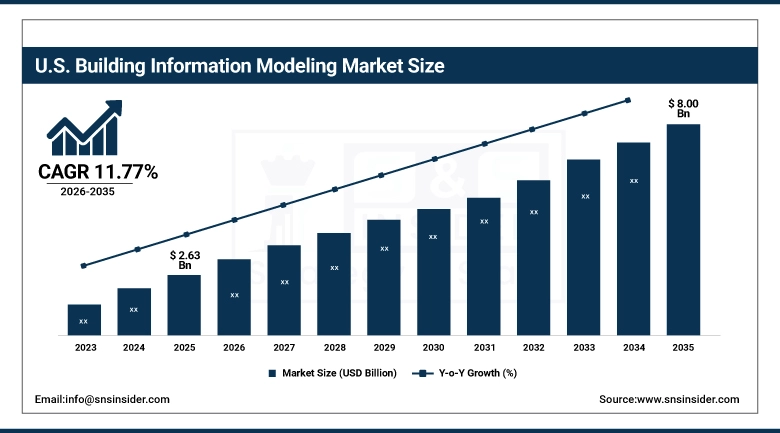
The US Building Information Modeling Market was valued at approximately USD 2.63 Billion in 2025 and is projected to reach approximately USD 8.00 Billion by 2035, registering a CAGR of approximately 11.77% from 2026 to 2035.
Demand continued to be shaped by large contractor and AEC-firm BIM adoption, expanding public-sector mandates on federally funded infrastructure projects, and growing integration between design-stage BIM models and downstream construction-management platforms across the United States. The country continues to be the largest national market tracked in this report, with further growth in the cloud-hosted collaboration tools segment driven by Procore’s ongoing platform expansion. Domestic demand continued across both design and construction-phase workflows, aided by ongoing investment in the Revit platform by Autodesk. Across software and services channels alike, firms are putting more focus on interoperability in addition to cost containment.
⮞In May 2025, Procore Technologies bought Novorender and FlyPaper Technologies to improve its BIM visualization and data-capture capabilities as contractors seek more integrated, cloud-based model-coordination tools.
Building Information Modeling Market Segment Analysis
-
By Component, the Software & Solutions segment dominated the Building Information Modeling Market in 2025 with 57.00% share; the Services segment is the fastest growing segment with a CAGR of approximately 15.85%.
-
By Deployment Mode, the On-Premises segment dominated the Building Information Modeling Market in 2025 with 56.00% share; the Cloud segment is the fastest growing segment with a CAGR of approximately 16.40%.
-
By Project Lifecycle, the Preconstruction segment dominated the Building Information Modeling Market in 2025 with 43.00% share; the Construction segment is the fastest growing segment with a CAGR of approximately 14.65%.
-
By Application, the Commercial segment dominated the Building Information Modeling Market in 2025 with 34.20% share; the Industrial segment is the fastest growing segment with a CAGR of approximately 14.95%.
-
By End User, the AEC Professionals segment dominated the Building Information Modeling Market in 2025 with 52.65% share; the Consultants & Facility Managers segment is the fastest growing segment with a CAGR of approximately 15.20%.
By Component, Software & Solutions Dominates the Building Information Modeling Market and Services Grows Fastest
In 2025, Software & Solutions was the largest component segment as companies preferred to license existing modeling, clash detection and documentation platforms rather than outsourcing the actual BIM authoring work itself. Big AEC firms are still purchasing enterprise-wide software licenses for Autodesk and Bentley platforms. The familiarity that design teams have with the tools helps keep them against newer entrants. Established plugin and interoperability ecosystems built around these leading platforms further reinforce this channel's dominant position relative to standalone services engagements. Established vendor familiarity among existing clients further reinforces this channel's entrenched position within the Building Information Modeling Market.
Services are forecast to grow fastest as mid-sized firms lacking in-house BIM expertise increasingly outsource modeling, coordination and clash-detection work to dedicated service providers. Firms increasingly favor these providers for their ability to scale project-specific modeling capacity without carrying permanent software-licensing and training overhead. Growing specialization among services firms in niche project types, such as healthcare and transportation infrastructure, is further accelerating this channel's above-average growth trajectory relative to pure software licensing. Continued vendor investment in supporting tools and training is reinforcing this above-average growth trajectory.
⮞In March 2023, Autodesk released the 2024 version of its Revit platform with improved efficiency, performance and compatibility, reinforcing the entrenched position of established modeling software among large AEC firms.
By Deployment Mode, On-Premises Dominates the Building Information Modeling Market and Cloud Grows Fastest
On-Premises was the largest deployed type in 2025. Large contractors and government agencies processing sensitive infrastructure data still prefer locally hosted installations to third party cloud infrastructure. Core, high-value projects continue to rely on on-premises deployment, as large enterprise and public-sector clients have established IT security policies. There’s a huge existing capital investment already sunk into on-premises server infrastructure that further discourages a near-term wholesale shift toward cloud-hosted alternatives for legacy project portfolios. Existing clients' familiarity with vendors further cements this channel's position in the Building Information Modeling Market.
Cloud deployment is forecast to grow fastest as distributed project teams increasingly require real-time, multi-party access to a shared model across geographically dispersed offices and subcontractors. Growing vendor investment in cloud-native collaboration and version-control capability is reinforcing this above-average growth trajectory across both software and services channels. Expanding mid-sized firm adoption of subscription-based cloud licensing is further accelerating demand for flexible, pay-as-you-go deployment relative to traditional on-premises installations. Continued vendor investment in supporting tools and training is reinforcing this above-average growth trajectory. Growing client willingness to pilot this approach on new projects is further widening its addressable base.
⮞In 2025, Hexagon AB and Nemetschek Group partnered to accelerate the adoption of cloud-based and digital-twin for AEC, on top of rising vendor investment in cloud-native collaboration infrastructure across the industry.
By Project Lifecycle, Preconstruction Dominates the Building Information Modeling Market and Construction Grows Fastest
Preconstruction retained the largest project-lifecycle share in 2025, reflecting the industry's continued emphasis on early-stage design coordination and clash detection to avoid costly rework once physical construction begins. Architects and engineers continue using BIM most intensively during design development and documentation phases, reinforcing preconstruction's position as the largest single lifecycle stage tracked in this report. Growing owner demand for design-stage cost certainty is further reinforcing investment in preconstruction modeling capability across both public and private projects. Established vendor familiarity among existing clients further reinforces this channel's entrenched position within the Building Information Modeling Market.
Construction-phase usage is forecast to grow fastest as contractors increasingly extend BIM models into field coordination, prefabrication planning and progress tracking rather than treating the model as a design-only deliverable. Growing integration between BIM platforms and site-based reality-capture and scheduling tools is reinforcing this above-average growth trajectory. Expanding contractor demand for model-based quantity takeoff and sequencing is further widening construction-phase adoption relative to the traditionally design-centric preconstruction stage. Continued vendor investment in supporting tools and training is reinforcing this above-average growth trajectory. Growing client willingness to pilot this approach on new projects is further widening its addressable base.
By Application, Commercial Dominates the Building Information Modeling Market and Industrial Grows Fastest
Commercial applications dominated the market in 2025, reflecting sustained office, retail and mixed-use development activity and the complexity of multi-stakeholder commercial projects that benefit most from coordinated 3D modeling. Developers and general contractors continue mandating BIM on commercial projects to manage complex mechanical, electrical and plumbing coordination across multiple subcontractors. Growing adoption of BIM for post-occupancy facility management on commercial assets is further reinforcing this application's largest-segment position. Established vendor familiarity among existing clients further reinforces this channel's entrenched position within the Building Information Modeling Market.
Industrial applications are forecast to grow fastest as manufacturing and energy-sector owners increasingly adopt BIM for complex plant design, retrofit planning and digital-twin-enabled operations. Growing integration between BIM and industrial process-engineering software is reinforcing this above-average growth trajectory relative to more established commercial and residential applications. Expanding investment in semiconductor, battery and data-center construction is further widening demand for BIM-enabled industrial facility design and coordination. Continued vendor investment in supporting tools and training is reinforcing this above-average growth trajectory. Growing client willingness to pilot this approach on new projects is further widening its addressable base.
⮞In 2025, Siemens further extended its integration of digital-twin and industrial-design software with BIM-adjacent platforms, solidifying rising industrial-sector demand for coordinated plant-design and facility-operations capability.
By End User, AEC Professionals Dominates the Building Information Modeling Market and Consultants & Facility Managers Grows Fastest
In 2025, AEC Professionals were the largest end-user segment as they are the primary creators and users of BIM models in design, engineering, and construction workflows. Architecture and engineering firms remain central to platform adoption decisions, as they sit at the nexus of model authoring and coordination throughout a project’s life. The dominance of the end-user segment over downstream facility-management users is underpinned by established training pipelines and university curricula designed around the leading BIM platforms. The channel is even more entrenched in the Building Information Modeling Market due to existing clients having established vendor familiarity.
Consultants & Facility Managers are forecast to grow fastest as owners increasingly extend BIM model use beyond construction handover into ongoing operations, maintenance and space-management workflows. Growing adoption of digital-twin-enabled facility management is reinforcing demand for BIM data among consultants advising building owners on long-term asset performance. Expanding integration between BIM models and computerized maintenance-management systems is further accelerating this end-user segment's above-average growth trajectory. Continued vendor investment in supporting tools and training is reinforcing this above-average growth trajectory. Growing client willingness to pilot this approach on new projects is further widening its addressable base.
⮞In 2026, AVEVA Group continued expanding its asset-performance and digital-twin software integration with BIM-derived facility data, reinforcing growing consultant and facility-manager reliance on model-based operational data.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
80.50% |
|
Europe |
Germany |
30.10% |
|
Asia Pacific |
China |
34.50% |
|
Middle East and Africa |
UAE |
32.40% |
|
Latin America |
Brazil |
41.20% |
North America Building Information Modeling Market Insights
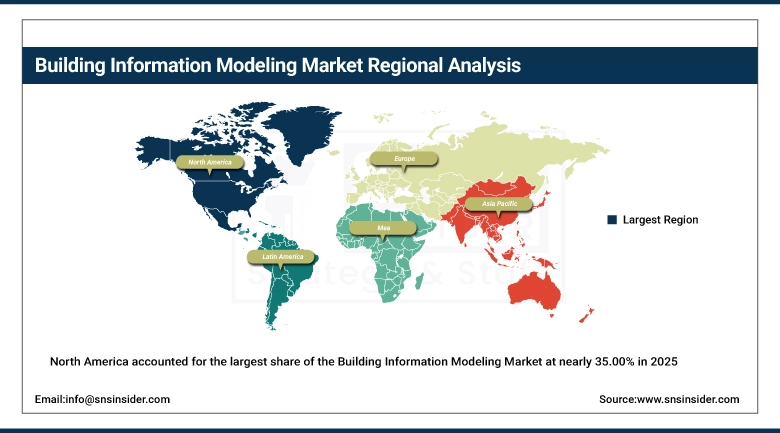
North America Building Information Modeling Market accounted for the largest share at nearly 35.00% in 2025, supported by widespread contractor and AEC-firm adoption, expanding public-sector BIM mandates on federally funded infrastructure projects, and a deep base of leading software vendors headquartered in the region. The region's mature construction-technology ecosystem and established vendor-training infrastructure continue reinforcing its position as the leading market for BIM software and services tracked in this report. Owners across multiple sectors increasingly treat BIM adoption as a standard project requirement rather than an optional design enhancement.
The United States accounted for the substantial majority of regional revenue, anchored by a deep base of large contractors, AEC firms and leading software vendors, while Canada contributed a smaller but steadily growing share through expanding public infrastructure investment. Continued investment in cloud-hosted collaboration platforms and AI-assisted design-review tools is expected to reinforce the region's leadership position through the remainder of the forecast period, with several new vendor partnerships already announced.
⮞In 2025, Bluebeam continued expanding its cloud-based markup and collaboration platform integration with leading BIM software across North America, reinforcing growing contractor demand for integrated digital-collaboration tools.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Building Information Modeling Market Insights
Asia Pacific Building Information Modeling Market is growing at the fastest rate among all regions tracked in this report, with a CAGR of around 12.79% between 2026 and 2035. Growth is driven by massive infrastructure and urban-development investment across China and India, rising government mandates requiring BIM on public construction projects, and growing adoption of cloud-hosted platforms among regional contractors seeking to compete with multinational firms on coordination quality. Expanding domestic software-vendor capability across the region is further easing BIM adoption among firms previously priced out of licensing leading Western platforms.
China was the region’s largest revenue share, buoyed by ongoing investment in infrastructure and urban development and a growing pool of domestic contractors adopting BIM for large public projects. India added significant additional demand via its growing infrastructure-investment pipeline and government BIM-mandate initiatives. Japan and South Korea added more demand from established construction-technology standards and rising adoption among their domestic contractor bases. Further investment in infrastructure and vendors should continue to augment the contribution of Asia Pacific throughout the rest of the forecast period.
⮞In 2026, Autodesk continued expanding its regional cloud-platform availability and local-language support across Asia Pacific, connecting regional contractors in China and other markets with coordinated model-based design and construction workflows.
Europe Building Information Modeling Market Insights
Europe Building Information Modeling Market held a meaningful share of global revenue, supported by regulatory mandates requiring BIM on public-sector construction projects across Germany, the United Kingdom and France, and by a deep base of established European software vendors including Nemetschek Group and its subsidiary brands. Regional regulatory harmonization under European Union public-procurement directives continues to reinforce BIM adoption as a standard requirement for government-funded infrastructure projects across member states. Deep AEC specialist talent pools across several member states further reinforce the continent's advanced BIM-adoption maturity relative to many emerging markets.
Germany continued to lead demand at roughly 30.10% of European revenue, supported by its large AEC-firm base and established software-vendor ecosystem, while the United Kingdom and France contributed additional demand through mandatory public-sector BIM requirements alongside growing private-sector adoption. Continued European investment in digital-construction infrastructure should keep regional demand climbing through the forecast period, reinforced by growing EU public-procurement coordination among the bloc's largest member states. Continued infrastructure and vendor investment should further reinforce Europe's contribution through the remainder of the forecast period.
⮞In 2025, Nemetschek Group further integrated Graphisoft and Vectorworks products into European AEC firms, extending, as regional demand for vendor-coordinated and unified BIM workflows increased.
MEA and Latin America Building Information Modeling Market Insights
The Middle East and Africa and Latin America both showed steady growth, driven by large-scale government infrastructure and urban-megaproject investment, growing BIM-mandate adoption on public construction projects, and rising contractor interest in coordination technology to manage increasingly complex project portfolios across both regions. Public infrastructure investment increases are creating new demand channels for BIM software and services among growing contractor bases in both areas, with several governments newly requiring BIM on large public construction tenders over the past two years.
The UAE accounted for the largest demand in the Middle East and Africa, driven by investment in large-scale urban-megaprojects and growing government BIM-mandate initiatives. South Africa contributed through an established construction sector. Brazil took the lion’s share of regional revenue in Latin America. Growing infrastructure-investment programs continue to be key to regional demand for BIM software and services, with Mexico and Argentina’s growing construction sectors and greater contractor interest in coordination technology contributing increasingly importantly to regional revenue. Continued investment in infrastructure and vendors should further boost the share of MEA and Latin America for the remainder of the forecast period.
⮞In 2025, Trimble expanded its construction-technology field-coordination platform integration with leading BIM authoring tools, broadening its reach among contractors managing complex infrastructure projects.
Market Dynamics
Growth Drivers: Public-Sector BIM Mandates and Rising Infrastructure Investment
The industry is driven by expanding public-sector BIM mandates on government-funded construction projects, rising global infrastructure investment, and growing contractor demand for coordination technology to reduce design clashes and costly rework. As owners and public agencies prioritize both project-delivery speed and cost certainty, demand for both software licensing and outsourced modeling services continues rising across developed and emerging markets alike.
Growing cloud-platform adoption is reinforcing this driver by allowing distributed project teams to access a shared model in real time without the IT overhead of traditional on-premises deployment. Continued vendor investment in AI-assisted clash detection and design-review tools is further widening the addressable client base able to justify new software-licensing and services investment.
⮞In 2025, Bentley Systems continued expanding its infrastructure-focused digital-twin and BIM platform integration, reinforcing growing public-sector demand for coordinated infrastructure-project delivery technology.
Restraints: High Implementation Costs and Workforce Training Gaps
High software-licensing and implementation costs continue to be a restraint to faster market-wide expansion, as comprehensive BIM adoption can require significant upfront investment in software, hardware and workforce training before any project-delivery benefit is realized. Smaller contractors and design firms competing on price in commoditized project segments have a particularly hard time absorbing this upfront cost burden relative to larger, better-capitalized competitors.
Persistent workforce training gaps also complicate adoption decisions for some firms, as skilled BIM modelers and coordinators remain in short supply relative to rising industry demand. Because new staff training and certification cycles can take considerable time, some firms continue favoring outsourced services engagements over building comparable in-house modeling capability from scratch.
Opportunities: Emerging-Market Infrastructure Growth and AI-Enabled Design Automation
Growing infrastructure investment across China, India, the Middle East and Latin America represents a significant opportunity, as government BIM mandates and rising urban-development activity create new demand channels for both software vendors and dedicated services providers. Vendors and service firms positioned early in these emerging infrastructure markets stand to capture meaningful share as global BIM adoption continues broadening beyond its traditional North American and European base.
Expansion of AI-enabled design automation and clash-detection technology offers a second opportunity for vendors able to differentiate on coordination speed and accuracy rather than feature breadth alone. Continued collaboration between software vendors and construction-management platform providers is expected to further accelerate this opportunity through the remainder of the forecast period as project-lifecycle integration deepens.
⮞In 2026, RIB Software continued expanding its AI-enabled cost-estimation and BIM-integrated project-management capability, an opportunity multiple contractors are evaluating as they expand digital-construction adoption.
Recent Developments:
-
In 2025, Hexagon AB and Nemetschek Group formed a partnership to accelerate digital-twin and cloud-based AEC adoption, combining Hexagon's reality-capture technology with Nemetschek's design and BIM authoring tools.
-
In 2026, Oracle continued integrating its Aconex project-information-management platform with leading BIM authoring tools, aiming to streamline document and model coordination for large capital-project owners.
-
In 2025, Asite Solutions expanded its cloud-based project-information-management platform to additional infrastructure-project clients, adding BIM-model coordination capability for public-sector capital programs.
-
In 2025, PTC continued expanding its product-lifecycle-management software integration with BIM-adjacent industrial-design workflows, broadening its reach among manufacturing and industrial-facility owners.
Building Information Modeling Companies are:
-
Autodesk Inc.
-
Bentley Systems Inc.
-
Nemetschek Group
-
Dassault Systèmes SE
-
Siemens AG
-
Hexagon AB
-
AVEVA Group plc
-
Procore Technologies Inc.
-
RIB Software SE
-
Asite Solutions Ltd.
-
ACCA Software S.p.A.
-
MagiCAD Group
-
Innovaya LLC
-
Bluebeam Inc.
-
Vectorworks Inc.
-
Synchro Software Ltd.
-
Oracle Corporation
-
PTC Inc.
Building Information Modeling Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 9.34 Billion |
| Market Size by 2035 | USD 29.63 Billion |
| CAGR | CAGR of 12.24% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Component (Software & Solutions and Services) • By Deployment Mode (On-Premises and Cloud) • By Project Lifecycle (Preconstruction, Construction, and Operation) • By Application (Industrial, Commercial, Residential, and Public Infrastructure) • By End User (Consultants & Facility Managers, AEC Professionals, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Autodesk Inc., Bentley Systems Inc., Trimble Inc., Nemetschek Group, Dassault Systèmes SE, Siemens AG, Hexagon AB, Graphisoft SE, AVEVA Group plc, Procore Technologies Inc., RIB Software SE, Asite Solutions Ltd., ACCA Software S.p.A., MagiCAD Group, Innovaya LLC, Bluebeam Inc., Vectorworks Inc., Synchro Software Ltd., Oracle Corporation, PTC Inc. |

Frequently Asked Questions
Key players include Autodesk, Bentley Systems, Trimble, Nemetschek Group, Dassault Systèmes, Siemens, Hexagon AB, Graphisoft, AVEVA Group and Procore Technologies, among others.
Key opportunities include growing infrastructure investment across China, India, the Middle East and Latin America, and expansion of AI-enabled design automation and clash-detection technology.
The market is driven by expanding public-sector BIM mandates on government-funded construction projects, rising global infrastructure investment, and growing contractor demand for coordination technology.
The Software & Solutions segment dominated the Building Information Modeling Market, accounting for approximately 57.00% share in 2025.
