
Coherent Optical Equipment Market Report Scope & Overview:
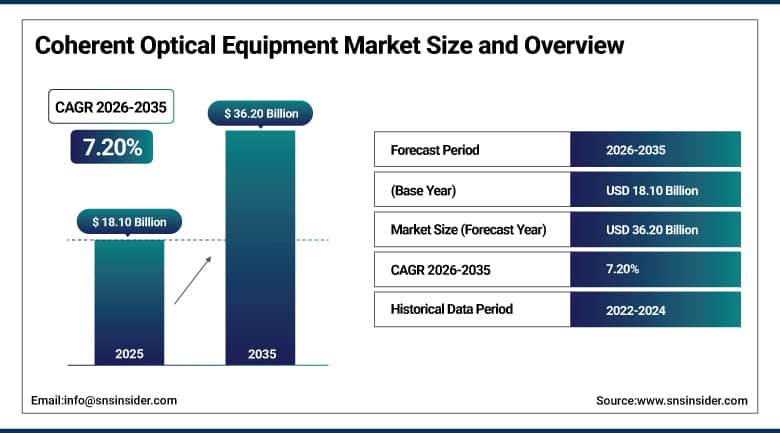
The Coherent Optical Equipment Market was valued at USD 18.10 Billion in 2025 and is expected to reach USD 36.20 Billion by 2035, growing at a CAGR of 7.20% from 2026 to 2035.
The Coherent Optical Equipment Market is experiencing rapid growth because of growing needs for high bandwidth data center interconnect networks, fast-growing 5G, and next generation telecom networks, as well as growing adoption of cloud computing and hyperscale data centers. Coherent optical equipment, such as transceivers, modules, amplifiers, transmission systems, and digital signal processors, employs advanced modulation and coherent detection techniques that help deliver much more data through the existing fiber optic networks than the intensity modulated technologies do, thus becoming an important technology for telecom companies and hyperscalers facing increasing volumes of network traffic.
In addition, the market growth is driven by growing workloads related to AI and machine learning requiring high-speed optical transmission among data centers, continuous innovations in coherent optical transceiver technologies aimed at boosting speeds and power efficiencies, and increasing adoption of pluggable coherent optical modules.
Ciena and Cisco both expanded their pluggable coherent optical transceiver production capacity in 2026 to meet surging demand from hyperscale data center operators and telecom carriers scaling network capacity to support rapidly growing AI workload traffic between data center facilities worldwide.
To Get More Information On Coherent Optical Equipment Market - Request Free Sample Report
Coherent Optical Equipment Market Trends
- Rising demand for high-capacity data center interconnect networks is being driven by explosive growth in AI and machine learning workloads requiring massive data transfer between geographically distributed data center facilities.
- Growing expansion of pluggable coherent optical modules is simplifying data center interconnect network architecture, reducing power consumption and physical footprint compared to traditional embedded coherent systems.
- Increasing rollout of 5G and next-generation telecom infrastructure is driving sustained coherent optical equipment demand as carriers upgrade backhaul and transport networks to support higher-bandwidth mobile services.
- Expanding submarine and long-haul network investment is supporting international data traffic growth, requiring increasingly sophisticated coherent optical transmission technology capable of extending signal reach across vast distances.
- Strategic partnerships among optical equipment manufacturers, telecom carriers, and hyperscale data center operators are supporting development of increasingly efficient, higher-capacity coherent optical solutions.
The U.S. Coherent Optical Equipment Market Outlook
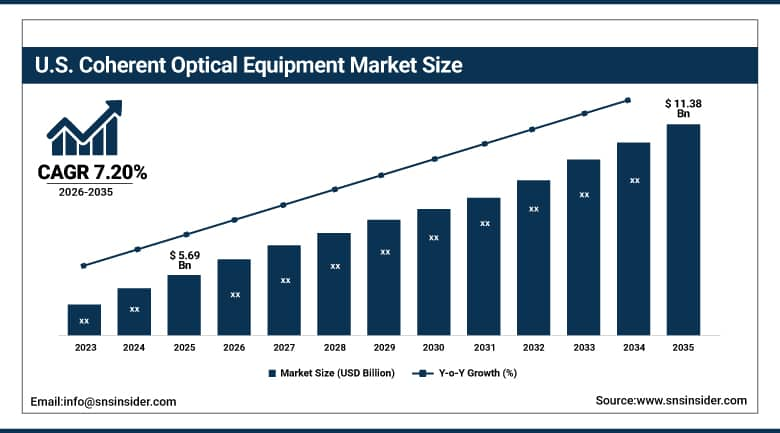
The U.S. Coherent Optical Equipment Market was valued at USD 5.69 Billion in 2025 and is projected to reach USD 11.38 Billion by 2035, growing at a CAGR of 7.20% during 2026–2035.
The main telecom players in the country along with the operators of the hyperscale data centers continue to invest more in coherent optical technology due to the increasing workloads of AI traffic as well as the rollout of 5G network infrastructure. The increasing number of hyperscale data centers being constructed for the support of cloud computing and the expansion of AI infrastructure, alongside the continued investments in data center interconnect and metro networks, continue to fuel domestic demand for advanced coherent optical transceivers, amplifiers, and transmission systems.
In 2026, Ciena expanded its U.S. manufacturing capacity for its WaveLogic coherent optical platform to meet growing hyperscale data center operator demand for higher-capacity, more power-efficient optical transmission technology supporting AI infrastructure expansion.
Coherent Optical Equipment Market Segment Analysis
- By Data Rate, 200G/400G dominated the coherent optical equipment market with a 42.60% share in 2025, while 800G & above is the fastest-growing data rate segment with a CAGR of 15.40% from 2026–2035.
- By Component, coherent transceivers & modules dominated the coherent optical equipment market with a 33.90% share in 2025, while dsps is the fastest-growing component segment with a CAGR of 12.90% from 2026–2035.
- By Application, data center interconnect dominated the coherent optical equipment market with a 44.60% share in 2025, while long-haul & submarine networks is the fastest-growing application segment with a CAGR of 9.80% from 2026–2035.
- By End User, telecom service providers dominated the coherent optical equipment market with a 46.80% share in 2025, while cloud/hyperscale data center operators is the fastest-growing end user segment with a CAGR of 11.60% from 2026–2035.
By Data Rate, 200G/400G dominated the coherent optical equipment market, while 800G & above is the fastest-growing segment.
The 200G/400G segment dominated the coherent optical equipment market with a revenue share of 42.60% in 2025. This particular range continues to represent the biggest segment in terms of its popularity as an industry standard for enhancing the capacity of networks due to increased deployment of 200G and 400G coherent systems by service providers to handle the increased demand at costs efficient compared to the most advanced data rates.
The 800G & above segment is expected to witness the fastest CAGR of 15.40% during the forecast period 2026-2035. Growing AI and machine learning workload demand for maximum bandwidth data center interconnect capacity is driving rapid adoption of 800G and higher coherent optical equipment, as hyperscale operators increasingly prioritize the highest available transmission speeds to support increasingly data-intensive AI training and inference infrastructure requirements.
By Component, coherent transceivers & modules dominated the coherent optical equipment market, while DSPs is the fastest-growing segment.
The coherent transceivers & modules segment dominated the coherent optical equipment market with a revenue share of 33.90% in 2025. Coherent transceivers and modules remain the dominant component category owing to their essential role in enabling high-speed data transmission, serving as the fundamental interface converting electrical signals into modulated optical signals capable of carrying substantially higher data volumes over existing fiber infrastructure than conventional intensity-modulated alternatives, making them the single largest capital equipment category within coherent optical network deployments worldwide.
The DSPs segment is anticipated to register the fastest CAGR of 12.90% during the forecast period 2026-2035. Technological advancements in coherent optical technologies are fueling the development of more efficient digital signal processors, enabling improved performance and reduced power consumption that continues to enhance overall network efficiency, as DSP innovation increasingly determines the achievable data rate and reach of modern coherent optical transmission systems supporting next-generation network capacity requirements.
By Application, data center interconnect dominated the coherent optical equipment market, while long-haul & submarine networks is the fastest-growing segment.
The data center interconnect segment dominated the coherent optical equipment market with a revenue share of 44.60% in 2025. Data center interconnect remains the largest application category owing to rising demand for high-capacity connectivity between geographically distributed data center facilities, driven substantially by explosive growth in AI and cloud computing workloads requiring massive, low-latency data transfer capacity between hyperscale data center campuses.
The long-haul & submarine networks segment is expected to register the fastest CAGR of 9.80% during the forecast period 2026-2035. Growing international data traffic and expanding submarine cable investment supporting global internet connectivity is driving strong demand for advanced coherent optical transmission technology capable of extending signal reach across vast oceanic and continental distances while maintaining signal integrity.
By End User, telecom service providers dominated the coherent optical equipment market, while cloud/hyperscale data center operators is the fastest-growing segment.
The telecom service providers segment dominated the coherent optical equipment market with a revenue share of 46.80% in 2025. Telecom service providers remain the largest end-user category owing to their extensive network infrastructure spanning metro, regional, and long-haul transport networks, where coherent optical equipment upgrades continue to represent a core, ongoing capital investment priority supporting growing mobile and fixed broadband traffic demand.
The cloud/hyperscale data center operators segment is expected to register the fastest CAGR of 11.60% during the forecast period 2026-2035. Rapid expansion of cloud computing and AI infrastructure investment among major hyperscale operators is driving strong demand for coherent optical equipment supporting data center interconnect applications, as these operators increasingly prioritize network capacity expansion to support growing AI training and inference workload traffic.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
85.00% |
|
Europe |
Germany |
27.60% |
|
Asia Pacific |
China |
44.80% |
|
Middle East & Africa |
UAE |
25.60% |
|
Latin America |
Brazil |
37.70% |
North America Coherent Optical Equipment Market Insights
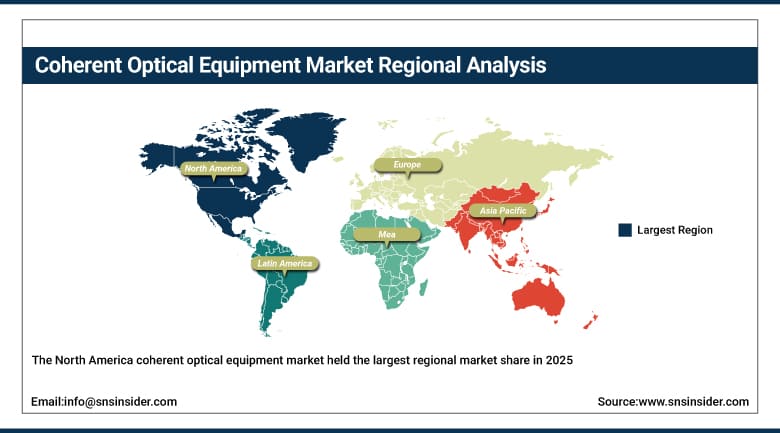
The North America coherent optical equipment market held the largest regional market share in 2025 owing to extensive hyperscale data center construction, strong telecom infrastructure investment, and rapid AI workload growth driving substantial data center interconnect capacity expansion across the region's major cloud and telecom operators.
The US was the leading country within the North America coherent optical equipment market in 2025 with a market share of 85.00% of the regional market, driven by extensive hyperscale data center construction, strong 5G network infrastructure investment, and substantial domestic coherent optical equipment manufacturing capability. Canada is contributing to regional growth through its own expanding data center infrastructure investment and growing telecom network modernization initiatives.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Coherent Optical Equipment Market Insights
The Europe region was a major contributor to the coherent optical equipment market in 2025. This is attributed to the region's substantial telecom infrastructure modernization investment, growing data center construction supporting cloud computing expansion, and strong presence of leading coherent optical equipment manufacturers serving both European and international markets.
Germany is one of the major markets in Europe owing to its strong telecom and data center infrastructure investment and presence of leading optical networking technology providers. Other countries such as the United Kingdom and France are also contributing to market growth through expanding 5G network deployment and growing hyperscale data center construction investment.
Asia Pacific Coherent Optical Equipment Market Insights
The Asia Pacific coherent optical equipment market is expected to witness the fastest growth rate during the forecast period 2026-2035. The market growth is driven by rapid data center construction expansion, extensive 5G network deployment, and growing domestic coherent optical equipment manufacturing capability across the region's major and emerging economies.
China is one of the main growth drivers in the Asia Pacific coherent optical equipment market, owing to its massive telecom infrastructure investment and rapidly expanding domestic optical networking equipment manufacturing base. Japan, South Korea, and India are also contributing to regional growth through expanding 5G network deployment and growing hyperscale data center construction investment supporting cloud and AI infrastructure expansion.
Middle East & Africa and Latin America Coherent Optical Equipment Market Insights
Middle East & Africa and Latin American regions are gradually expanding coherent optical equipment adoption as telecom and data center infrastructure investment grows across both regions, supported by increasing regional cloud computing and digital transformation initiatives.
Brazil is set to be a prominent Latin American market fueled by growing telecom infrastructure investment and expanding data center construction capacity. The Middle East & Africa region has UAE and Saudi Arabia investing heavily in digital infrastructure and data center development as part of broader smart-city and economic diversification strategies, driving sustained demand for advanced coherent optical transmission technology.
Market Dynamics
Growth Drivers: Rising data center interconnect demand and 5G expansion driving market growth
The rising demand for high-capacity data center interconnect networks, rapid expansion of 5G and next-generation telecom infrastructure, and increasing adoption of cloud computing and hyperscale data centers are among the primary drivers of the Coherent Optical Equipment Market. Coherent optical equipment enables telecom carriers and hyperscale operators to transmit substantially more data over existing fiber infrastructure, making it essential technology for managing exponentially growing network traffic across virtually every major digital infrastructure category.
Continuous advancements in coherent optical transceiver technologies have significantly improved transmission speed, reach, and power efficiency across modern optical networking equipment. Growing AI and machine learning workloads driving high-speed optical transmission needs, expanding deployment of pluggable coherent optical modules in data center interconnect applications, and rising international data traffic supporting submarine and long-haul network investment are further supporting demand across the forecast period, as coherent optical technology continues underpinning the global digital infrastructure supporting cloud computing, streaming, and AI applications.
Restraints: High deployment costs and technical complexity limiting market expansion
One of the main barriers to market growth is the high deployment and system integration cost of coherent optical solutions, which can constrain adoption among smaller telecom carriers and regional network operators with limited capital budgets relative to major hyperscale operators and tier-one carriers.
Additionally, technical complexity and power consumption limitations in advanced optical networks continue to present engineering challenges for equipment manufacturers seeking to deliver higher data rates without proportionally increasing energy requirements, particularly important as data center operators face growing scrutiny of overall facility power consumption. The specialized technical expertise required to design, deploy, and maintain coherent optical networks further constrains the pace of adoption among operators lacking dedicated optical networking engineering resources.
Opportunities: Expansion of AI-driven data center capacity and pluggable module adoption creating new growth avenues
The rapid expansion of AI-driven data center capacity requiring maximum bandwidth interconnect capability, growing pluggable coherent optical module adoption simplifying network architecture, and increasing submarine and long-haul network investment are expected to generate substantial opportunities for the Coherent Optical Equipment Market. Rising demand for higher-capacity, more power-efficient optical transmission technology is anticipated to support strong future demand across telecom, cloud, and enterprise applications.
There is a considerable growth opportunity in the continued development of 800G and higher coherent optical technology addressing the most demanding AI infrastructure data center interconnect requirements. The expansion of 5G network deployment and hyperscale data center construction in emerging markets across Asia Pacific and the Middle East is likely to unlock substantial new demand throughout the forecast period.
Recent Developments:
- 2025: Nokia completed its acquisition of Infinera, expanding its optical networking portfolio and strengthening its position to serve growing data center interconnect demand driven by artificial intelligence infrastructure expansion.
- 2025: Ciena launched an updated WaveLogic 6 coherent optical platform, offering enhanced transmission capacity and power efficiency for telecom carriers and hyperscale data center operators.
- 2026: Cisco introduced a new pluggable coherent optical module for data center interconnect applications, simplifying network architecture while reducing power consumption for hyperscale operator customers.
- 2026: Huawei launched an updated 800G coherent optical transmission system, targeting operators seeking maximum bandwidth capacity to support rapidly growing AI workload traffic between data center facilities.
Coherent Optical Equipment Market key players are:
- Ciena Corporation
- Huawei Technologies Co., Ltd.
- Cisco Systems, Inc.
- Nokia Corporation
- Infinera Corporation
- Fujitsu Limited
- Ribbon Communications Inc.
- ZTE Corporation
- ADVA Optical Networking SE
- Telefonaktiebolaget LM Ericsson
- NEC Corporation
- Lumentum Holdings Inc.
- Marvell Technology, Inc.
- Coherent Corp. (II-VI Incorporated)
- Acacia Communications, Inc. (Cisco)
- Applied Optoelectronics, Inc.
- ECI Telecom Ltd.
- Juniper Networks, Inc.
- Sumitomo Electric Industries, Ltd.
- Mitsubishi Electric Corporation
Coherent Optical Equipment Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 18.10 Billion |
| Market Size by 2035 | USD 36.20 Billion |
| CAGR | CAGR of 7.20% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Component (Coherent Transceivers & Modules, Optical Amplifiers, Coherent Optical Transmission Systems, DSPs) • By Data Rate (100G, 200G/400G, 800G & Above) • By Application (Data Center Interconnect, Metro Networks, Long-Haul & Submarine Networks) • By End User (Telecom Service Providers, Cloud/Hyperscale Data Center Operators, Enterprises) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Ciena Corporation, Huawei Technologies Co., Ltd., Cisco Systems, Inc., Nokia Corporation, Infinera Corporation, Fujitsu Limited, Ribbon Communications Inc., ZTE Corporation, ADVA Optical Networking SE, Telefonaktiebolaget LM Ericsson, NEC Corporation, Lumentum Holdings Inc., Marvell Technology, Inc., Coherent Corp. (II-VI Incorporated), Acacia Communications, Inc. (Cisco), Applied Optoelectronics, Inc., ECI Telecom Ltd., Juniper Networks, Inc., Sumitomo Electric Industries, Ltd., Mitsubishi Electric Corporation. |
Frequently Asked Questions
The Coherent Optical Equipment Market is expected to grow at a CAGR of 7.20% from 2026 to 2035.
The Coherent Optical Equipment Market was valued at USD 18.10 Billion in 2025.
The market is driven by rising demand for high-capacity data center interconnect networks, rapid 5G expansion, and increasing adoption of cloud computing and hyperscale data centers.
The Coherent Transceivers & Modules segment dominated the Coherent Optical Equipment Market in 2025, accounting for approximately 33.90% market share.
The North America region dominated the Coherent Optical Equipment Market in 2025.
