
Drilling Data Management Systems Market Report Scope & Overview:
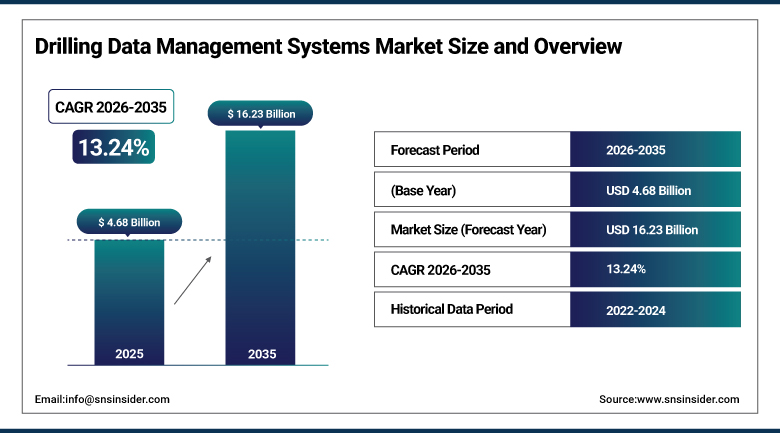
The Drilling Data Management Systems Market was valued at USD 4.68 Billion in 2025 and is expected to reach USD 16.23 Billion by 2035, growing at a CAGR of 13.24% from 2026-2035.
The Drilling Data Management Systems Market continues to expand as operators, drilling contractors, and oilfield service companies seek to capture, integrate, and analyze the growing volume of data generated during well construction. Modern rigs produce continuous streams of information from electronic drilling recorders, measurement-while-drilling and logging-while-drilling tools, mud logging systems, and rig control equipment. Drilling data management systems collect, standardize, store, and deliver this information to engineers in real time, supporting faster decisions, safer operations, and lower well costs. The adoption of WITSML and other data standards, cloud platforms, and edge computing is improving data quality and accessibility across rigs and remote operations centers. Operators increasingly treat drilling data as a strategic asset that supports well planning, performance benchmarking, and continuous improvement across drilling programs. Artificial intelligence and automation are increasing the value of drilling data, enabling predictive analytics, automated drilling control, and closed-loop optimization. Rising complexity of horizontal, extended-reach, and deepwater wells, together with pressure to reduce costs and emissions, is supporting the steady, resilient long-term growth trajectory of the global drilling data management systems market.
To Get more information Drilling Data Management Systems Market - Request Free Sample Report
⮞Real-time drilling data integration advanced when Innova Drilling & Intervention integrated, in July 2026, PV Fluid Products power section performance data into its cloud-based Vantage drilling platform, combining manufacturer curves with live MWD and electronic drilling recorder data to create a temperature-adjusted operating envelope.
Drilling Data Management Systems Market Trends
-
Rising adoption of cloud-based drilling data platforms and remote operations centers.
-
Growing use of edge computing for real-time analytics at the rig site.
-
Expanding deployment of AI-driven predictive drilling and automated setpoint control.
-
Increasing adoption of WITSML and open data standards across drilling contractors.
-
Rising integration of drilling data with well planning and digital twin solutions.
-
Growing demand for drilling data analytics to reduce well costs and emissions.
U.S. Drilling Data Management Systems Market Outlook
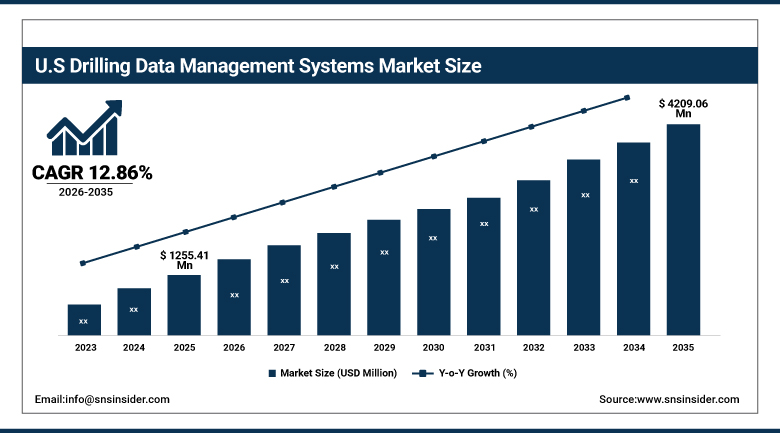
The U.S. Drilling Data Management Systems Market was valued at USD 1,255.41 Million in 2025 and is expected to reach USD 4,209.06 Million by 2035, growing at a CAGR of 12.86% from 2026-2035.
The U.S. Drilling Data Management Systems Market continues to grow steadily on the strength of high horizontal drilling activity, advanced rig automation, and strong adoption of data-driven drilling practices among shale operators. Operators in the Permian Basin, Eagle Ford, Bakken, Haynesville, and Appalachia drill large numbers of long-lateral wells, where real-time data and analytics help improve rate of penetration, reduce nonproductive time, and maintain wellbore placement. Drilling contractors including Helmerich & Payne, Nabors, and Patterson-UTI deploy rig automation and edge computing platforms that generate and use large volumes of data. Software providers such as Corva, Pason Systems, Petrolink, and the major service companies support remote monitoring centers in Houston, Denver, and Oklahoma City. Consolidation among shale producers and their contractors is increasing demand for standardized data platforms across merged portfolios. Low-earth orbit satellite connectivity is also improving data transfer from remote rigs. Deepwater drilling in the Gulf of America adds further demand for advanced data systems. These factors position the United States as the largest country market for drilling data management systems worldwide.
⮞Data-driven rig automation in the United States expanded when Helmerich & Payne announced, in October 2026, plans to deploy seven additional FlexRobotics automated drilling systems for ExxonMobil over the following 12 months, extending the use of automated pipe handling and rig floor operations across its fleet.
Drilling Data Management Systems Market Segment Analysis
-
By Component, the Software segment dominated the Drilling Data Management Systems Market with approximately 48.62% share in 2025, while the Services segment is the fastest growing with a CAGR of approximately 14.68%.
-
By Deployment, the On-Premises segment dominated the Drilling Data Management Systems Market with approximately 51.24% share in 2025, while the Cloud segment is the fastest growing with a CAGR of approximately 16.42%.
-
By Application, the Real-Time Monitoring segment dominated the Drilling Data Management Systems Market with approximately 34.26% share in 2025, while the Drilling Optimization segment is the fastest growing with a CAGR of approximately 15.12%.
-
By Location, the Onshore segment dominated the Drilling Data Management Systems Market with approximately 64.38% share in 2025, while the Offshore segment is the fastest growing with a CAGR of approximately 13.96%.
By Component, Software Dominates the Drilling Data Management Systems Market and Services Grows Fastest
Software led the market in 2025, as operators and contractors rely on data aggregation platforms, visualization tools, analytics applications, and drilling engineering software to manage well construction data. Many platforms now support open application programming interfaces. Solutions from SLB, Halliburton, Baker Hughes, NOV, Pason Systems, Petrolink, and Corva collect data from rig sensors and downhole tools, standardize it, and present it to engineers through dashboards and alerts. Subscription models and app-based platforms make it easier for companies to add new capabilities over time. Growing use of AI-enabled analytics for drilling performance and risk detection continues to secure software as the largest component segment in the market.
⮞In October 2026, SLB secured a 15-year digital drilling agreement with TotalEnergies to deploy its DrillPlan well planning and engineering solutions, integrating subsurface data, well trajectories and engineering workflows into a unified digital environment.
Services are the fastest-growing component as operators seek support for data integration, remote monitoring, system configuration, and managed data operations. Smaller operators increasingly rely on such outsourced support models. Many companies operate a mix of legacy and modern rig systems that require specialized expertise to connect and standardize. Remote operations centers staffed by service providers monitor wells around the clock, interpret data, and recommend adjustments to drilling parameters. Data quality assurance, WITSML implementation, and training services are increasingly in demand as companies scale digital drilling programs. Rising outsourcing of drilling data operations, especially among mid-sized operators, continues to drive the fastest growth in the services segment.
By Deployment, On-Premises Dominates the Drilling Data Management Systems Market and Cloud Grows Fastest
On-premises deployment led the market in 2025, as many operators and drilling contractors continue to host drilling data systems at rig sites and in their own data centers. Rig control systems also require very low latency. Rig-site systems must function reliably even when satellite or cellular connectivity is limited, making local processing essential for real-time monitoring and control. National oil companies and operators in certain countries also require local storage of strategic drilling data. Established investments in on-premises infrastructure, along with concerns about cybersecurity and latency for rig control, continue to secure on-premises deployment as the largest deployment segment in the drilling data management systems market.
Cloud deployment is the fastest-growing segment as operators move drilling data to platforms hosted on Microsoft Azure, Amazon Web Services, and Google Cloud to enable collaboration across teams and locations. Hybrid models are also gaining ground. Cloud platforms provide scalable storage for historical well data, elastic computing for analytics and machine learning, and easier access for remote operations centers. Edge computing devices at the rig increasingly connect to cloud platforms, combining local reliability with central analytics. Lower infrastructure costs, faster deployment of new applications, and growing confidence in cloud security continue to drive the fastest growth among deployment segments in the market over the forecast period.
⮞In August 2026, ADNOC and SLB confirmed the deployment of a cloud-hosted, AI-enabled Real-Time Operations Center across more than 120 drilling rigs, integrating live operational data, predictive analytics and performance dashboards within ADNOC's UAE-based sovereign cloud environment.
By Application, Real-Time Monitoring Dominates the Drilling Data Management Systems Market and Drilling Optimization Grows Fastest
Real-time monitoring led the market in 2025, as operators depend on continuous visibility into drilling parameters, downhole conditions, and equipment performance to maintain safety and efficiency. These systems form the foundation for most drilling data workflows. Remote operations centers monitor weight on bit, torque, standpipe pressure, mud properties, and gas readings to detect problems such as kicks, stuck pipe, and equipment failures. Real-time monitoring also supports geosteering and wellbore placement in complex horizontal wells. The essential role of monitoring in well control, safety, and regulatory compliance continues to secure real-time monitoring as the largest application segment in the drilling data management systems market worldwide.
Drilling optimization is the fastest-growing application as operators use analytics, machine learning, and automation to improve rate of penetration, reduce nonproductive time, and extend bit life. Optimization tools are also increasingly integrated with well planning software. Optimization platforms analyze historical and real-time data to recommend or automatically apply optimal drilling parameters through auto driller systems. Integrations such as Nabors RigCLOUD with Corva AI demonstrate how optimized setpoints can be delivered directly to the rig. Rising pressure to lower well costs, combined with the growing availability of high-quality drilling data and edge computing, continues to drive the fastest growth among application segments in the market.
⮞In January 2026, NOV and AIQ announced a collaboration to develop AI-enabled drilling optimization solutions, combining NOV's Max industrial IoT and edge computing platform with AIQ's artificial intelligence for operational testing and pilot deployments.
By Location, Onshore Dominates the Drilling Data Management Systems Market and Offshore Grows Fastest
Onshore drilling led the market in 2025, as land operations account for the majority of wells drilled worldwide, particularly in North American shale basins, the Middle East, China, and Argentina. Shale operators also benefit from repeatable well designs. High drilling activity and short well cycles in onshore unconventional plays create large volumes of data and strong demand for real-time monitoring and optimization. Drilling contractors operating large land rig fleets are deploying automation and data platforms across their rigs. The scale of onshore drilling programs, together with rapid adoption of digital tools by shale operators, continues to secure onshore as the largest location segment in the market.
⮞In March 2026, NOV reported that its Drilling Beliefs & Analytics application had expanded from a two-rig trial to double-digit rigs in Egypt's Western Desert, supporting real-time drilling performance analysis and two operations centers.
Offshore drilling is the fastest-growing location segment as deepwater and ultra-deepwater activity increases in Brazil, Guyana, the Gulf of America, West Africa, and the Eastern Mediterranean. Advanced data systems also support managed pressure drilling operations offshore. Offshore wells are complex and costly, with daily rig rates that make nonproductive time particularly expensive. Operators use advanced data management systems to monitor well control, manage narrow pressure windows, and coordinate drilling teams between offshore rigs and onshore centers. Rising investment in deepwater projects and growing adoption of remote operations to reduce offshore personnel continue to drive the fastest growth in the offshore segment over the forecast period.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
North America |
United States |
82.64% |
|
Asia Pacific |
China |
38.42% |
|
Europe |
Norway |
32.86% |
|
Latin America |
Brazil |
44.28% |
|
Middle East & Africa |
Saudi Arabia |
36.74% |
North America Drilling Data Management Systems Market Insights
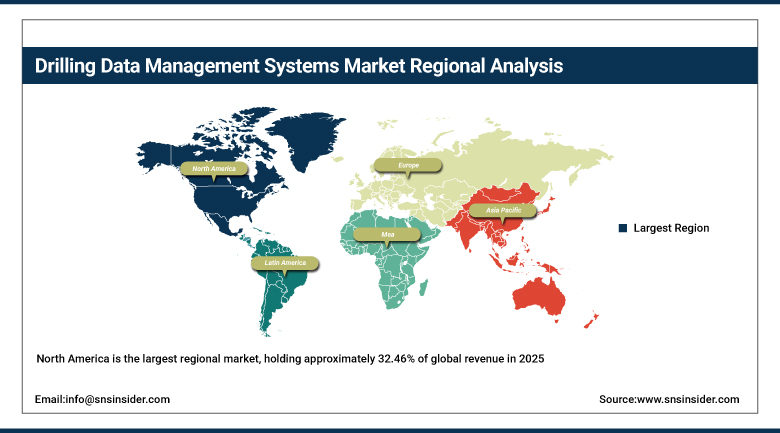
North America is the largest regional market, holding approximately 32.46% of global revenue in 2025, supported by intensive shale drilling, advanced rig automation, and strong adoption of digital drilling technologies. Large operators also maintain dedicated drilling data teams that work closely with technology vendors to develop new analytics, automation, and visualization tools. SLB, Halliburton, Baker Hughes, NOV, Nabors, Helmerich & Payne, Pason Systems, Petrolink, and Corva provide data platforms, automation systems, and remote monitoring services across the region. Long-lateral horizontal wells and pad drilling generate large data volumes, while operators increasingly rely on remote operations centers and AI-based analytics to improve drilling efficiency and reduce well construction costs.
Get Customized Report as per Your Business Requirement - Enquiry Now
⮞In July 2026, SLB reported that its Retina at-bit imaging system had been deployed in more than 50 wells across 16 locations worldwide, including U.S. land and Gulf of America operations, supporting real-time formation data acquisition.
The United States anchors regional demand through drilling activity in the Permian Basin, Eagle Ford, Bakken, Haynesville, and Appalachia, along with deepwater drilling in the Gulf of America. Many drilling contractors also run remote centers. Canada contributes through drilling in the Montney and Duvernay formations and oil sands operations in Alberta, where Pason Systems and other providers support rig data acquisition and management. Mexico is modernizing drilling operations through Pemex and private operators. Strong technology adoption, rig automation programs, and data-driven drilling practices among leading operators are expected to keep North America the largest regional market for drilling data management systems over the forecast period.
Asia Pacific Drilling Data Management Systems Market Insights
Asia Pacific is the fastest-growing regional market, holding approximately 21.84% of global revenue in 2025 and expanding at a CAGR of approximately 14.86% from 2026 to 2035. National oil companies across the region are also partnering with international service companies to deploy remote operations centers and intelligent drilling platforms. The region's growth reflects increasing drilling activity, expanding offshore exploration, and digital transformation programs at national oil companies. China's CNPC, Sinopec, and CNOOC are investing in intelligent drilling systems, real-time data platforms, and automation to improve efficiency in deep, tight, and shale reservoirs. Chinese technology providers are also developing local drilling software and rig automation solutions for regional use.
⮞In July 2026, CNPC's Chuanqing Drilling deployed its domestically developed QN-IDOS intelligent drilling system in Sichuan, upgrading 12 conventional rigs with automated drilling, intelligent reaming, remote monitoring and automated well-control capabilities.
India is a major growth contributor, as ONGC and Oil India expand onshore and offshore drilling programs and adopt real-time monitoring and remote operations centers. Regional governments are also supporting digital skills development and local technology capabilities. Malaysia's PETRONAS, Indonesia's Pertamina, and Thailand's PTTEP are investing in digital drilling technologies for offshore fields. Australia contributes through offshore gas drilling and coal seam gas development that require efficient data management. Rising energy demand, offshore exploration, and government support for digital oilfield initiatives across the region are expected to keep Asia Pacific the fastest-growing regional market for drilling data management systems over the forecast period.
Europe Drilling Data Management Systems Market Insights
Europe holds a significant share of the Drilling Data Management Systems Market, supported by mature offshore drilling in the North Sea and strong digital leadership among Norwegian operators. Data from the Norwegian Continental Shelf also supports industry research on drilling performance. Norway is the largest country market, where Equinor and Aker BP have adopted drilling automation, remote operations, and integrated data platforms from Kongsberg Digital, Exebenus, and the major service companies. Norway's regulatory environment encourages data sharing and safety monitoring, increasing demand for reliable drilling data systems. Offshore drilling contractors operating in the region are also deploying automation and real-time data analytics on their rigs.
⮞In December 2025, Norway's Ocean Industry Authority issued a regulatory order requiring Equinor to demonstrate that its NOVOS automated drilling control technology meets qualification requirements before expanding deployment to additional facilities, reinforcing digital drilling safety oversight.
The United Kingdom, the Netherlands, Denmark, and Italy contribute through offshore drilling, plug and abandonment campaigns, and geothermal and carbon storage well projects that require detailed drilling data. European operators are also exploring drilling data applications for hydrogen storage and lithium brine wells. Operators in the region focus on reducing emissions and personnel on board, encouraging remote operations and automated drilling. Strict regulatory requirements for well integrity and reporting increase demand for accurate, auditable drilling records. Strong technology adoption, energy transition well projects, and stringent safety standards are expected to keep Europe a significant regional market for drilling data management systems over the forecast period.
MEA & Latin America Drilling Data Management Systems Market Insights
The Middle East & Africa represents a significant and growing market, led by Saudi Arabia, the United Arab Emirates, Kuwait, and Qatar. Regional operators are also partnering with global service companies and technology providers to deploy automated drilling, real-time analytics, and integrated data platforms. National oil companies including Saudi Aramco, ADNOC, and Kuwait Oil Company are drilling large numbers of wells to sustain and expand production capacity, while investing in remote operations centers, AI, and drilling automation. Data sovereignty requirements encourage local data centers and in-country cloud regions. In Africa, Nigeria, Angola, and Namibia are increasing offshore exploration and development drilling, creating demand for advanced data systems.
⮞In January 2026, Abu Dhabi-based AIQ partnered with NOV to develop AI-driven drilling technologies, combining AIQ's industrial AI capabilities with NOV's Max industrial IoT platform for real-time drilling optimization and edge-based data processing.
Latin America is developing steadily, supported by Brazil, Argentina, Guyana, and Mexico. Regional service companies are also adopting cloud-based drilling data platforms to support new projects. Brazil's Petrobras operates complex deepwater pre-salt wells that rely on advanced drilling data management, real-time monitoring, and remote operations centers. Argentina's Vaca Muerta shale development is driving onshore drilling activity and adoption of North American digital drilling practices. Guyana's rapidly growing offshore developments require advanced data systems from the start of drilling campaigns. Expanding deepwater and shale activity, together with rising digital adoption among operators, is expected to support steady growth across both regions over the forecast period.
Market Dynamics
Growth Drivers: Rising Drilling Complexity and Growing Adoption of Rig Automation and AI
Rising drilling complexity represents the primary driver of Drilling Data Management Systems Market growth, as operators drill longer horizontal laterals, extended-reach wells, high-pressure high-temperature wells, and deepwater wells that require precise control. Higher data volumes also require more robust storage, governance, and quality control processes. Complex wells generate large volumes of surface and downhole data that must be monitored in real time to manage risks such as well control incidents, stuck pipe, and wellbore instability. Accurate data supports geosteering decisions that keep wells in the most productive zones. Increasing well complexity worldwide continues to expand demand for advanced drilling data management and real-time monitoring solutions.
⮞In July 2026, SLB reported that Kuwait Oil Company awarded four Innovation Factori AI collaborations, including AI-driven rig scheduling and AI-based well-log quality control and reconstruction, supporting digital integration across complex upstream workflows.
Growing adoption of rig automation and AI is further strengthening market growth, as drilling contractors and operators deploy automated drilling control, robotic pipe handling, and machine learning models that depend on high-quality data. Contractors increasingly differentiate their rig fleets through automation and data capabilities. Automated systems such as auto drillers and closed-loop optimization platforms use real-time data to adjust drilling parameters and improve consistency. Edge computing platforms such as Nabors RigCLOUD and analytics providers such as Corva enable AI-driven recommendations at the rig site. Proven reductions in drilling time and costs are encouraging wider deployment of automation and data management systems across rig fleets.
Restraints: High Implementation Costs and Data Integration and Connectivity Challenges
High implementation costs remain a key restraint on the Drilling Data Management Systems Market, as deploying sensors, edge computing hardware, software platforms, and remote operations centers requires significant investment. Return on investment can also be difficult to demonstrate during the early stages of deployment. Smaller operators and drilling contractors may struggle to justify these costs, particularly during periods of low oil prices or reduced drilling budgets. Licensing fees, system upgrades, and ongoing support add to total ownership costs. Cyclical drilling activity can lead companies to delay or reduce digital investments, slowing adoption of new data management systems in certain regions and market segments over time.
Data integration and connectivity challenges further restrain market growth, as drilling data comes from many different rig systems, service providers, and downhole tools that often use incompatible formats. Shortages of skilled data engineers and drilling specialists can further slow adoption. Inconsistent data quality, missing metadata, and proprietary interfaces make it difficult to combine information into a single reliable view. Limited bandwidth at remote land and offshore locations restricts real-time data transfer to central platforms. Cybersecurity concerns about connecting rig control systems to enterprise networks add further complexity. These challenges can increase project timelines and reduce the value companies capture from drilling data investments.
Opportunities: Cloud and Edge Computing Integration and Expansion into Geothermal and Carbon Storage Drilling
Cloud and edge computing integration presents significant opportunities for the Drilling Data Management Systems Market, as operators seek to combine reliable rig-site processing with centralized analytics and collaboration. Low-earth orbit satellite connectivity is also improving data transfer from remote rigs. Edge devices can run AI models and automated control at the rig even with limited connectivity, while cloud platforms store historical data and support large-scale analysis across fleets. Open app ecosystems allow operators to add specialized applications from multiple vendors. Providers that combine edge computing, cloud platforms, and open data standards can capture growing demand from operators and contractors modernizing drilling operations.
⮞In June 2026, Fervo Energy, Pacific Northwest National Laboratory and NVIDIA announced development of EGS-Twin, a geothermal digital twin platform combining real-time field data, physics-based modeling and AI forecasting to improve subsurface monitoring and operational decisions.
Expansion into geothermal and carbon storage drilling presents a further opportunity, as next-generation geothermal projects and carbon capture and storage developments require wells drilled with oil and gas techniques. Government funding for geothermal demonstration projects is also supporting this emerging application. Enhanced geothermal systems in the United States, Europe, and other regions use horizontal drilling in hot, hard rock formations, where real-time data and optimization can significantly reduce costs. Carbon storage wells require detailed drilling and integrity records for regulatory approval and long-term monitoring. Providers that adapt drilling data platforms to these energy transition applications can access new and expanding customer segments.
Recent Developments:
-
May 2026: Halliburton demonstrated its LOGIX automation and remote operations platform, providing closed-loop rig control for drilling and geosteering, along with its ZEUS IQ intelligent fracturing platform, at its Technology Showcase in Houston.
-
April 2026: Nabors and Corva expanded their strategic alliance, integrating Nabors' RigCLOUD edge computing platform with Corva AI predictive analytics to deliver optimized Auto Driller setpoints directly to rig sites, even with limited satellite bandwidth.
Drilling Data Management Systems Market Key Players
-
SLB
-
Halliburton Company
-
Baker Hughes Company
-
Weatherford International plc
-
NOV Inc.
-
Nabors Industries Ltd.
-
Helmerich & Payne, Inc.
-
Pason Systems Inc.
-
Petrolink International Ltd.
-
Corva AI, Inc.
-
Kongsberg Digital AS
-
Emerson Electric Co.
-
Honeywell International Inc.
-
ABB Ltd.
-
Siemens AG
-
Rockwell Automation, Inc.
-
Peloton Computer Enterprises Ltd.
-
Independent Data Services Ltd. (IDS)
-
Innova Drilling & Intervention
-
Exebenus AS
Drilling Data Management Systems Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 4.68 Billion |
| Market Size by 2035 | USD 16.23 Billion |
| CAGR | 13.24% from 2026-2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Component: Dominant – Software (48.62% share in 2025); Fastest-Growing – Services (CAGR 14.68%) • By Deployment: Dominant – On-Premises (51.24% share in 2025); Fastest-Growing – Cloud (CAGR 16.42%) • By Application: Dominant – Real-Time Monitoring (34.26% share in 2025); Fastest-Growing – Drilling Optimization (CAGR 15.12%) • By Location: Dominant – Onshore (64.38% share in 2025); Fastest-Growing – Offshore (CAGR 13.96%) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | SLB, Halliburton Company, Baker Hughes Company, Weatherford International plc, NOV Inc., Nabors Industries Ltd., Helmerich & Payne, Inc., Pason Systems Inc., Petrolink International Ltd., Corva AI, Inc., Kongsberg Digital AS, Emerson Electric Co., Honeywell International Inc., ABB Ltd., Siemens AG, Rockwell Automation, Inc., Peloton Computer Enterprises Ltd., Independent Data Services Ltd. (IDS), Innova Drilling & Intervention, Exebenus AS. |

Frequently Asked Questions
Key players include SLB, Halliburton Company, Baker Hughes Company, Weatherford International plc, NOV Inc., Nabors Industries Ltd., and Pason Systems Inc., among other global drilling technology providers.
Cloud and edge computing integration, along with expansion into geothermal and carbon storage drilling, represent the primary opportunities.
Growth is primarily driven by rising drilling complexity combined with growing adoption of rig automation and AI.
By Location, Onshore dominated the market with approximately 64.38% share in 2025, reflecting high land drilling activity in shale basins and the Middle East.
North America dominated the market with approximately 32.46% share in 2025, driven by intensive shale drilling and advanced rig automation.
