
Dual Carbon Battery Market Report Scope & Overview:
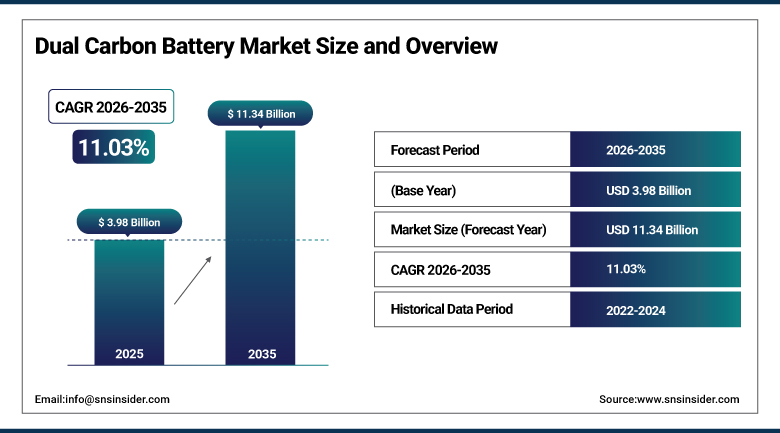
The Dual Carbon Battery Market was valued at USD 3.98 Billion in 2025 and is expected to reach USD 11.34 Billion by 2035, growing at a CAGR of 11.03% from 2026 to 2035.
Dual carbon batteries swap out the nickel and cobalt that lithium-ion cells depend on and build both electrodes from carbon instead, which sounds like a modest engineering choice until you look at what it does to charging speed and supply chain risk. Early commercial cells have demonstrated charge rates up to 20 times faster than conventional lithium-ion, along with materially lower fire risk since there is no metal oxide cathode to drive thermal runaway. That combination has caught the attention of automakers chasing both faster EV charging times and cobalt-free supply chains, while grid-storage developers like the reduced fire-suppression costs that come with a chemistry this stable. The technology is still young commercially, but the pull from both automotive and stationary storage buyers is real.
In July 2025, Contemporary Amperex Technology Co. Limited (CATL) unveiled a dual-power EV battery pack combining dual carbon fast-charge modules with high-energy lithium-ion cells, delivering roughly 930 miles of range for luxury sedan applications.
To Get more information Dual Carbon Battery Market - Request Free Sample Report
Dual Carbon Battery Market Trends
- Automakers are pairing dual carbon fast-charge modules with conventional lithium-ion cells to boost range without a full chemistry overhaul.
- Solid-state electrolyte development is picking up pace as researchers chase better low-temperature performance for dual carbon cells.
- Grid-storage developers are favoring dual carbon chemistries for their reduced fire-suppression and safety-system costs.
- Government pilot-line grants are helping early manufacturers scale production capacity beyond lab and pilot volumes.
- Plant-derived carbon sourcing is emerging as a differentiator among manufacturers competing on sustainability credentials.
The U.S. Dual Carbon Battery Market Outlook
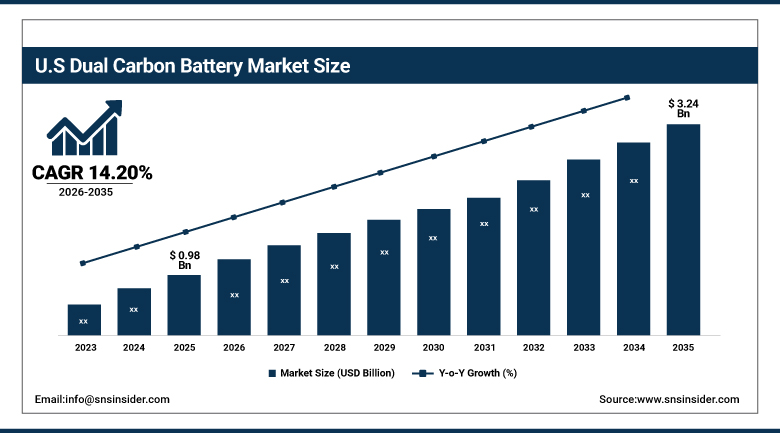
The U.S. dual carbon battery market was valued at USD 0.98 Billion in 2025 and is projected to reach USD 3.24 Billion by 2035, growing at a CAGR of 14.20% during 2026-2035.
Federal battery-module credits have done a lot of the early work here, with several U.S. dual carbon start-ups signing conditional offtake agreements with automakers in 2025 on the strength of Inflation Reduction Act incentives worth up to USD 3,750 per vehicle battery module. That policy support is pulling pilot-scale manufacturing capacity into the country faster than it might have developed otherwise. Grid-storage tenders are adding a second demand pull, since utilities managing wildfire and fire-suppression liability are increasingly specifying chemistries with lower thermal runaway risk. Domestic content requirements tied to EV tax credits are also nudging automakers toward U.S.-based dual carbon suppliers rather than importing cells, which is reshaping where manufacturing investment lands within the country.
In 2025, at least four U.S. automakers signed conditional offtake agreements with domestic dual carbon battery start-ups, supported by Inflation Reduction Act credits worth up to USD 3,750 per vehicle battery module.
Dual Carbon Battery Market Segment Analysis
- By Battery Type, rechargeable dual carbon batteries segment dominated the dual carbon battery market in 2025 with 82% share; primary dual carbon batteries segment is the fastest-growing segment, registering a CAGR of 13.40% from 2026 to 2035.
- By Application, electric vehicles segment dominated the market in 2025 with 57% share; energy storage systems segment is the fastest-growing segment, registering a CAGR of 15.80% from 2026 to 2035.
- By Electrolyte Type, liquid electrolyte segment dominated the market in 2025 with 64% share; solid electrolyte segment is the fastest-growing segment, registering a CAGR of 16.90% from 2026 to 2035.
- By Cell Configuration, pouch cells segment dominated the market in 2025 with 46% share; prismatic cells segment is the fastest-growing segment, registering a CAGR of 12.70% from 2026 to 2035.
By Battery Type, rechargeable dual carbon batteries lead while primary dual carbon batteries gain ground fastest
Rechargeable dual carbon batteries hold 82% of the market, and that dominance tracks pretty closely with where the money is: automotive and grid-storage buyers need cells that survive thousands of charge cycles, not once-and-done power sources. Early commercial cells rated for more than 3,000 cycles, with some lab demonstrations exceeding 8,000, give rechargeable formats a durability profile that is already competitive with mature lithium-ion chemistries. That cycle life, combined with the faster charging inherent to the dual carbon design, is what is pulling automakers and utility-scale storage developers toward this format first.
Primary dual carbon batteries are growing at a 13.40% CAGR through 2035, the fastest pace in the segment, largely on the back of low-power disposable electronics and industrial sensor applications where a rechargeable cell would be overkill. Carbon-based primary cells avoid the toxicity concerns tied to some conventional disposable battery chemistries, which is opening doors in medical devices and remote environmental sensors where end-of-life disposal matters as much as performance.
By Application, electric vehicles dominates while energy storage systems registers the fastest growth
Electric vehicles account for 57% of the dual carbon battery market, driven by automakers chasing both a cobalt-free supply chain story and genuinely faster charging times than conventional lithium-ion packs can offer. Several automakers have moved beyond lab testing into conditional offtake agreements with dual carbon suppliers, treating the chemistry as a complement to existing lithium-ion packs rather than an outright replacement, at least for now. That hybrid approach, pairing dual carbon fast-charge modules with high-energy lithium-ion cells, is proving to be the more practical path to market than a full-chemistry swap.
Energy storage systems are expanding at a 15.80% CAGR, the fastest rate of any application, as utilities and grid operators lean into the chemistry's lower thermal runaway risk. Fire-suppression infrastructure for large-scale battery storage installations is expensive, and a chemistry that meaningfully reduces that cost has an easier time clearing utility procurement reviews. Renewable energy capacity additions, which topped roughly 295 gigawatts globally in a single recent year, are creating exactly the kind of intermittency-management demand that favors safer, longer-cycling storage chemistries like this one.
By Electrolyte Type, liquid electrolyte dominates while solid electrolyte emerges as the fastest-growing format
Liquid electrolyte formulations hold 64% of the market simply because they are the most mature and best-understood option available to manufacturers scaling up production today. Existing lithium-ion manufacturing infrastructure is largely compatible with liquid-electrolyte dual carbon cells, which lowers the capital cost of entering the category compared to solid-state alternatives that often require entirely new production lines.
Solid electrolyte formulations are growing fastest, at a 16.90% CAGR, as manufacturers chase better low-temperature performance and improved safety margins. Recent electrolyte formulations have demonstrated roughly 90% ionic conductivity retention at -40 degrees Celsius while roughly doubling dual carbon cycle life at elevated temperatures, addressing two of the chemistry's historical weak points at once. That kind of performance gain is what is pulling commercialization timelines for solid-state dual carbon cells forward faster than most analysts expected even two years ago.
By Cell Configuration, pouch cells dominates while prismatic cells registers the fastest growth
Pouch cells lead the format category with 46% share, largely because the format suits the flexible, lightweight applications, e-bikes, drones, portable power stations, where dual carbon technology first found commercial traction before automotive buyers took interest. Pouch construction also simplifies manufacturing for smaller producers who do not have the capital for rigid-cell tooling, which has kept it the default choice among early-stage dual carbon manufacturers.
Prismatic cells are growing fastest among configurations, at a 12.70% CAGR, as automotive-scale manufacturing shifts toward the format's better volumetric efficiency for EV battery packs. Large-format prismatic cells pack more energy into a given pack volume than pouch or cylindrical alternatives, which matters more as dual carbon technology moves from niche mobility applications into mainstream EV programs.
Regional Analysis
|
Region |
Country |
Share (2025) |
|
North America |
United States |
88.40% |
|
Asia Pacific |
Japan |
34.60% |
|
Europe |
Germany |
27.90% |
|
Middle East & Africa |
UAE |
16.20% |
|
Latin America |
Brazil |
24.30% |
North America Dual Carbon Battery Market Insights
North America is growing faster than any other region in this market, expanding at roughly a 14.20% CAGR through 2035 on the strength of federal battery-module incentives and a wave of conditional offtake agreements between automakers and domestic dual carbon start-ups. What sets this region apart is not scale yet, Asia Pacific still leads on total revenue, it is the speed at which policy is pulling manufacturing investment toward U.S. soil specifically.
The United States accounts for approximately 88.40% of the North American market, reflecting both its concentration of dual carbon start-ups and the federal incentive structure driving early commercialization. Canada contributes a smaller share, tied mainly to its own critical minerals strategy and interest in reducing battery supply chain dependence on cobalt and nickel imports.
Europe Dual Carbon Battery Market Insights
Europe's dual carbon battery market is still early-stage relative to Asia Pacific, but automotive electrification mandates across the EU are creating steady pull for chemistries that can support both fast charging and improved thermal safety. Automakers here have been more cautious about full-scale adoption than their Japanese counterparts, treating dual carbon technology mainly as a research and pilot-program interest for now.
Germany leads the European market with a 27.90% share, supported by its automotive manufacturing base and government-backed battery research initiatives. The United Kingdom and France follow, with growth in both countries tied to national EV supply chain strategies aimed at reducing reliance on imported battery materials.
Asia Pacific Dual Carbon Battery Market Insights
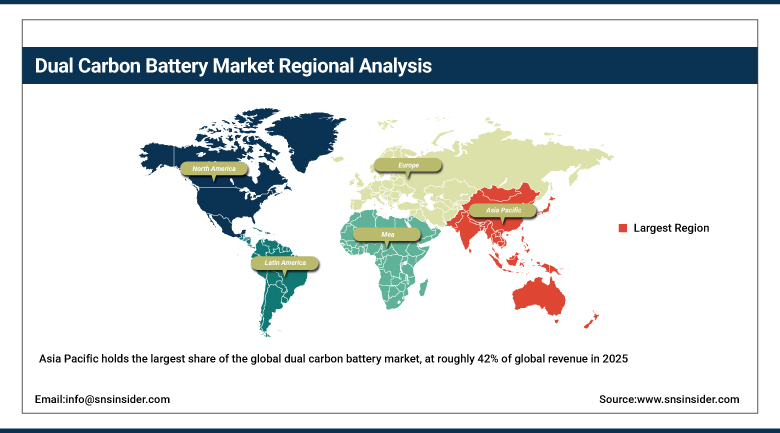
Asia Pacific holds the largest share of the global dual carbon battery market, at roughly 42% of global revenue in 2025, and that leadership traces directly back to where the underlying technology was developed, Japanese researchers and start-ups have been working on carbon-based electrode chemistries since the mid-2010s, giving the region a head start most competitors are still trying to close. National policies mandating minimum domestic battery content in EV packs across several Asia Pacific markets are reinforcing that lead further.
Japan holds roughly 34.60% of the regional market, anchored by early commercial dual carbon developers and a deep base of battery materials research tied to universities and established electronics manufacturers. China is growing quickly as its major battery producers begin integrating dual carbon fast-charge modules into existing lithium-ion EV packs, while South Korea contributes through its established battery manufacturing base.
Get Customized Report as per Your Business Requirement - Enquiry Now
Middle East & Africa and Latin America Dual Carbon Battery Market Insights
The Middle East & Africa region is growing off a small base, mostly through early-stage grid-storage pilot projects in the Gulf states rather than automotive applications. Latin America's interest is similarly nascent, concentrated in a handful of renewable energy storage pilots in markets with fast-growing solar and wind capacity.
The UAE leads the Middle East & Africa market with a 16.20% share, supported by grid-storage pilot programs tied to its renewable energy diversification goals. Brazil represents 24.30% of the Latin American market, reflecting early interest from its renewable energy sector, with Chile also exploring dual carbon storage pilots tied to its solar capacity expansion.
Market Dynamics
Growth Drivers: Cobalt-Free Supply Chains and Fast-Charging Demand Fueling Market Growth
Two pressures are pushing this market forward at once: automakers need a credible path away from cobalt and nickel dependence, and both EV buyers and grid operators want faster charging and better safety than conventional lithium-ion chemistry can offer. Dual carbon batteries answer both asks simultaneously, which is a big part of why adoption is accelerating faster than most niche battery chemistries manage in their first commercial decade.
Government incentive programs, from IRA credits in the U.S. to capital grants for pilot production lines in Asia, are lowering the capital barrier for new entrants and accelerating the timeline from lab demonstration to commercial-scale manufacturing.
Restraints: Manufacturing Scale-Up Costs and Energy Density Gaps Limiting Market Expansion
Most dual carbon manufacturers are still operating well below the production scale that would let them compete with lithium-ion on cost per kilowatt-hour, and building that scale requires capital that smaller start-ups often struggle to raise without government grant support. Energy density, while improving, still lags the best commercial lithium-ion cells in some formulations, which limits dual carbon adoption in applications where range or runtime per unit weight is the primary buying criterion.
Supply chain infrastructure for battery-grade carbon materials is also less mature than the established lithium-ion supply base, and manufacturers sourcing plant-derived carbon face their own agricultural and processing variability that conventional graphite suppliers do not.
Opportunities: Grid-Storage Adoption and Solid-State Development Creating New Growth Avenues
Grid-scale energy storage represents one of the clearest near-term opportunities, since utilities managing fire-suppression costs and safety compliance for large battery installations have a direct financial incentive to consider a chemistry with meaningfully lower thermal runaway risk. As renewable capacity additions keep climbing, that demand pull is likely to strengthen rather than fade.
Solid-state electrolyte development offers a second major opportunity, particularly for cold-climate applications where recent formulations have shown strong low-temperature performance. Manufacturers who can commercialize solid-state dual carbon cells at scale first stand to capture premium positioning in both EV and grid-storage segments before competitors catch up.
Recent Developments:
- 2025: Contemporary Amperex Technology Co. Limited (CATL) unveiled a dual-power EV battery pack combining dual carbon fast-charge modules with high-energy lithium-ion cells, delivering roughly 930 miles of range for luxury sedan applications.
- 2025: Asahi Kasei Corporation introduced a new electrolyte family that retains 90% ionic conductivity at -40 degrees Celsius and roughly doubles dual carbon cycle life at 60 degrees Celsius, with commercialization slated for late 2025.
- 2025: Japan's Ministry of Economy, Trade and Industry cleared a joint venture between Toyota Motor Corporation and Idemitsu Kosan Co., Ltd. to build a USD 142 million lithium-sulfide plant supplying precursor materials for dual carbon battery electrolytes, with production set to begin in 2027.
- 2025: PJP Eye Ltd. began commercialization of its Cambrian dual carbon battery, developed in partnership with Kyushu University, targeting personal mobility, energy storage, and data center backup applications.
Dual Carbon Battery Market key players are:
- PJP Eye Ltd.
- JSR Corporation
- Hitachi, Ltd.
- Asahi Kasei Corporation
- Nippon Chemi-Con Corporation
- Sanyo Electric Co., Ltd.
- Nissan Motor Co., Ltd.
- Contemporary Amperex Technology Co. Limited (CATL)
- BYD Company Limited
- LG Energy Solution Ltd.
- Panasonic Holdings Corporation
- Samsung SDI Co., Ltd.
- Johnson Controls International plc
- Tianjin Lishen Battery Joint-Stock Co., Ltd.
- Amprius Technologies, Inc.
- PolyPlus Battery Company
- Toyota Motor Corporation
- Idemitsu Kosan Co., Ltd.
- Murata Manufacturing Co., Ltd.
- Loxus Inc.
Dual Carbon Battery Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 3.98 Billion |
| Market Size by 2035 | USD 11.34 Billion |
| CAGR | CAGR of 11.03% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Battery Type (Rechargeable Dual Carbon Batteries, Primary Dual Carbon Batteries) • By Application (Electric Vehicles, Energy Storage Systems, Consumer Electronics, Portable Power, Others) • By Electrolyte Type (Liquid Electrolyte, Solid Electrolyte, Gel Electrolyte) • By Cell Configuration (Pouch Cells, Cylindrical Cells, Prismatic Cells) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | PJP Eye Ltd., JSR Corporation, Hitachi, Ltd., Asahi Kasei Corporation, Nippon Chemi-Con Corporation, Sanyo Electric Co., Ltd., Nissan Motor Co., Ltd., Contemporary Amperex Technology Co. Limited (CATL), BYD Company Limited, LG Energy Solution Ltd., Panasonic Holdings Corporation, Samsung SDI Co., Ltd., Johnson Controls International plc, Tianjin Lishen Battery Joint-Stock Co., Ltd., Amprius Technologies, Inc., PolyPlus Battery Company, Toyota Motor Corporation, Idemitsu Kosan Co., Ltd., Murata Manufacturing Co., Ltd., Loxus Inc. |
Frequently Asked Questions
Key players include PJP Eye Ltd., JSR Corporation, Hitachi, Ltd., Contemporary Amperex Technology Co. Limited (CATL), and BYD Company Limited, among others.
Key opportunities include grid-scale energy storage adoption driven by lower fire-suppression costs, solid-state electrolyte commercialization for improved cold-climate performance, and expanding automotive offtake agreements supported by cobalt-free supply chain incentives.
The market is driven by automaker demand for cobalt-free, fast-charging battery chemistries, rising grid-storage safety requirements, and government incentive programs supporting pilot-scale manufacturing.
The Rechargeable Dual Carbon Batteries segment dominated the Dual Carbon Battery Market in 2025.
The Asia Pacific region dominated the Dual Carbon Battery Market in 2025, accounting for approximately 42% of global market share.
