
Flame Detector Market Report Scope & Overview:
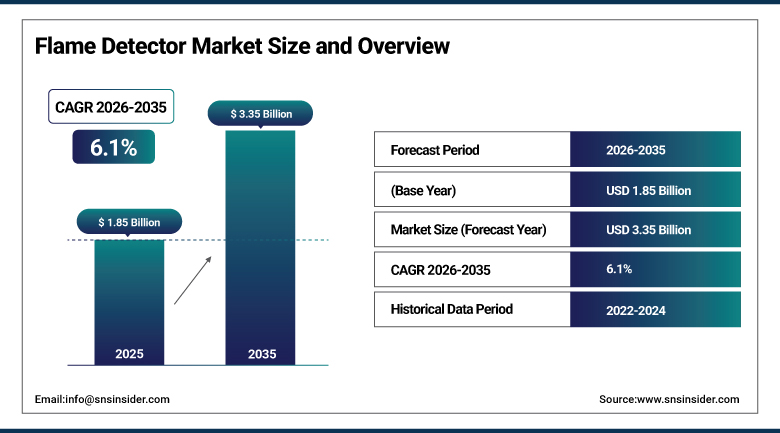
The Flame Detector Market was valued at USD 1.85 Billion in 2025 and is expected to reach USD 3.35 Billion by 2035, growing at a CAGR of 6.1% from 2026–2035.
The Flame Detector Market is steadily witnessing growth, due to growing concerns related to workplace safety, fire prevention, and hazard detection at hazardous industrial sites. Increasing investments in the oil and gas industry, manufacturing industries, power generation industries, mining, and transport sector have led to the rise in demand for advanced flames detection systems. Development in the field of technology like ultraviolet (UV) flames detectors, infrared (IR) flames detectors, and multichannel spectrum flames detectors have increased the efficiency of these detectors. Wireless and intelligent solutions have also been helping in propelling the growth of the market through remote monitoring and control of hazards.
Teledyne Gas and Flame Detection introduced its Spyglass Xtend triple-infrared flame detector in 2025, engineered to detect hydrogen and hydrocarbon fires simultaneously rather than requiring separate sensors for each. The launch addresses a real gap in the market: hydrogen flames are nearly invisible to the naked eye and burn at wavelengths conventional hydrocarbon-focused detectors can miss entirely, a blind spot that matters more every year as green-hydrogen production facilities and battery energy storage systems multiply across the industrial landscape.
To Get more information Flame Detector Market - Request Free Sample Report
Flame Detector Market Trends
-
New installations are shifting toward lithium-ion battery warehouses, data centers, and green-hydrogen electrolyser plants, environments where hydrogen flames create sensing challenges conventional hydrocarbon-focused detectors weren't originally designed to handle.
-
Multi-spectrum infrared detectors continue gaining share as they analyze several wavelength bands simultaneously, cutting false-alarm rates in sunny or hot industrial environments and meeting tightening insurance and hazardous-area certification requirements.
-
Portable flame detection is growing as operators adopt test-before-touch safety procedures, letting inspection teams validate fixed-system integrity during turnarounds without halting production.
-
Wireless and IoT-enabled flame detectors are spreading as operators seek remote monitoring and easier retrofitting into facilities where running new cabling to a detector location is impractical or prohibitively expensive.
-
Integration of flame detectors with smart building and facility management systems continues expanding, enabling remote monitoring, real-time alerting, and faster incident response across increasingly connected industrial sites.
U.S. Flame Detector Market Outlook
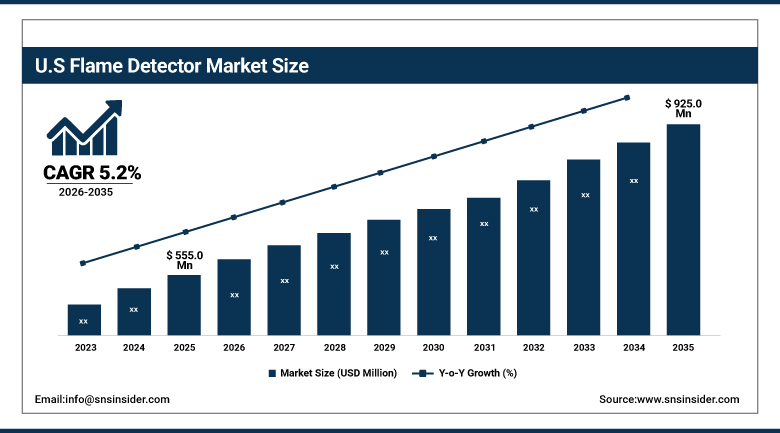
The U.S. Flame Detector Market was valued at approximately USD 555.0 Million in 2025 and is expected to reach approximately USD 925.0 Million by 2035, growing at a CAGR of approximately 5.2%.
Demand in the United States is anchored by a deep base of leading manufacturers, extensive oil and gas infrastructure, and a growing base of data center and battery storage installations that require flame detection technology many of these facilities didn't need a decade ago. Rising technological development and strong economic activity across construction, fire services, and industrial sectors continue supporting steady replacement and new installation demand. A concentration of major safety equipment manufacturers headquartered domestically gives U.S. buyers particularly deep access to the latest detection technology.
MSA Safety, a Pennsylvania-based fixed gas and flame detection supplier, introduced its FL5000 flame detector and acquired Autronica Fire and Security to broaden its integrated fire and gas safety portfolio across critical infrastructure, energy, marine, and industrial markets. The expansion reflects how much U.S.-headquartered safety equipment manufacturers are consolidating adjacent detection technologies, gas, flame, and fire, into single integrated platforms rather than selling them as separate product lines.
Flame Detector Market Segment Analysis
-
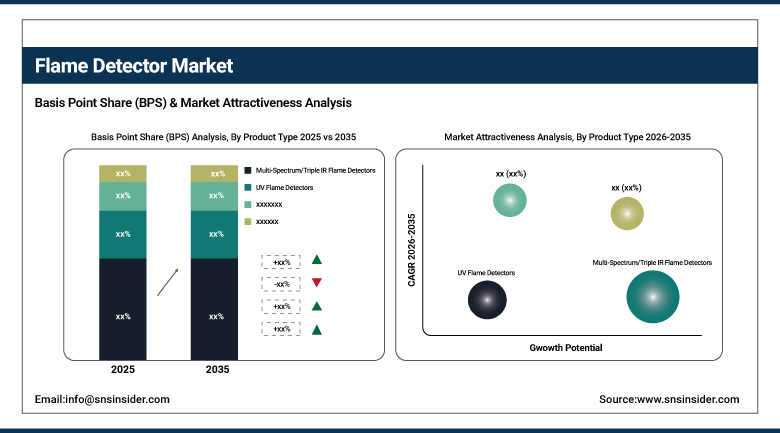
By Product Type, the Multi-Spectrum/Triple IR segment dominated the Flame Detector Market with approximately 38.0% share in 2025, and is also the fastest growing with a CAGR of approximately 7.8%.
-
By Mounting Type, the Fixed segment dominated the Flame Detector Market with approximately 82.0% share in 2025, while the Portable segment is the fastest growing with a CAGR of approximately 7.6%.
-
By Connectivity, the Wired segment dominated the Flame Detector Market with approximately 68.0% share in 2025, while the Wireless segment is the fastest growing with a CAGR of approximately 9.4%.
-
By Service Type, the Maintenance Services segment dominated the Flame Detector Market with approximately 34.0% share in 2025, while the Inspection & Managed Services segment is the fastest growing with a CAGR of approximately 8.6%.
-
By End-User Industry, the Oil & Gas segment dominated the Flame Detector Market with approximately 34.0% share in 2025, while the Power & Energy segment is the fastest growing with a CAGR of approximately 8.9%.
By Product Type, multi-spectrum/triple IR dominates and grows fastest
Multi-spectrum, triple-infrared detectors held the largest share of the product-type segment in 2025, owing to their superior false-alarm rejection rates relative to single-wavelength UV or IR sensors. Analyzing multiple wavelength bands simultaneously lets these detectors distinguish an actual fire from sunlight, hot machinery, or welding arcs far more reliably than older single-spectrum technology.
Multi-spectrum detectors are also the fastest-growing product type, an unusual case where the already-dominant category continues gaining share rather than ceding ground to simpler alternatives. Tightening insurance requirements and hazardous-area certification standards are reinforcing this trend, as facility operators increasingly find that multi-spectrum technology's lower false-alarm rate pays for itself in reduced unplanned shutdowns alone.
By Mounting Type, fixed dominates, portable grows fastest
Fixed flame detectors accounted for the overwhelming majority of the mounting-type segment in 2025, permanently installed and wired into a facility's alarm, shutdown, and suppression systems to provide continuous, unattended monitoring. That always-on coverage remains essential for hazardous industrial environments where a fire needs to trigger an automated response within seconds.
Portable flame detectors are growing fastest as operators adopt test-before-touch safety procedures, using handheld units to validate fixed-system integrity during turnarounds without halting production, while first responders carry them to quickly assess unknown scenes. Battery density improvements have meaningfully extended portable device mission time while maintaining sensitivity comparable to fixed platforms, and rugged, intrinsically safe designs now enable safe use even in hazardous Zone-1 locations.
By Connectivity, wired dominates, wireless grows fastest
Wired flame detectors held the larger share of the connectivity segment in 2025, being the preferred option in facilities that have an existing wired system and require the security and dependability offered by wired connectivity. Safety-critical applications also prefer wired connectivity due to the reduced risk of any disruptions in the signal or any interruptions caused by battery issues.
Wireless flame detectors are experiencing the fastest growth since wireless detectors provide easier installation and remote monitoring, which is very important when installation of new cables would be difficult or too costly. The ability to install detectors remotely is becoming an increasingly useful characteristic in large industrial facilities.
By Service Type, maintenance dominates, inspection & managed services grows fastest
Maintenance services accounted for the largest service-type share in 2025, reflecting the ongoing calibration, testing, and upkeep that safety-critical flame detection equipment requires to remain compliant with regulatory standards and manufacturer specifications. Regular maintenance cycles represent a predictable, recurring revenue stream that keeps this the largest single service category.
Inspection and managed services are growing fastest as facility operators increasingly outsource ongoing compliance verification and system monitoring rather than managing these functions entirely in-house. That outsourcing trend is particularly pronounced among operators looking to reduce the specialized technical staffing burden that comprehensive in-house flame detection program management otherwise requires.
By End-User Industry, oil & gas dominates, power & energy grows fastest
Oil and gas accounted for the largest end-user share in 2025, reflecting the industry's sizable installed base of flame detectors across refineries, offshore platforms, and pipeline infrastructure where hydrocarbon fire risk has driven safety investment for decades. That deep, established installed base keeps oil and gas the anchor end-user industry by both unit count and replacement demand.
Power and energy is the fastest-growing end-user industry as green-hydrogen production facilities, battery energy storage systems, and data centers all drive new flame detection demand that barely existed as a meaningful category a decade ago. These newer applications often require detection technology specifically capable of identifying hydrogen flames, a genuinely different technical challenge than the hydrocarbon fire detection that has traditionally defined the industry.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
North America |
United States |
81.0% |
|
Europe |
Germany |
23.0% |
|
Asia Pacific |
China |
39.0% |
|
Latin America |
Brazil |
36.0% |
|
Middle East & Africa |
Saudi Arabia |
42.0% |
North America Flame Detector Market Insights
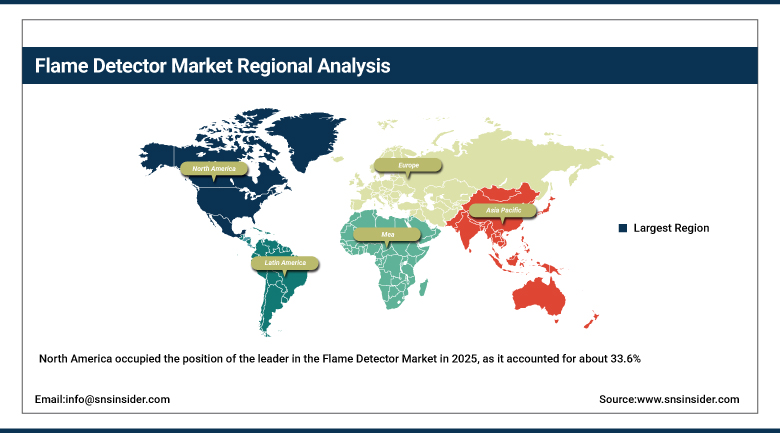
North America occupied the position of the leader in the Flame Detector Market in 2025, as it accounted for about 33.6% of the global market size. This position is supported by the presence of leading flame detector manufacturers in the U.S., its significant oil & gas industry, as well as increasing numbers of data centers and battery storage facilities.
The Canadian market makes a significant contribution to the regional market performance, due to its oil & gas and industrial sector. Meanwhile, in Mexico, the market expands along with the increasing number of investments in its manufacturing and energy infrastructure. Many supplies within the North American market are interlinked, as manufacturers usually serve all three markets via joint distribution channels.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Flame Detector Market Insights
Europe is a mature, regulation-driven flame detector market influenced by stringent industrial safety regulations and ATEX hazardous area certifications. The country leading regional demand is Germany, which is home to a significant number of industrial manufacturing plants, in addition to being the domicile of some leading companies of flame detectors and gas detection equipment.
Also contributing to the demand in significant numbers are the UK, France, and the Netherlands, with their oil and gas, chemicals, and industrial segments. European industrial safety regulations play a direct role in the specification of the equipment as compared to other regions of the world.
Asia Pacific Flame Detector Market Insights
The Asia-Pacific is an important region in the flame detector industry, where China stands out through robust demand due to increased spending on industrial safety and infrastructure development in the manufacturing and energy industries in the nation. The continued focus on the regulation of industrial fire safety will only enhance the already high levels of demand growth.
While India will continue to attract investments due to rapid industrial and energy infrastructure developments, both Japan and South Korea are established markets in the industry driven by industrial safety regulations. The markets in Southeast Asia will be following suit in terms of growth driven by industrialization.
Middle East & Africa Flame Detector Market Insights
The Middle East and Africa are expected to register the fastest regional growth through 2035, driven substantially by roughly USD 200 billion in LNG mega-train investments across the region that require advanced flame monitoring throughout their processing and export infrastructure. Saudi Arabia anchors this growth, supported by substantial industrial and energy infrastructure investment tied to the country's broader economic diversification strategy.
The UAE and Qatar contribute meaningful demand as well, each expanding petrochemical and LNG infrastructure that requires comprehensive flame detection coverage. South Africa anchors demand across the rest of the continent, supported by a more established industrial and mining base than most of its neighbors.
Market Dynamics
Growth Drivers: Stringent safety regulations and industrial infrastructure expansion fueling adoption
Stringent government and industry safety regulations are one of the clearest forces behind rising flame detector demand, as hazardous industrial environments across oil and gas, chemicals, and manufacturing face increasingly rigorous fire detection and response requirements. That regulatory pressure gives flame detector demand a dependable baseline independent of broader economic cycles.
Continued industrial infrastructure expansion adds a second major driver, as growing manufacturing, energy, and processing capacity worldwide creates sustained new installation demand alongside the steady replacement demand from an already sizable global installed base. Rising industrialization in emerging markets is reinforcing this demand base as new facilities come online requiring comprehensive fire safety coverage from the outset.
Restraints: High equipment costs and false-alarm sensitivity limiting broader adoption
The upfront cost of advanced multi-spectrum flame detection equipment remains a real barrier for smaller facilities and operators in price-sensitive emerging markets, where simpler, lower-cost single-spectrum detectors often win out despite their higher false-alarm rates. That cost sensitivity can slow adoption of premium technology even among facilities that would benefit from reduced false-alarm downtime.
False-alarm sensitivity in challenging environments, sunny outdoor installations, hot machinery, or welding operations, remains a genuine restraint for older single-spectrum technology, since repeated false alarms erode operator confidence and can lead facilities to disable or ignore detection systems altogether. That risk is a key reason multi-spectrum technology continues gaining share despite its higher upfront cost.
Opportunities: Hydrogen economy expansion and smart building integration opening new growth avenues
The expanding global hydrogen economy offers manufacturers a genuinely significant opportunity, as green-hydrogen production facilities and hydrogen-powered equipment require flame detection technology specifically capable of identifying hydrogen fires, a technical challenge conventional hydrocarbon-focused detectors weren't originally designed to solve. Manufacturers that build genuine hydrogen detection expertise are positioned to capture disproportionate growth as global hydrogen infrastructure investment continues accelerating.
Integration with smart building and facility management systems represents a second significant opportunity, letting manufacturers offer flame detectors as part of broader connected safety ecosystems rather than standalone devices. Companies that build genuine IoT and smart building integration capability are positioned to capture premium pricing from facility operators seeking unified, remotely monitored safety infrastructure.
Recent Developments:
-
2025: Honeywell launched its Hydrogen Leak Detector sensor, using thermal conductivity detection technology capable of identifying hydrogen leaks as small as 50 parts per million in industrial equipment and hydrogen-powered vehicles.
-
October 2025: Teledyne Gas and Flame Detection showcased its MultiFlame DF-TV7-T multi-spectrum infrared flame detector, featuring three wavelengths and integrated high-definition video for remote decision-making, at ADIPEC 2025 in Abu Dhabi.
-
December 2025: Honeywell entered a multi-year partnership with Hornets Sports & Entertainment to deploy AI-powered building management and XLS4000 smart fire detection systems across Charlotte's Spectrum Center and the Novant Health Performance Center.
-
2025: Industry-wide adoption of IoT-enabled fire safety devices in industrial settings rose by roughly 40% between 2021 and 2023, according to the European Commission's Joint Research Centre, reflecting accelerating integration of flame detectors with smart building management systems.
Flame Detector Market Key Players
-
Honeywell International Inc.
-
Emerson Electric Co.
-
Johnson Controls International plc
-
MSA Safety Incorporated
-
Siemens AG
-
Drägerwerk AG & Co. KGaA
-
Teledyne Technologies Incorporated
-
Robert Bosch GmbH
-
Halma plc
-
Hochiki Corporation
-
Crowcon Detection Instruments Ltd.
-
Fike Corporation
-
Minimax Viking GmbH
-
REZONTECH Co., Ltd.
-
Micropack Engineering Ltd.
-
Nohmi Bosai Ltd.
-
Riken Keiki Co., Ltd.
-
Firefly AB
-
Sense-WARE Fire and Gas Detection B.V.
-
Apollo Fire Detectors Ltd.
Flame Detector Market Report Scope:
| Market Size in 2025Report Attributes | Details |
|---|---|
| USD 1.85 Billion | |
| Market Size by 2035 | USD 3.35 Billion |
| CAGR | CAGR of 6.1% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (UV Flame Detectors, IR Flame Detectors, Multi-Spectrum/Triple IR Flame Detectors, Others) • By Mounting Type (Fixed, Portable) • By Connectivity (Wired, Wireless) • By Service Type (Engineering Services, Installation & Design Services, Maintenance Services, Inspection & Managed Services) • By End-User Industry (Oil & Gas, Manufacturing & Process Industries, Power & Energy, Mining, Transportation & Logistics, Aerospace & Defense, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Honeywell International Inc., Emerson Electric Co., Johnson Controls International plc, MSA Safety Incorporated, Siemens AG, Drägerwerk AG & Co. KGaA, Teledyne Technologies Incorporated, Robert Bosch GmbH, Halma plc, Hochiki Corporation, Crowcon Detection Instruments Ltd., Fike Corporation, Minimax Viking GmbH, REZONTECH Co., Ltd., Micropack Engineering Ltd., Nohmi Bosai Ltd., Riken Keiki Co., Ltd., Firefly AB, Sense-WARE Fire and Gas Detection B.V., Apollo Fire Detectors Ltd. |
Frequently Asked Questions
Key players include Honeywell International Inc., Emerson Electric Co., Johnson Controls International plc, MSA Safety Incorporated, and Siemens AG, among others.
Key opportunities include hydrogen flame detection, multi-spectrum sensing, wireless connectivity, smart buildings, data centers, industrial safety, and expanding power and energy applications.
Stringent government and industry safety regulations combined with continued industrial infrastructure expansion, particularly in hydrogen and battery storage applications.
Oil & Gas dominated with approximately 34.0% share in 2025, while Power & Energy is the fastest growing segment with a CAGR of approximately 8.9%.
North America dominated the Flame Detector Market in 2025, while Middle East & Africa is the fastest-growing region.
