
Flexible Paper Packaging Market Report Scope & Overview:
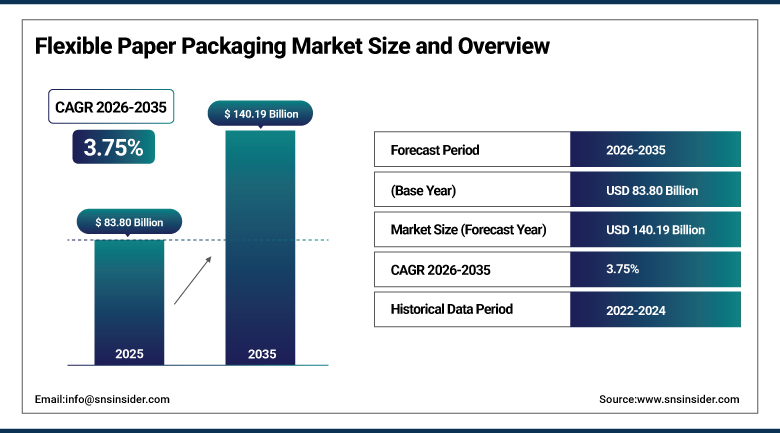
The Flexible Paper Packaging Market was valued at USD 83.80 Billion in 2025 and is expected to reach USD 140.19 Billion by 2035, growing at a CAGR of 3.75% from 2026 to 2035.
The Flexible Paper Packaging Market exists at the intersection of two forces most packaging categories only feel one of, genuine consumer and regulatory pressure to move away from plastic, and a manufacturing base mature enough to make paper-based flexible formats actually competitive on cost and performance rather than a compromise. Any box or component of a package that can readily transform shape when loaded or utilized qualifies as flexible packaging, and paper-based bags, pouches, liners, and wraps increasingly deliver the marketing advantages and sustainability benefits brands want without sacrificing the barrier performance that used to make plastic the default choice. The COVID-19 pandemic reinforced the importance of hygienic packaging, leading to increased use of flexible paper materials in food and healthcare sectors, a shift that has largely persisted well past the acute crisis that first drove it.
In January 2025, Sonoco Products Company launched its first Global Capability Centre, the Sonoco Performance Hub, in Hyderabad, India, representing a USD 10 million initial-phase investment in packaging design and engineering services.
To Get more information Flexible Paper Packaging Market - Request Free Sample Report
Flexible Paper Packaging Market Trends
-
Digital printing adoption continues surging, enabling brand personalization and visually appealing packaging at smaller production runs.
-
E-commerce packaging demand is expanding fastest as paper-based mailers and protective wraps replace plastic alternatives.
-
Coated paper formulations offering enhanced barrier performance are gaining share in food and pharmaceutical applications.
-
Compostable and biodegradable paper packaging solutions continue attracting growing consumer demand across major markets.
-
Brand owners are increasingly specifying paper-based pouches for personal care and food products previously packaged exclusively in plastic.
U.S. Flexible Paper Packaging Market Outlook
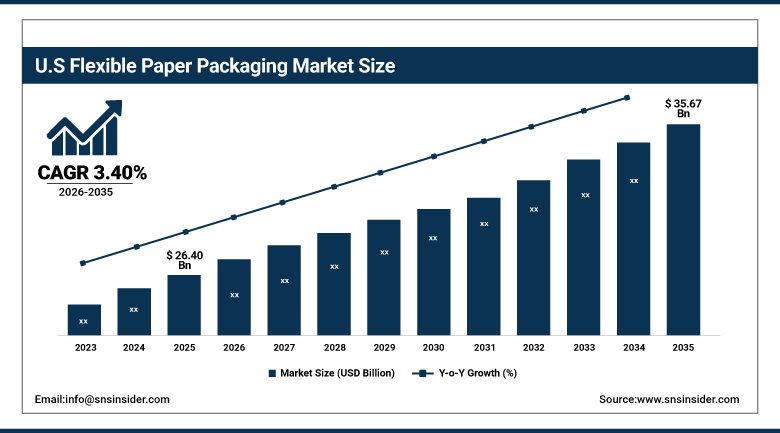
The U.S. Flexible Paper Packaging Market was valued at USD 26.40 Billion in 2025 and is projected to reach USD 35.67 Billion by 2035, growing at a CAGR of 3.40% during 2026-2035.
There is a variety of different sustainable paper-based packaging available in the domestic market due to a growing awareness of sustainability and higher demands for environmentally friendly packaging solutions. Digital printing became extremely popular and adopted domestically because it provides the means of branding and personalized design, which are difficult to achieve through traditional flexographic printing methods. Hygiene issues highlighted during the outbreak of the coronavirus became one of the key factors behind the popularity of flexible paper-based packaging in the fields of food and health care, an aspect that still remains relevant in making purchase decisions nowadays. E-commerce operations are constantly changing packaging requirements by making manufacturers prefer paper-based packaging over plastic alternatives.
In 2025, Frugalpac Ltd. continued its cooperation with ITC Limited to increase the use of its paper-based bottle technology in beverage packaging and thus reduce the amount of plastics used.
Flexible Paper Packaging Market Segment Analysis
-
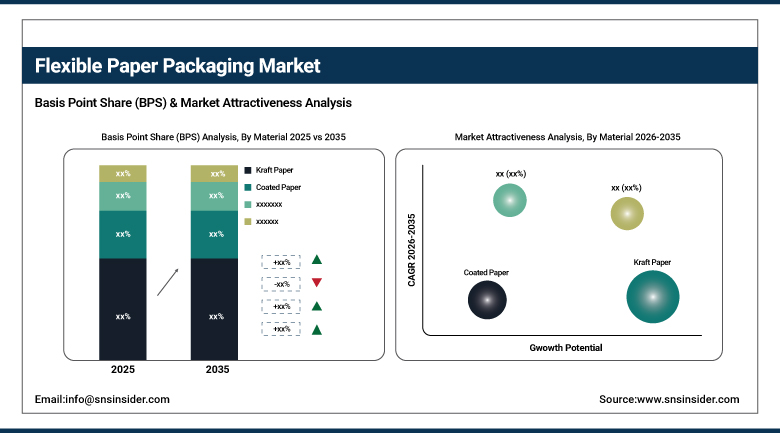
By Material, kraft paper dominates the Flexible Paper Packaging Market while coated paper grows fastest, with kraft paper holding 42% share in 2025 and coated paper registering a CAGR of 6.20% from 2026 to 2035.
-
By Packaging Type, bags dominates the Flexible Paper Packaging Market while pouches grows fastest, with bags holding 38% share in 2025 and pouches registering a CAGR of 6.80% from 2026 to 2035.
-
By Printing Technology, flexography dominates the Flexible Paper Packaging Market while digital printing grows fastest, with flexography holding 46% share in 2025 and digital printing registering a CAGR of 7.40% from 2026 to 2035.
-
By End-Use, food & beverage dominates the Flexible Paper Packaging Market while e-commerce grows fastest, with food & beverage holding 44% share in 2025 and e-commerce registering a CAGR of 8.20% from 2026 to 2035.
By Material, Kraft Paper Dominates the Flexible Paper Packaging Market While Coated Paper Grows Fastest
Kraft Paper holds 42% of the Flexible Paper Packaging Market, the largest single category, benefiting from its combination of strength, cost efficiency, and broad compatibility with the wide range of bag, pouch, and wrap formats that flexible paper packaging encompasses. Established kraft paper manufacturing infrastructure across the industry keeps this material the most economical choice for high-volume flexible packaging applications.
Coated Paper is growing at a 6.20% CAGR, the fastest pace among materials, as manufacturers increasingly apply functional coatings that deliver moisture, grease, and oxygen barrier performance previously achievable only with plastic films or laminates. Growing brand demand for paper packaging that performs in food and pharmaceutical applications without sacrificing barrier protection continues reinforcing coated paper's above-average growth.
By Packaging Type, Bags Dominates the Flexible Paper Packaging Market While Pouches Grows Fastest
Paper bags represent 38% of the packaging type market share and are the largest single category, continuing to be the most established flexible paper format, where ease of containment is more important than complex barriers. The high level of recognition among consumers and retailers of paper bags is continually helping to maintain its dominant position in the category.
Paper pouches are the highest growing packaging type at 6.80% CAGR, as brands are turning to paper-based pouches for food products, personal care products, and home care products which were once available only in plastic pouches, thanks to its superior performance characteristics and sustainable image. Consumer and retailer preference of paper pouches over plastic ones is continually boosting its growth rate.
By Printing Technology, Flexography Dominates the Flexible Paper Packaging Market While Digital Printing Grows Fastest
Flexography holds 46% of the market by printing technology, the largest single category, remaining the standard choice for high-volume flexible paper packaging production thanks to its cost efficiency and compatibility with the long print runs most packaged goods manufacturers still require. Established flexographic press infrastructure across the converting industry keeps this technology the default choice for large-scale production.
Digital Printing is growing fastest, at a 7.40% CAGR, as the adoption of digital printing technologies has surged, enabling brand personalization and visually appealing packaging that shorter production runs and increasingly customized packaging demand require. Growing brand interest in limited editions, regional variants, and personalized packaging continues reinforcing digital printing's above-average growth.
By End-Use, Food & Beverage Dominates the Flexible Paper Packaging Market While E-commerce Grows Fastest
The Food & Beverage segment constitutes 44% of end-use demand, which is the largest category in terms of market share, considering the huge number of food and beverages that are packaged and sold throughout the globe. The significance of hygiene in packaging during the recent pandemic also supports continued growth in demand within this category.
E-commerce is the fastest growing end-use application segment, with a compound annual growth rate (CAGR) of 8.20%. This application category shows high revenue growth owing to the popularity of paper packaging in direct mail packaging applications instead of plastic.
Regional Analysis
|
Region |
Country |
Share (2025) |
|
North America |
United States |
85.00% |
|
Asia Pacific |
China |
36.40% |
|
Europe |
Germany |
25.60% |
|
Middle East & Africa |
UAE |
17.20% |
|
Latin America |
Brazil |
26.50% |
North America Flexible Paper Packaging Market Insights
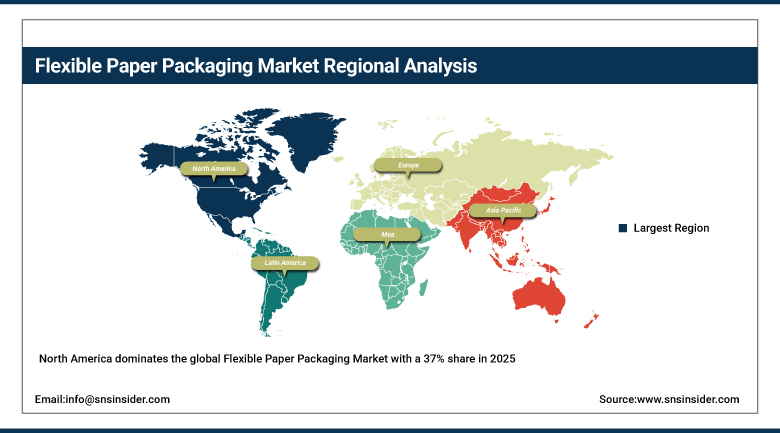
North America dominates the global Flexible Paper Packaging Market with a 37% share in 2025, encompassing a diverse range of sustainable paper-based packaging solutions driven by heightened emphasis on sustainability and growing demand for eco-friendly packaging materials. Growth here comes mostly from digital printing adoption and e-commerce packaging expansion rather than first-time category adoption, since flexible paper packaging has been standard practice across the region for decades.
The United States accounts for approximately 85.00% of the North American market, reflecting its large consumer goods manufacturing base and advanced packaging converting infrastructure. Canada contributes a smaller but steady share, tied to its own packaging waste regulations and comparable sustainability-driven consumer trends.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Flexible Paper Packaging Market Insights
Europe's flexible paper packaging market is mature and steady, shaped by strong regulatory pressure for eco-friendly solutions and comprehensive packaging waste regulation that has pushed brands toward paper-based alternatives well ahead of most other regions. Strong consumer preference for sustainable packaging options continues reinforcing steady demand even as growth in absolute terms remains more measured than in Asia Pacific.
Germany leads the European market with a 25.60% share, supported by its large consumer goods manufacturing base and strict sustainability compliance standards. France and the United Kingdom follow, with demand in both countries tied to comprehensive packaging waste regulation and growing e-commerce packaging adoption.
Asia Pacific Flexible Paper Packaging Market Insights
The Asia Pacific region is the fastest-growing region in the market, owing to the rising consciousness and concerns of consumers and governments about the need for environmental sustainability and development in the e-commerce industry of China and India. The e-commerce efforts made by China alone are helping to boost online retail sales by 12.4 percent year over year to about USD 810 billion in the first five months of 2025.
China is one of the largest regional markets, representing approximately 36.40 percent share of the regional market, owing to the rapid development in e-commerce and the rise in the manufacture of consumer goods.
Middle East & Africa and Latin America Flexible Paper Packaging Market Insights
The Middle East & Africa region is developing continuously owing to the development of retail infrastructure and e-commerce facilities in the Gulf countries, aided by increasing disposable income levels and increasing consumer awareness about eco-friendly packaging. Growth of Latin America is following a parallel trend fueled by the rapid expansion of consumer goods manufacturing industry in Brazil and growth of e-commerce in the region.
UAE is leading the Middle East & Africa market with a market share of 17.20%, aided by its position as the e-commerce and retail distribution hub of the region. Brazil accounts for 26.50% of the Latin America market, owing to the presence of a well-established consumer goods manufacturing industry, followed by Mexico through its growing e-commerce and packaged products industry.
Market Dynamics
Growth Drivers: Sustainability Demand and E-Commerce Expansion Fueling Market Growth
The rising trend of the demand for environmentally friendly packaging that has low impact on the environment is the most prominent factor fueling this market, where companies have started responding to the regulations as well as consumer preferences toward environmentally friendly packaging that substitutes plastic with paper. The rise of e-commerce within large economies is further driving the demand for such products, as more brands have switched from plastic to paper-based packaging. Another notable demand driver that is fueling this market is related to the implementation of digital printing technology that allows for the creation of personalized packaging.
Restraints: Barrier Performance Limitations and Cost Premiums Limiting Market Expansion
Paper-based flexible packaging still faces genuine barrier performance limitations compared to plastic alternatives in certain demanding applications, particularly where moisture or oxygen exposure would compromise product quality over extended shelf life. Coated and functional paper formulations that close this performance gap often carry a cost premium over both standard paper and conventional plastic packaging, creating a genuine adoption barrier for cost-sensitive product categories.
Raw material cost volatility for pulp and paper, tied to broader forestry commodity markets, can make it difficult for packaging manufacturers to hold pricing steady with brand customers on long-term supply contracts.
Opportunities: Barrier Coating Innovation and E-Commerce Packaging Design Creating New Growth Avenues
Innovations in barrier coatings present an important opportunity for growth, especially as companies capable of providing real moisture, grease, and oxygen barrier capabilities on a paper surface will be able to attract customers away from plastics in both food and pharmaceutical applications where paper was previously thought to be unsuitable. Further advancements in this technology are allowing for more applications of paper packaging.
A specialized design of paper packaging for e-commerce purposes represents another opportunity for development, especially as more direct-to-consumer brands are requiring special paper packaging designed specifically for shipment purposes.
Recent Developments:
-
2025: Amcor plc launched a recycle-ready frozen and fresh food packaging format in Latin America featuring a 38% reduced carbon footprint compared with prior multilayer structures.
-
2025: Huhtamaki Oyj launched compostable and recyclable packaging made from certified paperboard with a bio-based coating, keeping plastic content below 10%, for fresh and frozen food applications.
-
2025: Notpla Ltd. continued expanding commercial applications of its seaweed-derived packaging material as a biodegradable alternative to single-use plastic films and coatings.
-
January 2025: Pactiv Evergreen Inc. launched a new line of molded fiber packaging products, made from wood pulp and recycled paper, offering a compostable and recyclable alternative to traditional plastic packaging.
Flexible Paper Packaging Market key players are:
-
Smurfit Westrock plc
-
JK Paper Limited
-
Sappi Europe SA
-
Packaging Corporation of America
-
International Paper Company
-
Billerud AB
-
Nippon Paper Industries Co., Ltd.
-
Canadian Kraft Paper Industries Limited
-
Sealed Air Corporation
-
Coveris Holdings S.A.
-
Transcontinental Inc.
-
Amcor plc
-
Sonoco Products Company
-
Huhtamaki Oyj
-
Mondi Group
-
Stora Enso Oyj
-
Georgia-Pacific LLC
-
Graphic Packaging International, LLC
-
Oji Holdings Corporation
-
Constantia Flexibles Group GmbH
Flexible Paper Packaging Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 83.80 Billion |
| Market Size by 2035 | USD 140.19 Billion |
| CAGR | CAGR of 3.75% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Material (Kraft Paper, Coated Paper, Glassine Paper, Others) • By Packaging Type (Pouches, Bags, Wraps & Films, Others) • By Printing Technology (Flexography, Rotogravure, Digital Printing) • By End-Use (Food & Beverage, Pharmaceutical, Personal Care, E-commerce) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Smurfit Westrock plc, JK Paper Limited, Sappi Europe SA, Packaging Corporation of America, International Paper Company, Billerud AB, Nippon Paper Industries Co., Ltd., Canadian Kraft Paper Industries Limited, Sealed Air Corporation, Coveris Holdings S.A., Transcontinental Inc., Amcor plc, Sonoco Products Company, Huhtamaki Oyj, Mondi Group, Stora Enso Oyj, Georgia-Pacific LLC, Graphic Packaging International, LLC, Oji Holdings Corporation, Constantia Flexibles Group GmbH |
Frequently Asked Questions
Key players include Smurfit Westrock plc, International Paper Company, Amcor plc, Sonoco Products Company, Huhtamaki Oyj, Mondi Group, Stora Enso Oyj, and Packaging Corporation of America, alongside other established paper packaging manufacturers.
Key opportunities include barrier coating innovation extending paper packaging into demanding food and pharmaceutical applications, purpose-built e-commerce packaging design, and expanding brand adoption of paper-based pouches.
The market is driven by growing consumer demand for eco-friendly packaging materials, expansion of e-commerce, and adoption of digital printing technologies enabling brand personalization.
The Kraft Paper segment dominated the Flexible Paper Packaging Market in 2025.
The North America region dominated the Flexible Paper Packaging Market in 2025, accounting for approximately 37% of global market share.
