
Paper Straw Market Report Scope & Overview:
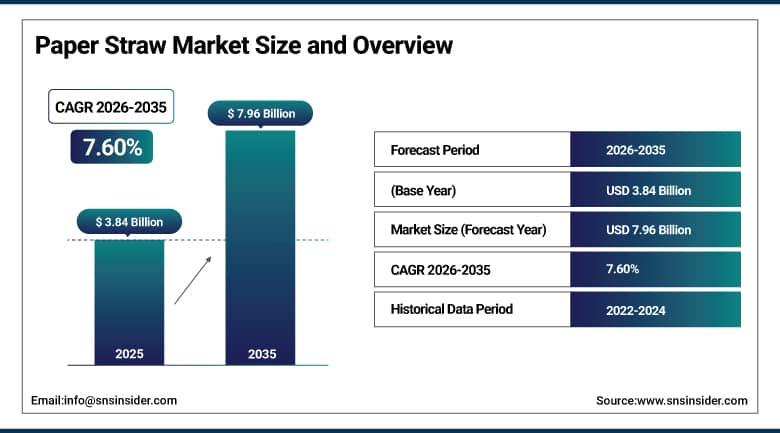
The Paper Straw Market was valued at USD 3.84 Billion in 2025 and is expected to reach USD 7.96 Billion by 2035, growing at a CAGR of 7.60% from 2026-2035.
The Paper Straw Market covers paper-based drinking straws manufactured from virgin kraft paper and recycled paper stock, sold across foodservice, institutional, and household channels as a direct substitute for single-use plastic straws. Growth is being driven by an expanding wave of plastic straw bans and extended producer responsibility regulations across North America, Europe, and parts of Asia, which have pushed quick-service restaurants, cafes, and beverage retailers to standardize on paper alternatives. Manufacturers are investing heavily in wet-strength coatings and multi-ply paper construction to close the durability gap that historically made paper straws prone to sogginess in extended-use beverage occasions, while also expanding printing and branding capabilities to help foodservice customers preserve on-pack marketing real estate. Direct supply contracts between large restaurant chains and manufacturers now account for the largest share of market revenue, reflecting buyer preference for volume and quality assurance over spot purchasing.
In July 2023, Huhtamaki Oyj announced a USD 30 million investment to expand its Paris, Texas manufacturing facility, increasing North American foodservice packaging capacity with production ramping up in the first quarter of 2025 to support growing demand from restaurant chains across the Southern and Midwestern United States. The investment reflects a broader pattern among established paper packaging majors of prioritizing regional capacity expansion over new market entry, allowing them to shorten delivery lead times and better compete against lower-cost Asian imports on service reliability rather than price alone, a strategy that is becoming increasingly important as foodservice buyers demand shorter, more resilient supply chains.
To Get More Information On Paper Straw Market - Request Free Sample Report
Paper Straw Market Trends:
-
Growing adoption of multi-ply wet-strength paper straws designed to close the durability gap with plastic alternatives.
-
Rising preference for direct, long-term supply contracts between large restaurant chains and paper straw manufacturers.
-
Expansion of printed and branded paper straws as foodservice operators preserve on-pack marketing opportunities.
-
Increasing use of recycled paper stock as brands pursue circular-economy sourcing commitments.
-
Accelerating regional manufacturing investment to shorten lead times and reduce reliance on Asian import supply chains.
U.S. Paper Straw Market Outlook:
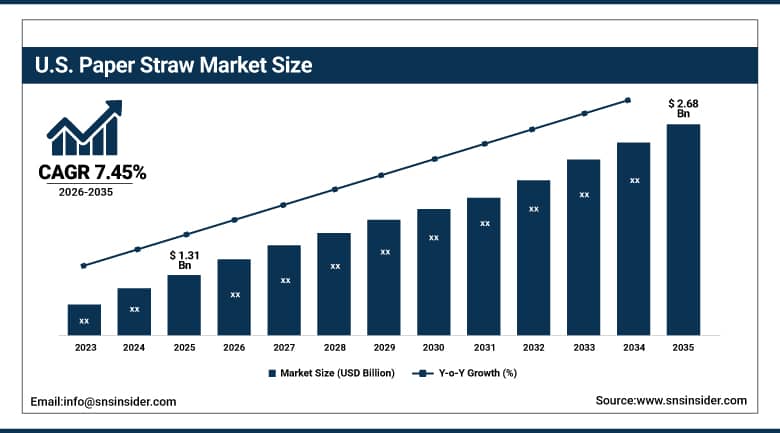
The U.S. Paper Straw Market was valued at USD 1.31 Billion in 2025 and is expected to reach USD 2.68 Billion by 2035, growing at a CAGR of 7.45% from 2026-2035.
The US represents the biggest single national paper straw market based on numerous state and city bans on single-use plastic straws, sustainability pledges by quick-service restaurants, and domestic production infrastructure represented by such companies as Aardvark Straws and Hoffmaster Group. Supply deals between producers and nationwide chains of restaurants and coffee shops prevail in procurement practices, where the priority is high-quality products, custom-branded paper straws, and guaranteed supply quantity rather than low cost. Capacity investments within the US have been rapidly growing due to the desire of companies to rely less on foreign paper straws, especially after the experience of disrupted supply chains highlighted the risks of international procurement of this product.
In June 2024, Aardvark Straws secured expanded supply agreements with hospitality and food service distributors, strengthening its commercial distribution network across North America and reinforcing its position as the leading domestically manufactured paper straw brand. The expansion reflects how domestic manufacturers are using distribution partnerships, rather than price competition alone, to defend market share against lower-cost import supply, particularly for foodservice customers who prioritize consistent quality and shorter, more reliable delivery timelines over marginal unit cost savings on a low-cost-per-unit product where service reliability carries disproportionate weight in the purchasing decision.
Paper Straw Market Segment Analysis:
-
By Type, the Flexible segment dominated the Paper Straw Market with approximately 54.30% share in 2025, while the Non-Flexible segment is the fastest growing with a CAGR of approximately 9.15%.
-
By Material, the Virgin Kraft Paper segment dominated the Paper Straw Market with approximately 61.75% share in 2025, while the Recycled Paper segment is the fastest growing with a CAGR of approximately 10.40%.
-
By End-Use, the Food Service segment dominated the Paper Straw Market with approximately 58.90% share in 2025, while the Household segment is the fastest growing with a CAGR of approximately 9.60%.
By Type, Flexible dominates, and Non-Flexible grows fastest
Flexible paper straws with accordion-type joint were the leading category among paper straws in 2025 since they emulate plastic straws most closely in terms of convenience, making them the best option for beverage vendors targeting customers ordering drinks via drive-thru and dine-in windows with a demand for a bendable straw for cups with domed tops and covers. Flexible paper straws have been the primary focus of manufacturers developing new products since there is less functional difference for the consumer in opting for a paper product over plastic.
Non-flexible paper straws are expected to have the highest CAGR due to novel design features being developed by manufacturers, which enhance the rigidity of paper straws and make them better for drinking thick beverages like smoothies or bubble tea without the need for a joint. The customers that order such drinks in the comfort of their offices or at home are more accepting of the non-flexible format, thus driving the higher-than-average growth in this category.
By Material, Virgin Kraft Paper dominates, and Recycled Paper grows fastest
Virgin kraft paper held the largest material share in 2025 because it offers superior fiber strength and moisture resistance compared with recycled stock, properties that are critical to preventing the sogginess and structural failure that damaged early paper straw products' reputation with consumers. Foodservice buyers have prioritized virgin kraft paper specifications to avoid negative customer experiences that could undermine broader sustainability messaging around the switch away from plastic straws.
Recycled paper straws are the fastest-growing material segment as brand owners pursue circular-economy sourcing commitments and improved wet-strength coating technology narrows the historical performance gap with virgin fiber. Advances in multi-ply lamination techniques now allow recycled paper straws to achieve durability closer to virgin kraft alternatives, making them increasingly viable for foodservice use rather than being confined to lower-performance household and institutional applications where structural demands are less severe.
By End-Use, Food Service dominates, and Household grows fastest
Food service commanded the biggest end-use share in 2025, owing to the high volumes that are produced in quick-service restaurants, cafes, and beverage retailers, who need to adhere to laws restricting the use of plastic straws in a majority of their operation footprint. End-user share is dominated by direct supply agreements from the manufacturers to the big restaurant chains, as the quality, brand customization, and stability of delivery take precedence over spot buying.
The household end-user market will grow rapidly because of the increasing availability of multipack paper straws in retail stores as consumers adopt sustainable behavior, which is adjacent to reusability, after years of being exposed to paper straws in foodservice establishments. The growing availability, coupled with slightly declining prices due to better economies of scale in production, will drive mainstream grocery buyers to use paper straws instead of plastic straws in beverages.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
77.85 |
|
Europe |
United Kingdom |
28.40 |
|
Asia Pacific |
China |
36.55 |
|
Middle East & Africa |
United Arab Emirates |
41.20 |
|
Latin America |
Brazil |
48.65 |
North America Paper Straw Market Insights
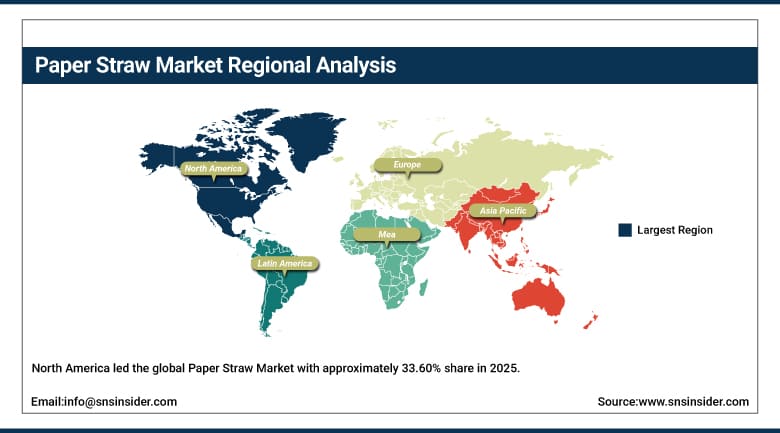
North America led the global Paper Straw Market with approximately 33.60% share in 2025, driven by widespread state and municipal single-use plastic straw restrictions and strong corporate sustainability commitments from major quick-service restaurant and coffee chains headquartered in the region. The United States accounted for the overwhelming majority of regional demand, supported by a well-established domestic manufacturing base including Aardvark Straws and Hoffmaster Group, both of which have invested in expanded production capacity to serve growing foodservice demand.
Canada contributes meaningful additional regional demand following its federal single-use plastics ban, which has pushed national restaurant and retail chains toward standardized paper straw specifications across their store networks. Continued expansion of domestic manufacturing capacity, aimed at reducing reliance on longer-lead-time Asian imports, is expected to reinforce North America's position as the largest regional market through the near term of the forecast period, even as growth rates in the region moderate relative to faster-growing emerging markets.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Paper Straw Market Insights
The Asia Pacific region has become the fastest-growing region for the Paper Straw Market, set to grow at a CAGR of around 10.85% during the forecast period of 2026-2035 on account of fast-paced growth in the beverage retail stores and quick-service restaurants chains in countries such as China, India, and Southeast Asia along with rising regulations against the use of single-use plastics in several economies. China has turned out to be not only the largest consuming market but also the leading exporter and manufacturer of paper straws because of its relatively cheaper pulp and paper sources.
There is huge demand coming from the rising bubble tea and quick service beverages culture along with the ban on single-use plastics in India, while in the Southeast Asia region, including Vietnam and Thailand, there is rising production of paper straws locally for reducing dependency on imports. Rising consumption of beverages by the urban middle-class population and increasing regulatory environment in several countries in the region is likely to drive Asia Pacific's above average growth rates during the forecast period.
Europe Paper Straw Market Insights
Europe represents a mature paper straw market, underpinned by the European Union's Single-Use Plastics Directive, which has effectively banned plastic straws across member states since 2021 and established paper straws as the default replacement across the foodservice and beverage retail sectors. The United Kingdom leads regional demand, supported by strong retailer and restaurant chain commitments to eliminate plastic packaging alongside a well-developed paper and pulp manufacturing base.
Germany and France contribute significant additional regional demand through their own extended producer responsibility frameworks and strong consumer expectations around packaging sustainability, while Nordic countries maintain high adoption rates tied to broader environmental policy leadership. Continued regulatory reinforcement under the EU's evolving packaging and packaging waste rules is expected to keep replacement-driven demand steady even as the initial post-ban adoption surge moderates into a more mature, replenishment-driven demand pattern.
MEA & Latin America Paper Straw Market Insights
Growth in the market for paper straws in the Middle East & Africa region is driven by initiatives taken by the UAE and Saudi Arabia towards imposing bans on single-use plastics, along with developing the hospitality and food service infrastructure, which will be boosted further due to the increase in tourists, and the huge demand for the hospitality and quick service restaurant segment in the UAE.
Latin America has been led by the Brazilian market, which is characterized by an increasing formalization of the foodservice industry and the growing popularity of quick service restaurants of international chains. Mexico and Colombia have started contributing towards demand due to the increased number of restrictions on single use plastics imposed on the national and municipal levels.
Market Dynamics:
Growth Drivers: Single-Use Plastic Bans and Corporate Sustainability Commitments
Widely enforced restrictions on single-use plastic straws throughout North America, Europe, and parts of Asia continue to be the main factor pushing up the demand for paper straws, obliging foodservice providers and beverage companies to change all their straw specifications from plastic to paper in compliance with regulatory timelines rather than on a voluntary sustainability basis. The EU's Single-Use Plastics Directive and a rising number of regulations from individual U.S. states and municipalities have established strong demand, which is largely resistant to economic fluctuations.
Corporate sustainability policies of major quick-service restaurant chains and beverage providers strengthen this regulatory demand, since at the brand level commitments to cut down on single-use plastics lead to consistent adoption of paper straws even in jurisdictions without any official bans, ensuring that the chain maintains the same packaging specifications regardless of the location. This unusual combination of regulatory and voluntary drivers of demand has been giving manufacturers a great deal of confidence about future volume growth despite the relatively thin profit margins of paper straws.
Restraints: Durability Limitations and Cost Premium Versus Plastic
Paper straws still suffer from consumer dissatisfaction about their ability to withstand structural stress, especially in longer-duration beverages due to the likelihood of becoming soggy or falling apart before finishing the drink; this has been only partly overcome through advancements in wet strength and multi-layer coating technologies. Paper straws’ inability to maintain structural integrity is a serious constraint on adoption, particularly in regions where they were introduced without strict quality control standards, leading to negative initial perceptions.
In addition to the durability challenge, paper straws remain significantly more expensive on a unit basis than plastic straws because of the higher cost of the raw material and production process. The higher cost is a serious challenge for food service providers, especially in highly competitive markets such as quick-service beverages retail, where margins tend to be very low. However, this challenge has been greatly reduced by bans on plastic straws, which makes consumers purchase paper straws regardless of their cost.
Opportunities: Regional Manufacturing Investment and Recycled Fiber Innovation
The continued development of regional manufacturing capacity, as evidenced by Huhtamaki’s decision to upgrade its facility in Paris, Texas, and Transcend Packaging’s new business relationship with ITOCHU Corporation to solidify its pulp and paper supply chain, provides an opportunity for manufacturers to gain the ability to shorten lead times in order to be more competitive than import supply chains. This regionalization of manufacturing facilities is especially beneficial for foodservice customers that can’t afford the risk associated with long-lead-time imports.
Recycled paper fiber innovations and improved wet strength coating technologies provide additional opportunities to grow the addressable market by improving performance parity between recycled and virgin paper straws, enabling manufacturers to satisfy sustainability requirements of their customers while not compromising on performance requirements of foodservice customers. Manufacturers that will be able to produce high-performing recycled paper straws will be able to command premium prices from their sustainability-minded customers.
Recent Developments:
-
June 2024- Aardvark Straws secured expanded supply agreements with hospitality and food service distributors to strengthen its commercial distribution network across North America.
-
July 2023- Huhtamaki Oyj announced a USD 30 million investment to expand its Paris, Texas manufacturing facility, increasing North American foodservice packaging capacity with production ramping up in the first quarter of 2025.
-
April 2023- Transcend Packaging Ltd. entered a strategic partnership and investment agreement with ITOCHU Corporation to strengthen its pulp and paper supply chain and international distribution.
-
February 2023- Hoffmaster Group, Inc. completed the acquisition of Paterson Pacific Parchment Company, expanding its foodservice paper and parchment product portfolio.
-
November 2022- Huhtamaki completed a EUR 20 million expansion of its paper-based packaging facility in Nules, Spain, doubling the site's production capacity.
Paper Straw Market Key Players:
-
Huhtamaki Oyj
-
Hoffmaster Group, Inc.
-
Precision Products Group (Aardvark Straws)
-
Transcend Packaging Ltd.
-
BioPak Pty Ltd.
-
Canada Brown Eco Products Ltd.
-
Charta Global Inc.
-
Fuling Global Inc.
-
SEDA International Packaging Group S.p.A.
-
Hotpack Global
-
YUTO Packaging Technology Co., Ltd.
-
Stora Enso Oyj
-
Pactiv LLC
-
Eco-Products, Inc.
-
Footprint International, LLC
-
Uflex Ltd.
-
Vegware Ltd.
-
WinCup, Inc.
-
Genpak, LLC
-
Green Paper Products Co.
Paper Straw Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 3.84 Billion |
| Market Size by 2035 | USD 7.96 Billion |
| CAGR | CAGR of 7.60% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Type (Flexible and Non-Flexible) • by Material (Virgin Kraft Paper and Recycled Paper) • by End-Use (Food Service, Institutional, and Household) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Huhtamaki Oyj, Hoffmaster Group, Inc., Precision Products Group (Aardvark Straws), Transcend Packaging Ltd., BioPak Pty Ltd., Canada Brown Eco Products Ltd., Charta Global Inc., Fuling Global Inc., SEDA International Packaging Group S.p.A., Hotpack Global, YUTO Packaging Technology Co., Ltd., Stora Enso Oyj, Pactiv LLC, Eco-Products, Inc., Footprint International, LLC, Uflex Ltd., Vegware Ltd., WinCup, Inc., Genpak, LLC, Green Paper Products Co. |
Frequently Asked Questions
Key players in the Paper Straw Market include Huhtamaki Oyj, Hoffmaster Group, Precision Products Group (Aardvark Straws), Transcend Packaging Ltd., and BioPak Pty Ltd., among others.
Key opportunities lie in regional manufacturing investment that shortens lead times against import supply, and in recycled paper fiber and wet-strength coating innovations that narrow the durability gap with virgin kraft paper straws.
Expanding single-use plastic straw bans across North America, Europe, and parts of Asia, reinforced by corporate sustainability commitments from major foodservice chains, are the major growth factors.
By Type, the Flexible segment dominated the Paper Straw Market with approximately 54.30% share in 2025.
North America dominated the Paper Straw Market with approximately 33.60% share in 2025, supported by widespread plastic straw bans and strong domestic manufacturing capacity.
