
Greases Market Report Scope & Overview:
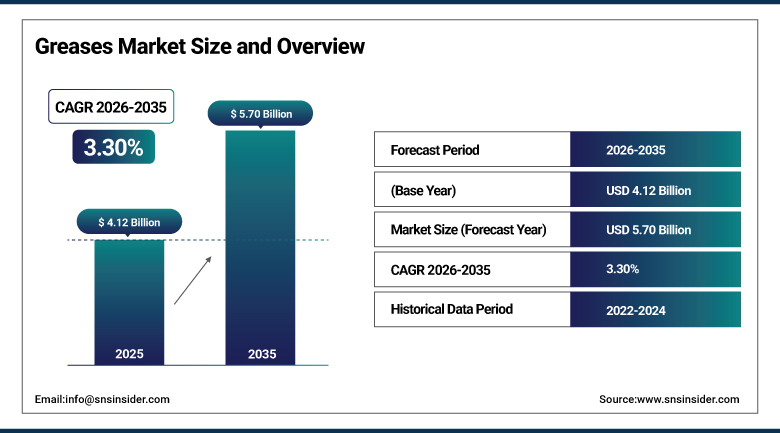
The Greases Market was valued at USD 4.12 Billion in 2025 and is expected to reach USD 5.70 Billion by 2035, growing at a CAGR of 3.30% from 2026-2035.
Greases Market is growing at a steady pace due to the demand for lubricants that remain adhered to surfaces in conditions of heat, load and contamination in industrial operations, automobile manufacturing and equipment maintenance services. Growth is being driven by increasing demand from automotive, construction, mining and general manufacturing, and from new applications of electric vehicle drivetrains and wind turbines which require advanced and high-temperature performance. Synthetic, bio-based and long-life greases are being developed by manufacturers to comply with environmental requirements and to minimize the need for reapplication, while producers in Asia Pacific increase their production capacity in proximity to the growing industrial facilities in the region. Demand for advanced greases is outpacing that for conventional greases.
⮞Producers are building capacity close to growing industrial demand. In March 2024, Shell announced plans for its first grease plant in Indonesia, at the Marunda complex in Bekasi, with capacity of up to 12 kilotons per year. The investment shows how major lubricant suppliers are localizing production in Southeast Asia, where manufacturing and mining activity is rising and where local supply shortens delivery times for industrial customers.
To Get more information Greases Market - Request Free Sample Report
Greases Market Trends:
-
Shift from conventional lithium greases toward calcium sulfonate complex and polyurea thickeners
-
Development of synthetic and bio-based greases to meet environmental standards
-
Demand for long-life, sealed-for-life and high-temperature grades in electric vehicles and wind turbines
-
Localization of grease production plants in Asia Pacific and the United States
-
Growth of automatic lubricators and condition-based relubrication
U.S. Greases Market Outlook:
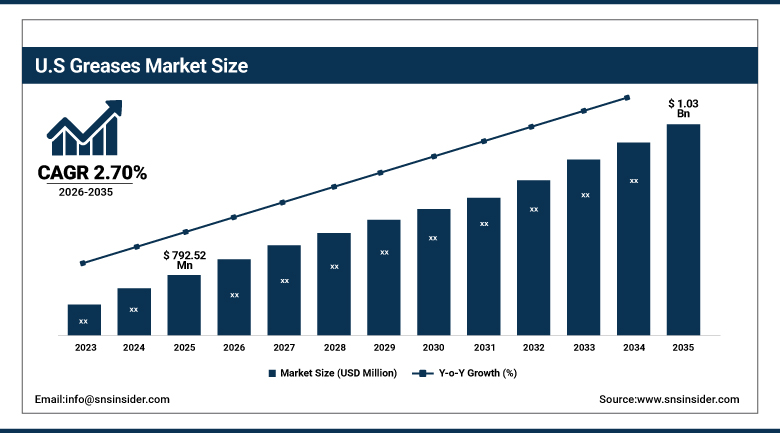
The U.S. Greases Market was valued at USD 792.52 Million in 2025 and is expected to reach USD 1.03 Billion by 2035, growing at a CAGR of 2.70% from 2026-2035.
The U.S. Greases Market is supported by a large base of automotive, heavy-duty truck, construction, rail, mining and agricultural equipment, a mature industrial maintenance culture and the presence of leading lubricant suppliers. Demand centers on multi-purpose, high-temperature and extreme-pressure greases, and calcium sulfonate complex grades are gaining share in wet and heavily loaded applications. Growth is moderated by maturity, but capacity additions by local and foreign suppliers and renewed investment in manufacturing and infrastructure sustain steady volumes.
⮞Local capacity is being added to ease supply constraints. In June 2024, Lucas Oil announced the opening of a grease manufacturing facility in Harrison County, Indiana, within a 400,000-square-foot production site, adding a dedicated production area for industrial and commercial greases. The company said the space is intended to help address a national grease shortage that followed pandemic-related supply chain disruptions and to improve its ability to develop more advanced formulations.
Greases Market Segment Analysis:
-
By Base Oil, mineral oil segment dominated the Greases Market in 2025 with an estimated 68.90% share; bio-based oil segment is the fastest-growing segment, with an estimated CAGR of 5.20% during 2026–2035.
-
By Thickener Type, metallic soap segment dominated the Greases Market in 2025 with an estimated 63.20% share; non-soap segment is the fastest-growing segment, with an estimated CAGR of 4.10% during 2026–2035.
-
By End-Use Industry, automotive segment dominated the Greases Market in 2025 with 34.50% share; power generation segment is the fastest-growing segment, with an estimated CAGR of 4.82% during 2026–2035.
By Base Oil, Mineral Oil Dominates Greases Market; Bio-Based Oil to Register Fastest Growth.
Mineral oil dominates the Greases Market because it is inexpensive, widely available and performs adequately across the large majority of automotive and industrial applications. Group I to Group III base stocks can be blended with a wide range of thickeners and additive packages, giving formulators flexibility to meet cost targets and performance specifications. Established supply chains from major refiners and the familiarity of maintenance teams with mineral oil greases keep volumes high, particularly in general manufacturing, construction and agriculture, where operating conditions are moderate and relubrication is routine.
Bio-based oil is projected to register the fastest growth from a small base as environmental regulation, procurement policies and corporate sustainability targets encourage biodegradable lubricants in sensitive applications. Greases based on vegetable and synthetic ester oils are used in forestry, marine, food processing and water-related equipment where leakage can affect ecosystems. Synthetic oils such as polyalphaolefins and esters also gain share in extreme-temperature and long-life uses, supported by electric vehicle components and wind turbines that require extended service intervals and low-temperature startup performance.
By Thickener Type, Metallic Soap Dominates Greases Market; Non-Soap to Register Fastest Growth.
Metallic soap thickeners dominate the Greases Market because lithium and lithium complex soaps deliver a balanced combination of water resistance, mechanical stability and temperature range at competitive cost. They are compatible with many base oils and additives and are well understood by formulators and end users, which supports their use as multi-purpose greases in vehicles and industrial equipment. Calcium sulfonate complex and aluminum complex soaps add extreme-pressure and corrosion resistance for mining, steel and marine duties, and suppliers continue to expand dedicated kettle capacity for these premium soap grades.
Non-soap thickeners are projected to register the fastest growth because polyurea and similar organic systems provide long life, oxidation stability and high-temperature performance that soap greases struggle to match. They are widely used in sealed-for-life bearings, electric motors, automotive constant velocity joints and steel mill applications where relubrication is difficult or costly. Inorganic thickeners such as bentonite clay and silica are used in very high-temperature and specialty service, and demand for them is tied to heavy industrial processes in which dropping point and thermal stability are more important than cost.
By End-Use Industry, Automotive Dominates Greases Market; Power Generation to Register Fastest Growth.
Automotive dominates the Greases Market because every vehicle uses greases in wheel bearings, chassis points, constant velocity joints, steering and brake components, and because trucks, buses and off-highway fleets require regular relubrication. Large vehicle production in Asia Pacific and a sizeable fleet in service in North America and Europe sustain demand for both factory fill and aftermarket products. The shift to electric vehicles changes requirements toward low electrical conductivity, high-speed bearing performance and noise reduction, which encourages development of new automotive grease grades.
Power generation is projected to register the fastest growth as wind turbine installations, gas turbine maintenance and expansion of electricity capacity in emerging economies increase use of high-performance greases. Wind turbine main bearings, pitch and yaw systems and gearboxes operate under heavy load, vibration and wide temperature ranges, and operators prefer long-life products to reduce costly maintenance visits. Construction and off-highway, steel, mining and agriculture remain important consumers, with growth tied to infrastructure investment, commodity activity and mechanization of farming in developing countries.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
Asia Pacific |
China |
48.20% |
|
Europe |
Germany |
27.12% |
|
North America |
United States |
84.56% |
|
Latin America |
Brazil |
45.25% |
|
Middle East & Africa |
Saudi Arabia |
30.76% |
North America Greases Market Insights
North America is the third-largest region, growing at a CAGR of 2.70% during 2026-2035. The United States accounts for most regional demand, supported by its automotive, heavy-duty truck, rail, construction, mining and agricultural equipment base, while Canada adds volumes through resource extraction and Mexico through automotive manufacturing. Lucas Oil opened a new grease production area in Indiana in 2024, and FUCHS has operated grease plants in Kansas City, Missouri, and Harvey, Illinois. Industrial distributors play an important role in reaching maintenance buyers, and private-label offerings compete in commodity multi-purpose grades.
A national grease shortage after pandemic-related disruptions highlighted the importance of local supply, and AXEL Americas has announced plans to add calcium sulfonate complex grease capacity in Rosedale, Mississippi, as well as cartridge filling capacity in Tulsa, Oklahoma, and Schertz, Texas. Mature markets moderate growth, but infrastructure investment, reshoring of manufacturing and demand for long-life products in wind power and electric vehicles support steady volumes. Replacement of aging equipment and growing attention to predictive maintenance programs encourage the use of higher-quality products that extend service intervals.
Europe Greases Market Insights
Europe is the second-largest region, growing at a CAGR of 2.60% during 2026-2035. Germany leads regional demand through its automotive, machinery and bearing industries, followed by Italy, France, the United Kingdom and Spain. The region is home to specialist grease producers including FUCHS and Klüber Lubrication, which focus on high-performance, long-life and environmentally acceptable products and supply customers worldwide from European technology centers. Scandinavian and Central European countries also maintain strong paper, steel and machinery industries that depend on dependable lubrication of heavy bearings.
Environmental regulation, including rules on hazardous substances and the European Ecolabel for lubricants, encourages bio-based and low-toxicity formulations. A mature vehicle fleet and industrial base limit volume growth, but wind power, rail and electric vehicle component manufacturing add demand for specialty grades. Klüber Lubrication merged with OKS in October 2025, strengthening a specialty lubricant portfolio that serves industrial maintenance customers across the region, and suppliers are investing in automatic lubricators and condition-based relubrication services. Regional buyers also place emphasis on supplier technical service and documented product performance, which favors established brands.
Asia Pacific Greases Market Insights
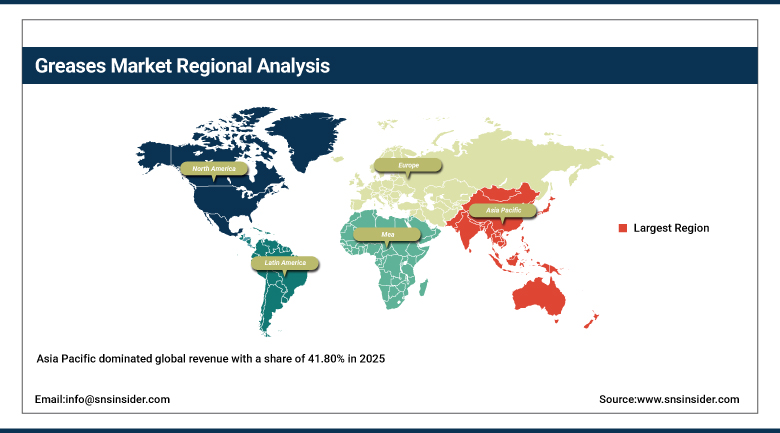
Asia Pacific dominated global revenue with a share of 41.80% in 2025 and is also projected to be the fastest-growing region, at a CAGR of 4.00% from 2026-2035. China is the largest country market, supported by its vehicle, steel, construction and machinery industries and by local producers such as Sinopec Lubricant, while India, Japan and South Korea add significant demand. FUCHS opened a high-performance grease plant in Yingkou, China, in May 2024, and Shell is building its first grease plant in Indonesia. Regional demand is also supported by large two-wheeler and commercial vehicle fleets, which require frequent relubrication of chassis and wheel components.
India's expanding automotive, mining and infrastructure sectors support steady growth, and companies such as Balmer Lawrie supply industrial and automotive greases. Japan hosts specialist suppliers including Idemitsu and ENEOS and a large bearing and machinery industry that requires high-specification products. Southeast Asian economies are increasing demand through manufacturing relocation, mining and plantation activity, and Australia contributes through mining equipment maintenance. Rising vehicle ownership and large-scale infrastructure programs are expected to sustain regional volume growth. Local blending and filling plants are being added to serve distributors and to reduce import dependence for specialty grades.
Get Customized Report as per Your Business Requirement - Enquiry Now
MEA & Latin America Greases Market Insights
In Latin America, Brazil leads on the strength of its automotive, agriculture, mining and steel industries, followed by Mexico, Argentina and Chile. Mining activity in Chile and Peru requires heavy-duty calcium sulfonate and extreme-pressure greases, and agricultural mechanization supports demand for multi-purpose products. Economic volatility and import dependence for specialty grades can affect pricing and availability. Colombia and Peru add demand through mining and agricultural machinery fleets that rely on imported and locally blended products. Cement, sugar and pulp plants also create steady industrial maintenance demand.
In the Middle East and Africa, Saudi Arabia and the United Arab Emirates lead through construction, oil and gas and industrial diversification, while South Africa supplies regional mining demand. FUCHS Lubricants South Africa launched RENOLIT CSX ULTRA, a calcium sulfonate complex grease for mining equipment, in April 2024. Luberef plans to start expanded base oil capacity at Yanbu in the second half of 2026, which supports regional supply, and infrastructure projects across Africa add gradual demand for construction and mining equipment greases. Regional distributors and industrial service providers help suppliers reach remote mining and farming sites, where reliable lubrication is essential to equipment availability.
Market Dynamics:
Growth Drivers: Industrial Activity, Vehicle Production and High-Performance Formulations
Industrial operations and automobile production are the key growth drivers of the Greases Market. All the bearings, joints and sliding components in machines, cars and equipment need grease for protection from wear, corrosion and contamination, and thus the demand is directly correlated with the industrial output, construction and mining activities. Development of manufacturing industries, infrastructure projects and increased number of cars in Asia-Pacific ensures steady volume growth, while maintenance activities in mature markets ensure replacement demand. Growing fleet of equipment also increases the installed base that requires frequent regreasing.
Value growth comes from increased demand for higher quality products. Electric cars, wind turbines and modern factories need grease that can operate under high speeds and wide range of temperatures for long service life periods, and customers are ready to spend more for such products that decrease downtime and relubrication costs. Manufacturers that can offer their customers polyurea, calcium sulfonate complex and synthetic greases have good potential for growth above the industry average. Increased awareness of cost of equipment failures ensures premium products sales. Growth of construction and mining equipment fleets in developing markets increases the installed base of equipment that needs lubrication.
Restraints: Mature Demand, Raw Material Volatility and Substitution by Oils and Sealed Bearings
Slow demand growth is seen in mature markets because there is saturation of vehicle fleets and industrial bases. Longer-life greases mean less volume of grease per machine. Oil, lithium, and additive price fluctuations are seen to impact margin, while any disruptions in supplies lead to shortage situations, such as those observed following the pandemic. It will be difficult for smaller suppliers to pass along cost increases to industrial segments. Private label pressures are felt due to pricing competition. Operators can also increase relubrication intervals by condition monitoring. This results in lower consumption per machine despite the growth in the number of machines.
Growth is constrained by substitution. Sealed-for-life bearings and electrical elements that need no relubrication mean reduced grease usage. Circulating oil system and dry film lubricants can replace grease in some applications. Environmental restrictions regarding disposal of used lubricants and tighter limits on additives mean additional compliance costs. The shift towards the use of electric vehicles means that some grease points are lost because of internal combustion engine grease points. Manufacturers have to continue reformulation for compliance and performance reasons. Differences in standards and approvals also mean additional costs of product introduction to other markets.
Opportunities: Electric Vehicle Drivetrains, Wind Power and Bio-Based Greases
Special greases are possible in electric vehicle drivetrains and wind power generation. Electric motors and reducers need grease with low electrical conductivity and reduced noise and stability at high speeds, while wind turbines need long-lasting greases with excellent resistance to water and vibrations. Suppliers who qualify their products with car and turbine producers can have multi-year supply agreements with higher margins compared to the commodity multi-use greases. Co-development with the original equipment manufacturer can also ensure long-term supply contracts. Cooperation of grease producers and bearing as well as wind turbine producers will result in co-development of products with high qualification barriers to competitors.
Bio-based and recycle greases provide additional possibilities as the consumers strive to achieve sustainability targets. Greases with the use of vegetable and ester oils are possible in forest industries, marine and food processing industries, while the collection and recycling programs of lubricants are being developed in many countries. Automated lubrication and condition-based relubrication services can generate recurring revenue through the grease supply linked with monitoring equipment. Digital services can distinguish suppliers and build relationships with customers. Expansion into emerging markets with local blending and filling is also possible.
Recent Developments:
-
2024, FUCHS China opened a high-performance grease plant in Yingkou. The plant adds local capacity for specialty greases and supports supply to industrial customers in the Chinese market.
-
2025, Klüber Lubrication merged with OKS. The combination brings together specialty lubricant portfolios and distribution channels serving industrial maintenance customers.
-
2026, NYCO said its Newnan, Georgia, facility is fully operational for synthetic esters. The plant supports supply of synthetic ester base oils used in high-performance lubricants and greases.
-
2026, LANXESS opened a lubricant additives blending plant in Jhagadia, Gujarat. The plant strengthens local supply of additive packages to lubricant and grease formulators in India.
Greases Market Key Players:
-
Shell plc
-
Exxon Mobil Corporation
-
Chevron Corporation
-
FUCHS SE
-
TotalEnergies SE
-
Idemitsu Kosan Co., Ltd.
-
Klüber Lubrication (Freudenberg Group)
-
SKF Group
-
Phillips 66 Lubricants
-
Sinopec Lubricant Company
-
BP p.l.c. (Castrol)
-
ENEOS Corporation
-
PETRONAS Lubricants International
-
PJSC LUKOIL
-
Balmer Lawrie & Co. Ltd.
-
AXEL Americas, LLC
-
Lucas Oil Products, Inc.
-
CITGO Petroleum Corporation
-
NYCO
-
Saudi Arabian Oil Company
Greases Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 4.12 Billion |
| Market Size by 2035 | USD 5.70 Billion |
| CAGR | CAGR of 3.30% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Base Oil (Mineral Oil, Synthetic Oil, Bio-Based Oil) • By Thickener Type (Metallic Soap, Non-Soap, Inorganic) • By End-Use Industry (Automotive, Construction and Off-Highway, General Manufacturing, Steel and Metal Production, Mining, Power Generation, Agriculture, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Shell plc, Exxon Mobil Corporation, Chevron Corporation, FUCHS SE, TotalEnergies SE, Idemitsu Kosan Co., Ltd., Klüber Lubrication (Freudenberg Group), SKF Group, Phillips 66 Lubricants, Sinopec Lubricant Company, BP p.l.c. (Castrol), ENEOS Corporation, PETRONAS Lubricants International, PJSC LUKOIL, Balmer Lawrie & Co. Ltd., AXEL Americas, LLC, Lucas Oil Products, Inc., CITGO Petroleum Corporation, NYCO, Saudi Arabian Oil Company |

Frequently Asked Questions
Key players include Shell plc, Exxon Mobil Corporation, Chevron Corporation, FUCHS SE, TotalEnergies SE, Idemitsu Kosan Co., Ltd., Klüber Lubrication and SKF Group.
Key opportunities include specialty greases for electric vehicle drivetrains and wind turbines, bio-based and long-life formulations, and local capacity additions in Asia Pacific and North America.
The major growth factor is steady industrial activity and vehicle production, combined with rising demand for high-performance and long-life greases in electric vehicles, wind power and heavy equipment.
By Base Oil, the Mineral Oil segment dominated the market in 2025, supported by low cost, wide availability and suitability for most automotive and industrial applications.
Asia Pacific dominated the market with a share of 41.80% in 2025, driven by large manufacturing, automotive, steel and construction industries in China, India and Japan.
