
High Density Interconnect Market Report Scope & Overview:
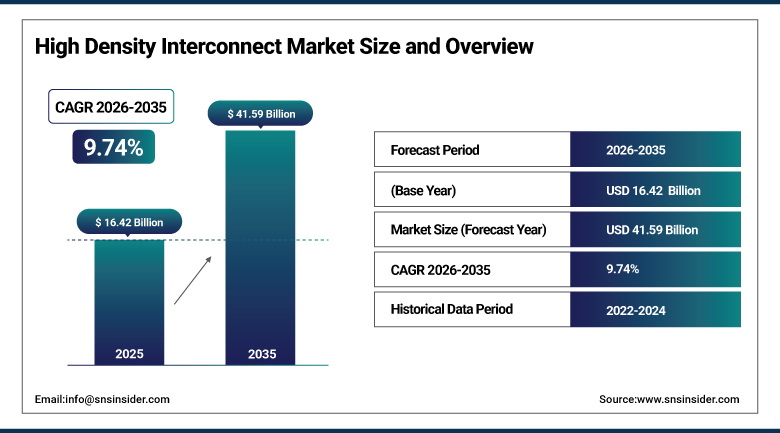
The High Density Interconnect Market was valued at USD 16.42 Billion in 2025 and is expected to reach USD 41.59 Billion by 2035, growing at a CAGR of 9.74% from 2026-2035.
The High Density Interconnect Market covers printed circuit boards that use microvias, fine lines and spaces, and sequential build-up layers to pack more connections into a smaller area than standard boards. They are used in smartphones, wearables, servers, vehicle electronics, medical devices and defense systems. Growth is supported by device miniaturization, AI servers, advanced driver assistance and 5G, while material costs, yield challenges and capital intensity shape investment and pricing.
⮞On September 29, 2026, Samsung Electro-Mechanics announced investments of about KRW 6.78 trillion, roughly USD 5.00 billion, with KRW 4.27 trillion for its Sejong site in South Korea and KRW 2.51 trillion for its Vietnam subsidiary. The money is for FCBGA semiconductor substrates serving AI servers, high-performance computing and automotive electronics, with the Vietnam site targeting operation by June 2030.
To Get more information High Density Interconnect Market - Request Free Sample Report
High Density Interconnect Market Trends
-
Any-layer and ultra-HDI boards with finer lines for AI and defense electronics
-
Growth of HDI in advanced driver assistance and vehicle computing
-
Laser drilling and modified semi-additive processes for finer features
-
Low-loss materials for high-speed servers and 5G equipment
-
Production moving to Southeast Asia, India and Mexico to diversify supply
-
Automation and AI inspection that improve yield on fine-pitch boards
U.S. High Density Interconnect Market Outlook
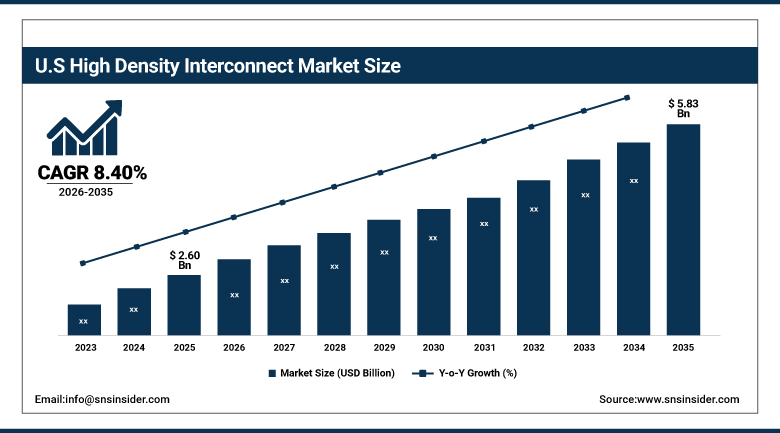
The U.S. High Density Interconnect Market was valued at USD 2.60 Billion in 2025 and is expected to reach USD 5.83 Billion by 2035, growing at a CAGR of 8.40% from 2026-2035.
The U.S. High Density Interconnect Market is the largest national market in the region, supported by aerospace and defense programs, data center and networking equipment, medical devices and a push to rebuild local electronics supply chains. Demand is concentrated in high-reliability and low-volume advanced boards. Growth is moderated by high labor costs, limited local capacity and reliance on Asian supply for consumer volumes.
⮞On June 22, 2026, TTM Technologies held the grand opening of its 215,000 square foot Ultra-HDI manufacturing facility in Syracuse, New York, a USD 130.00 million project that includes USD 30.00 million from the U.S. Department of War. The plant makes ultra-high-density boards and advanced packaging for radar, missile defense, space sensors and autonomous systems.
High Density Interconnect Market Segment Analysis
-
By Build-Up Type, 1+N+1 HDI segment dominated the High Density Interconnect Market in 2025 with an estimated 44.00% share; 3+N+3 HDI segment is the fastest-growing segment, with an estimated CAGR of 12.40% during 2026–2035.
-
By Substrate Material, FR-4 segment dominated the High Density Interconnect Market in 2025 with an estimated 49.00% share; polyimide segment is the fastest-growing segment, with an estimated CAGR of 12.20% during 2026–2035.
-
By Application, smartphones and tablets segment dominated the High Density Interconnect Market in 2025 with an estimated 29.50% share; automotive electronics segment is the fastest-growing segment, with an estimated CAGR of 12.00% during 2026–2035.
By Build-Up Type, 1+N+1 HDI Dominates High Density Interconnect Market; 3+N+3 HDI to Register Fastest Growth.
The 1+N+1 build-up type dominates the High Density Interconnect Market because it offers a useful step up in density over standard boards at moderate cost and with high yields. One layer of microvias on each side of a core board suits many mid-range phones, wearables, tablets, cameras and vehicle modules. Most fabricators can produce it at scale, which keeps prices competitive. Standard laser drilling, plating and lamination steps are used, so fabricators can move existing lines to new designs quickly, and customers can place orders with several qualified suppliers, which keeps this build-up type the main volume product. Short lead times and engineering support are also valued by customers.
The 3+N+3 HDI segment is positioned for strong growth as electronic systems increasingly require higher interconnection density, advanced routing capabilities, and improved signal integrity. Its multiple build-up layers support complex circuit designs in applications such as artificial intelligence servers, high-performance computing, advanced telecommunications equipment, and automotive electronics. The growing integration of sophisticated processors and high-speed components is increasing demand for advanced HDI architectures. As manufacturers develop more compact and powerful electronic systems, adoption of higher build-up structures is expected to expand, although growth rates vary across applications and market forecasts.
By Substrate Material, FR-4 Dominates High Density Interconnect Market; Polyimide to Register Fastest Growth.
FR-4 dominates the High Density Interconnect Market because this glass-reinforced epoxy laminate is low cost, widely available and well understood by fabricators. Variants with high glass transition temperature and low halogen content meet needs in consumer electronics, networking and automotive modules. Long qualification histories keep many designs on FR-4. Lower-cost laminates are also available from many suppliers, which gives designers flexibility on price and performance. Fabricators keep inventories of common grades, and long relationships with laminate makers support supply during shortages.
Polyimide is projected to register the fastest growth as flexible and rigid-flex HDI boards are adopted in foldable phones, wearables, cameras, medical devices and vehicle sensors. The material tolerates heat and bending and supports thin, lightweight designs. Demand for high-speed, low-loss materials is also lifting use of advanced laminates in servers. Liquid crystal polymer and modified polyimide films are also being tested for high-frequency use, and manufacturers invest in roll-to-roll and laser processing to produce thin flexible circuits with fine features at scale.
By Application, Smartphones and Tablets Dominates High Density Interconnect Market; Automotive Electronics to Register Fastest Growth.
Smartphones and tablets dominate the High Density Interconnect Market because these devices require very compact boards with large numbers of components, and annual volumes run into the billions. Each new generation adds cameras, sensors and antennas, which increases density needs. Large brands source HDI boards from a small group of experienced fabricators. Product cycles are short and volumes are very large, so suppliers invest ahead of annual launches and share design data with customers early. Tablets, laptops and wearables follow similar trends, adding to board demand. Replacement cycles in premium phones keep demand for advanced boards steady.
Automotive electronics is projected to register the fastest growth as vehicles add cameras, radar, domain controllers, infotainment and battery management units that need compact, reliable boards. Electric and software-defined vehicles use more electronics per car, and safety rules demand high quality and long life, which favors advanced HDI suppliers with automotive certification. Autonomous driving functions need processing boards with high-speed memory and power management, and each vehicle may use dozens of HDI boards across sensors, ECUs and displays, a far higher count than in earlier vehicle generations.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
46.00 |
|
North America |
United States |
88.00 |
|
Europe |
Germany |
27.00 |
|
MEA |
Israel |
32.00 |
|
Latin America |
Mexico |
34.00 |
North America High Density Interconnect Market Insights
North America is the second-largest region, with a share of 18.00% in 2025, and is projected to grow at a CAGR of 8.40% during 2026-2035. The United States accounts for about 88.00% of regional demand, with Canada and Mexico adding volume. TTM Technologies, Sanmina, Benchmark, Jabil, Sierra Circuits, Eagle Electronics and Advanced Circuits serve the region. Programs funded by federal agencies support local production of trusted electronics for defense and aerospace. Fabricators with security clearances and certified processes have a clear advantage in this segment.
Aerospace and defense programs, data center hardware, medical devices and industrial equipment drive demand for high-reliability boards. Government funding and security rules favor local production for sensitive systems. High labor and compliance costs, limited skilled workers and reliance on imported materials moderate growth, though reshoring programs are adding capacity. Data center growth and AI server builds in the United States are adding demand for high-layer-count boards and advanced packaging, although much of the volume is still produced in Asia and shipped for final assembly. Medical device makers also buy small, dense boards.
Europe High Density Interconnect Market Insights
Europe is the third-largest region, with a share of 17.00% in 2025, and is projected to grow at a CAGR of 7.80% during 2026-2035. Germany, Austria, France, the United Kingdom, Italy and Finland lead regional demand. AT&S, Schweizer Electronic, Würth Elektronik, Cicor, NCAB, Eurocircuits and TTM's European units serve the region. Automotive suppliers in Germany and Central Europe account for much of regional demand, and Austria hosts one of the world's major HDI and substrate producers. Nordic firms serve telecom and industrial customers. Industrial automation firms in Italy and Finland also use advanced boards.
Demand comes from automotive, industrial automation, medical and aerospace customers who value quality, traceability and short supply lines. Regional initiatives aim to strengthen chip and electronics supply, including advanced substrates. High energy costs, strict environmental rules and competition from Asia moderate growth, though specialty and high-reliability boards remain competitive. The EU Chips Act and national programs encourage investment in advanced packaging and substrates, and customers in medical and aerospace sectors value local sourcing for security and traceability reasons. Suppliers also offer quick-turn prototyping.
Asia Pacific High Density Interconnect Market Insights
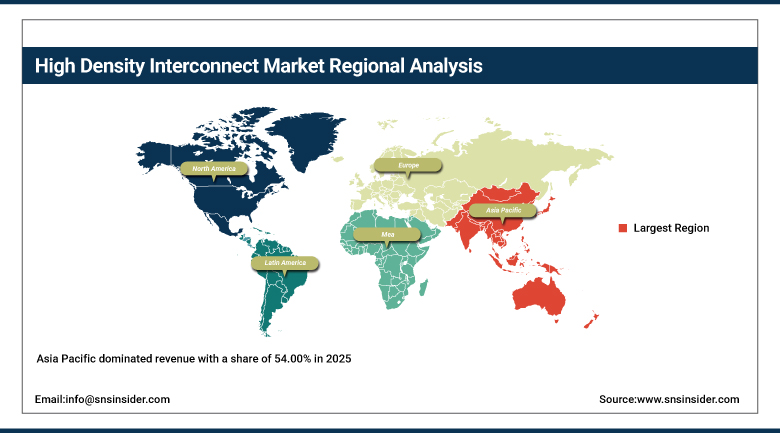
Asia Pacific dominated revenue with a share of 54.00% in 2025, and is projected to be the fastest-growing region, at a CAGR of 10.80% during 2026-2035. China, Taiwan, Japan, South Korea, Vietnam and India lead regional demand. Unimicron, Zhen Ding, Compeq, Tripod, Nan Ya PCB, Ibiden, Meiko, Samsung Electro-Mechanics and Shennan Circuits serve the region. China accounts for about 46.00% of regional demand. Taiwan leads in advanced HDI and substrate technology, while mainland China provides scale and cost advantages and Japan supplies materials, chemicals and equipment. South Korea is strong in mobile and memory-related boards. Local material suppliers help fabricators lower costs.
The region hosts nearly all consumer electronics assembly, the deepest supply chain for laminates, chemicals and equipment, and the largest HDI fabricators. Producers are adding capacity in Vietnam, Thailand and India to diversify away from a single country. Price competition, rising wages and heavy capital spending moderate growth, but AI server and vehicle demand support investment. Governments in India and Vietnam offer incentives to attract electronics production, and brands are asking suppliers to open plants in these countries. This is shifting the geographic spread of HDI capacity within the region.
⮞In December 2024, Taiwan-based HDI PCB manufacturer Compeq Manufacturing opened its first Southeast Asian production facility in Thailand, with initial mass production planned for the first quarter of 2025.
Get Customized Report as per Your Business Requirement - Enquiry Now
MEA & Latin America High Density Interconnect Market Insights
In Latin America, Mexico leads, followed by Brazil, with regional demand growing at about 9.00% annually. Mexico benefits from nearshoring of automotive and electronics assembly, and board fabricators and assemblers are expanding to serve U.S. customers. Brazil serves its local market with duties favoring local production. Maquiladora clusters in Tijuana, Guadalajara and Monterrey assemble electronics, and fabricators are moving closer to these hubs. Free trade agreements and shorter shipping times support the shift. Customs duties on imported boards can influence sourcing in Brazil.
In the Middle East and Africa, Israel, Turkey, the United Arab Emirates and Saudi Arabia lead demand, with growth of about 9.40% annually. Defense electronics, telecom equipment and new electronics manufacturing zones create demand, while a lack of local laminate and chemical supply means most advanced boards are imported. Israel has a strong defense and communications electronics base that buys advanced boards, and Gulf states are building electronics manufacturing zones under industrial diversification programs, though talent and supply chains remain limited.
Market Dynamics
Growth Drivers: Miniaturization, AI Hardware and Vehicle Electronics
Smaller and more powerful devices require denser boards, and AI servers and networking equipment need high-layer-count, high-speed designs. Adoption of 5G and Wi-Fi 7, along with higher data rates in servers, requires boards with lower signal loss and tighter impedance control, which only advanced HDI processes can deliver. Rising adoption of foldable phones, extended reality headsets and smart glasses adds products that rely on compact flexible-rigid circuits, which broadens demand beyond traditional smartphones. Governments and corporations are also investing in sovereign AI compute and edge devices, which creates additional demand for advanced boards in regions that previously relied on imported systems, and diversifies the customer base for fabricators. Growth in cloud data centers and edge computing also raises demand for network switches and accelerator cards that depend on high-layer HDI boards.
Vehicles are adding cameras, radar and controllers, which multiplies the number of HDI boards used in each car. Growing use of wearables, hearing devices and implantable medical electronics also adds demand for very small, reliable circuits. Expanding satellite constellations and low-earth-orbit communication equipment also use compact high-reliability boards, creating a new group of buyers. Increased use of electric power tools, e-bikes and portable medical equipment adds consumer and healthcare volumes that favor compact boards. Longer product life and repairability rules may increase demand for reliable, high-quality boards.
Restraints: Capital Cost, Yield Challenges and Material Prices
New HDI lines need large investment in lasers, imaging and plating equipment, and qualification takes time. Environmental rules on chemicals, water and waste raise compliance cost, and permits for new plants can take a long time in some regions. Customer concentration is a risk, as a few large brands account for a large share of orders, and changes in their sourcing can quickly shift utilization across plants. Price pressure from large customers who seek yearly cost reductions, combined with rising energy and labor expenses, can squeeze margins for smaller fabricators that lack scale or a strong technology advantage. Skills shortages and strict environmental permits can slow plant expansion even where demand is strong.
Fine features reduce yields, and prices of copper, laminates and gold swing, squeezing margins when customers push for price cuts. Shortages of skilled process engineers and technicians slow the ramp-up of new lines and raise labor costs. Trade restrictions and tariffs can disrupt flows of equipment and materials, and uncertainty makes long investment decisions harder. Dependence on a few suppliers for specialty laminates, films and drilling equipment can cause delays when demand surges across the industry. Counterfeit components and quality escapes can harm trust and lead to costly recalls. Investment cycles in the industry are long and demand swings with smartphone and server upgrades, which can leave new plants underused for a time.
Opportunities: Supply Chain Diversification, Ultra-HDI and Defense Electronics
Customers want second sources outside a single country, which opens room for plants in Southeast Asia, India, Mexico and the United States. Partnerships between board makers and chip packaging firms can create integrated offers for AI accelerators and advanced modules. Automation, digital twins and AI-based inspection allow fabricators to reduce scrap and shorten cycle times, supporting profitability on complex boards. Wider acceptance of new materials such as low-loss laminates, resin-coated copper and glass cores can help fabricators serve next-generation servers and packaging, and secure higher-value contracts.
Ultra-HDI boards for defense, space and advanced packaging command higher prices and long contracts. Recycling of copper and precious metals from scrap boards, and greener plating chemistry, offer cost savings and sustainability benefits. Rising demand for advanced packaging substrates may lead board makers to move upmarket and add new product lines with higher margins. Emerging markets with growing electronics demand, such as India and Brazil, may support regional fabrication when governments offer incentives. Government grants and tax credits for advanced electronics plants in the United States, Europe and India reduce the risk of large investments and attract fabricators to build local capacity close to customers. Rising need for repair, rework and refurbishment services for high-value boards adds recurring revenue for fabricators.
Recent Developments:
-
In May 2025, Compeq Manufacturing reported strong growth in its low-Earth-orbit satellite communications segment, reflecting increasing opportunities for HDI circuit boards in satellite connectivity and emerging communications infrastructure.
-
2023: Taiwanese PCB manufacturer Unimicron Technology identified artificial intelligence, high-performance computing and high-speed transmission networking as strategic development areas, reflecting growing opportunities for advanced circuit-board technologies in computing infrastructure.
High Density Interconnect Market Key Players are
-
TTM Technologies, Inc.
-
Unimicron Technology Corp.
-
AT&S Austria Technologie & Systemtechnik AG
-
Samsung Electro-Mechanics Co., Ltd.
-
Zhen Ding Technology Holding Ltd.
-
Compeq Manufacturing Co., Ltd.
-
Meiko Electronics Co., Ltd.
-
Sanmina Corporation
-
Schweizer Electronic AG
-
Würth Elektronik GmbH & Co. KG
-
Kinwong Electronic Co., Ltd.
High Density Interconnect Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 16.42 Billion |
| Market Size by 2035 | USD 41.59 Billion |
| CAGR | CAGR of 9.74% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Build-Up Type (1+N+1 HDI, 2+N+2 HDI, 3+N+3 HDI, and Others) • By Substrate Material (FR-4, Polyimide, and Others) • By Application (Smartphones and Tablets, Automotive Electronics, Telecommunications and Data Centers, Medical and Industrial, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | TTM Technologies, Inc., Unimicron Technology Corp., AT&S Austria Technologie & Systemtechnik AG, Samsung Electro-Mechanics Co., Ltd., Zhen Ding Technology Holding Ltd., Compeq Manufacturing Co., Ltd., Meiko Electronics Co., Ltd., Sanmina Corporation, Schweizer Electronic AG, Würth Elektronik GmbH & Co. KG, Kinwong Electronic Co., Ltd. |

Frequently Asked Questions
Key players include TTM Technologies, Inc., Unimicron Technology Corp., AT&S Austria Technologie & Systemtechnik AG, Samsung Electro-Mechanics Co., Ltd., Zhen Ding Technology Holding Ltd., Compeq Manufacturing Co., Ltd., Ibiden Co., Ltd. and Meiko Electronics Co., Ltd.
Key opportunities include supply chain diversification, ultra-HDI for defense and growth in AI hardware.
The major growth factor is device miniaturization and the rise of AI servers and vehicle electronics.
By Build-Up Type, the 1+N+1 HDI segment dominated the market in 2025 with an estimated 44.00% share, as it offers higher density at moderate cost and strong yields.
Asia Pacific dominated the market with a share of 54.00% in 2025, driven by consumer electronics assembly and the largest HDI fabricators.
