
Hip Replacement Market Report Scope & Overview:
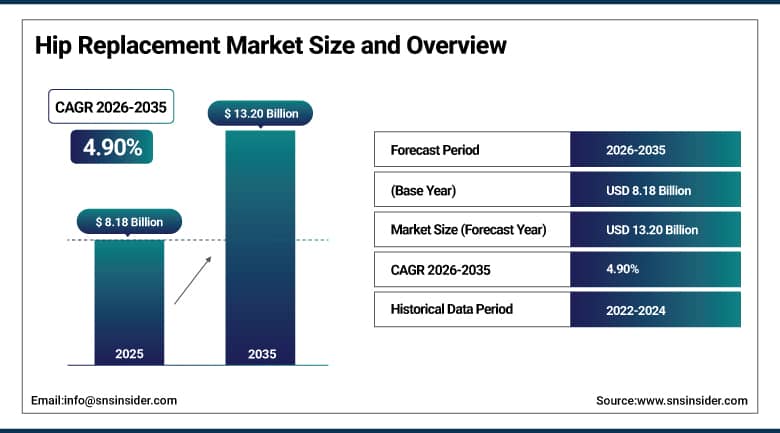
The Hip Replacement Market was valued at USD 8.18 Billion in 2025 and is expected to reach USD 13.20 Billion by 2035, growing at a CAGR of 4.90% from 2026-2035.
The Hip Replacement Market is experiencing growth due to technological advancement, an increase in the number of surgeries, an increase in the elderly population, and the rising prevalence of osteoarthritis across the globe. Total hip arthroplasty or hip replacement surgery involves the replacement of the damaged hip joint by an artificial joint made from materials such as metal, ceramic, and hard plastics in order to relieve pain and enhance mobility for those suffering from severe hip arthritis or any other disease damaging their hip joints. The demand is expected to keep increasing with an aging demographic, increased prevalence of osteoarthritis, and increasing adoption of outpatient protocols for joint replacements. Technological advancements in terms of rapidly adopted robotic systems that help surgeons place components in proper alignment and 3D printed porous implants, which enhance implant longevity through bone ingrowth characteristics, are contributing as key factors behind market growth.
In November 2024, Zimmer Biomet announced plans for the broad commercial launch of its Z1 Femoral Hip System at the annual meeting of the American Association of Hip and Knee Surgeons, a triple-taper femoral system designed to pair with the company's industry-leading G7 Acetabular System to provide surgeons with a versatile, streamlined, and efficient total hip arthroplasty solution. The launch reflects continued innovation investment among established orthopedic device manufacturers as they compete to deliver increasingly integrated, surgeon-friendly implant systems, reinforcing the competitive importance of comprehensive femoral and acetabular product portfolios as manufacturers seek to capture share within an increasingly consolidated global hip replacement market.
To Get More Information On Hip Replacement Market - Request Free Sample Report
Hip Replacement Market Trends
-
Rising adoption of robotic-assisted surgical systems improving component alignment and reproducible surgical outcomes.
-
Growing use of three-dimensional-printed porous implants extending device longevity through optimized bone ingrowth.
-
Expanding shift toward outpatient and ambulatory surgical center protocols displacing traditional inpatient hip replacement care.
-
Increasing demand for personalized and patient-specific hip implants tailored to individual anatomical characteristics.
-
Rising adoption of AI-powered surgical guidance systems enhancing implant positioning precision during hip arthroplasty.
-
Growing focus on antimicrobial implant coatings addressing post-surgical joint infection prevention.
U.S. Hip Replacement Market Outlook
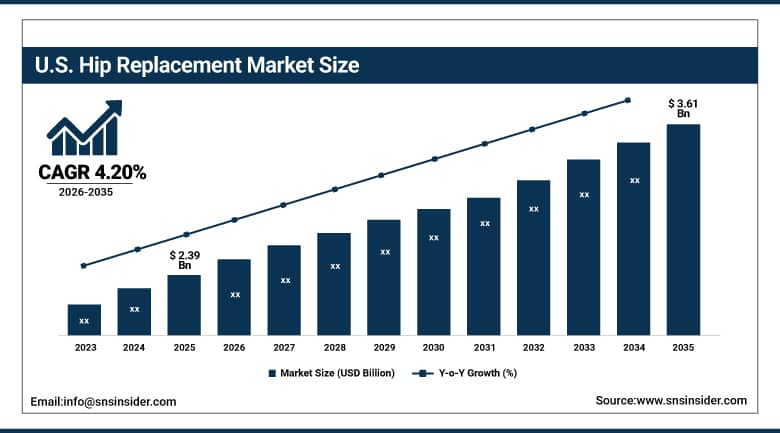
The U.S. Hip Replacement Market was valued at USD 2.39 Billion in 2025 and is expected to reach USD 3.61 Billion by 2035, growing at a CAGR of 4.20% from 2026-2035.
The growth of the U.S. Hip Replacement Market will continue to get further strengthened due to the adoption of robotic surgery systems from all the key players in the industry, and robotic assisted surgeries becoming a norm in the country’s orthopedics practice. The hip replacement implants market is very concentrated with the top three companies namely, Zimmer Biomet, Stryker and Johnson & Johnson DePuy Synthes having 70% of the total market share followed by Smith & Nephew. Positive reimbursement trends and solid healthcare infrastructure will continue to help in driving growth in procedure volumes within the domestic market.
The Stryker Mako robotic surgery platform had already been adopted in about one-third of the hip replacement procedures in the United States in late 2024, with its installed base surpassing 2,000 units across the globe due to the firm's leadership position that emanated from the acquisition of Mako Surgical in late 2013. Stryker's Mako platform has continued to be indicated for total hip, total knee, and partial knee surgeries, showing that the domestic orthopedic device makers have kept penetrating the robotics market through the hip replacement surgery volume.
Hip Replacement Market Segment Analysis
-
By Product Type, the Total Hip Replacement segment dominated the Hip Replacement Market with approximately 62.60% share in 2025, while the Hip Resurfacing segment is the fastest growing with a CAGR of approximately 6.80%.
-
By Material, the Metal segment dominated the Hip Replacement Market with approximately 44.60% share in 2025, while the Ceramic segment is the fastest growing with a CAGR of approximately 5.80%.
-
By Fixation Type, the Cementless segment dominated the Hip Replacement Market with approximately 54.60% share in 2025, while the Hybrid segment is the fastest growing with a CAGR of approximately 5.60%.
-
By End-User, the Hospitals segment dominated the Hip Replacement Market with approximately 58.60% share in 2025, while the Ambulatory Surgical Centers segment is the fastest growing with a CAGR of approximately 7.20%.
By Product Type, Total Hip Replacement Dominates the Hip Replacement Market and Hip Resurfacing Grows Fastest
Total hip replacement is the dominating product type due to the fact that this procedure is still considered the gold-standard treatment of the hip joint damage caused by osteoarthritis and other degenerative diseases, which requires replacement of both parts of the hip joint – femoral head and acetabulum. Effectiveness of this procedure in eliminating pain and restoring mobility and its use for patients of different age groups and with various severity of the disease keep total hip replacement as the most prevalent product type, despite continuous modifications of the technology including implementation of dual-mobility cups in order to reduce the risk of hip dislocation in certain patient groups.
Hip resurfacing is the fastest growing product type because this bone conserving substitute of total hip replacement continues to become more popular among physically active people as they need implants to function well after the surgery, since hip resurfacing is a less invasive surgery than total hip replacement, thus, less bone tissue is removed during the procedure. Higher growth of this segment is also driven by increasing demand among younger physically active people as hip resurfacing allows them to perform physical activities after surgery.
By Material, Metal Dominates the Hip Replacement Market and Ceramic Grows Fastest
Metal dominates the market as metal femoral stems and components continue to represent the most widely used material across hip implant systems, given their proven durability, established manufacturing processes, and extensive long-term clinical outcome data spanning decades of commercial use. The material's structural strength and compatibility with a wide range of fixation techniques and implant designs continues to sustain metal's position as the largest material category, reinforced by continued innovation including antimicrobial coating technology designed to reduce post-surgical infection risk.
Ceramic is the fastest-growing material as ceramic-on-polyethylene and ceramic-on-ceramic bearing surface combinations continue to gain adoption for their superior wear resistance characteristics relative to traditional metal-on-polyethylene combinations, particularly appealing for younger, more active patients requiring long-term implant durability. This growth is reinforced by continued advancement in ceramic material formulations that address historical concerns regarding component fracture risk, positioning ceramic as an increasingly preferred bearing surface choice for patients prioritizing implant longevity over multi-decade timeframes.
By Fixation Type, Cementless Dominates the Hip Replacement Market and Hybrid Grows Fastest
Cementless fixation holds the largest share of the market as this type of fixation, where the bones grow into the porous or textured surface of implants in order to provide long-term stability of implants, has become the modern gold standard method for most hip replacement surgeries due to better results compared to the cemented fixation. Compatibility with three-dimensional-printed porous implants ensures the leading place of cementless fixation as the fixation type with the largest market share, especially for younger active patients with good bone quality.
Hybrid fixation is the fastest growing segment as doctors choose a personalized fixation strategy depending on bone quality of each patient. Growing popularity of hybrid fixation among the orthopedic surgeons treating elderly patients with poor bone quality is one of the factors that drive the growth of this segment, as it combines the mechanical stability provided by cemented femoral fixation and long-term biological stability provided by cementless acetabular fixation.
By End-User, Hospitals Dominates the Hip Replacement Market and Ambulatory Surgical Centers Grows Fastest
Hospitals dominate end-user demand as the majority of hip replacement procedures, particularly those involving more complex cases, revision surgeries, and patients with significant comorbidities, continue to be performed within hospital settings given their comprehensive surgical and post-operative care infrastructure. The scale of hospital-based orthopedic surgery programs, combined with hospitals' established relationships with orthopedic surgeons and implant manufacturers, continues to sustain hospitals' position as the largest end-user category for hip replacement procedures.
Ambulatory surgical centers are the fastest-growing end-user category as widening acceptance of outpatient joint-replacement protocols continues to displace inpatient care for appropriately selected, lower-risk patients. This growth is reinforced by rising surgeon and patient comfort with same-day discharge protocols following advances in minimally invasive surgical technique, anesthesia management, and post-operative pain control, positioning ambulatory surgical centers as an increasingly significant care setting as the industry continues its broader shift toward outpatient joint replacement delivery.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
84.60% |
|
Asia Pacific |
China |
39.60% |
|
Europe |
Germany |
29.60% |
|
Latin America |
Brazil |
27.60% |
|
Middle East & Africa |
United Arab Emirates |
24.60% |
North America Hip Replacement Market Insights
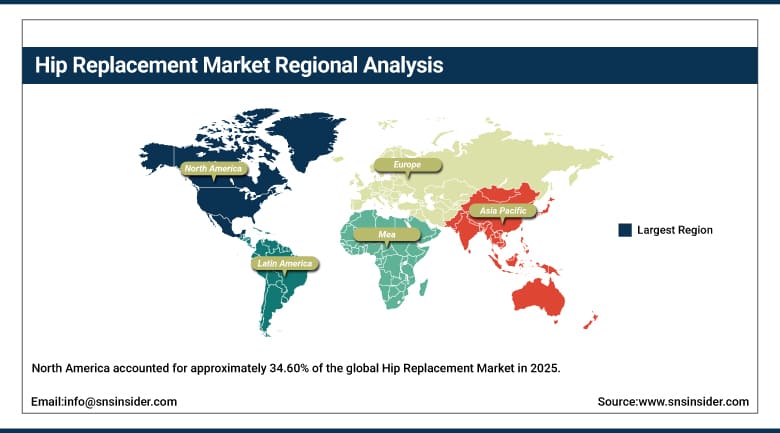
North America accounted for approximately 34.60% of the global Hip Replacement Market in 2025, making it the largest regional market, driven by the rapid adoption of customized hip implants and favorable health reimbursement policies across the region. The United States dominates regional demand, anchored by a highly concentrated competitive landscape led by Zimmer Biomet, Stryker, and DePuy Synthes, alongside well-established healthcare infrastructure and widespread robotic-assisted surgical platform adoption.
Canada is contributing incremental regional demand as its healthcare system continues to expand orthopedic surgical capacity. Continued domestic investment in robotic-assisted surgery and next-generation implant technology is expected to sustain North America's leading position through the forecast period, even as growth in percentage terms moderates relative to faster-expanding emerging markets pursuing rapid healthcare infrastructure development.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Hip Replacement Market Insights
Asia Pacific is the fastest growing regional market, recording an approximate CAGR of 6.60% between 2026 and 2035, as a result of the increasing infrastructure investments in the healthcare industry, high expertise level among orthopedic surgeons, and availability of advanced surgical facilities in China and India. The large and aging population in China has continued to stimulate high demand for hip replacement surgeries, aided by the continued increase in production of orthopedic devices in China.
India has continued to contribute to the incremental growth in the market due to the development of the healthcare industry and orthopedic surgeries in India, aided by the increasing number of patients coming for medical tourism in India and increased accessibility to advanced surgeries by the Indian middle class.
Europe Hip Replacement Market Insights
Europe represents a significant share of the global Hip Replacement Market, anchored by Germany's large healthcare infrastructure and established orthopedic surgical expertise. European healthcare systems continue to support robust hip replacement procedure volumes given the region's aging population demographics and well-developed public healthcare reimbursement frameworks covering orthopedic joint replacement procedures.
The United Kingdom, France, and Italy are contributing steady demand growth as regional healthcare systems continue to extend advanced implant technology adoption across an aging patient population. Regional device manufacturers continue to invest in next-generation implant material and robotic-assisted surgical technology to meet the region's growing demand for improved surgical outcomes and reduced revision rates.
MEA & Latin America Hip Replacement Market Insights
The Middle East & Africa market remains comparatively small but is expanding as growing healthcare infrastructure investment across the United Arab Emirates and Saudi Arabia sustains demand for advanced orthopedic surgical capability. Regional governments continue to invest in expanding specialized orthopedic surgical centers to serve growing domestic demand for hip replacement procedures.
Latin America's market is led by Brazil, where a growing aging population and expanding healthcare infrastructure continue to drive gradual hip replacement market growth. Mexico is contributing growth as regional healthcare access continues to expand. Across the region, adoption remains concentrated among larger urban medical centers with established orthopedic surgical programs.
Market Dynamics
Growth Drivers: Aging Population and Osteoarthritis Prevalence
The increase in elderly population represents the primary driver of Hip Replacement Market growth, as demographic aging trends continue to expand the patient population at elevated risk for degenerative hip joint conditions requiring surgical intervention. Growing prevalence of osteoarthritis, a degenerative disease in which flexible tissues at bone joints get degraded, resulting in severe joint pain, continues to reinforce sustained procedure volume growth across both established and emerging healthcare markets worldwide.
Advancements in technology represent a second major growth driver, as recent innovations, including robotic-assisted surgical systems and three-dimensional-printed porous implants, continue to improve surgical precision and implant longevity. The rise in the number of trauma cases requiring hip replacement, combined with growing demand for personalized hip implants tailored to individual patient anatomy, continues to reinforce sustained market expansion as technological capability continues to advance across the orthopedic device industry.
Restraints: High Implant and Surgery Costs and Regulatory Complexity
The high costs associated with implants and surgeries serve as a significant impediment to the growth of the market, considering the high costs involved in carrying out hip replacement surgeries, such as costs related to implants, fees charged by the surgical center, and rehabilitation costs. The aforementioned cost factor still serves as an impediment to the growth of the volume of such procedures carried out in areas with poor insurance coverage of joint replacements.
Stringent regulatory guidelines represent a further restraint, as hip implant devices must undergo rigorous premarket approval and clinical validation processes across major regulatory jurisdictions before achieving commercial availability, extending development timelines and increasing costs relative to less regulated medical device categories. This regulatory complexity continues to create meaningful barriers to entry for smaller device manufacturers while also constraining the pace at which established manufacturers can introduce next-generation implant technology across different regional markets.
Opportunities: Robotic Surgery Expansion and Personalized Implant Development
Continued expansion of robotic-assisted surgical platform adoption represents a substantial opportunity, as manufacturers that can demonstrate superior surgical precision and reproducible outcomes are positioned to capture increasing procedure volume as robotic-assisted hip replacement continues its transition from early adoption toward standard-of-care status. Manufacturers investing in expanding robotic platform installed base and surgeon training capability are well positioned to capture demand from healthcare systems increasingly prioritizing surgical precision and reduced revision rates.
The continued growing demand for personalized hip implants offers a further avenue for growth, as patient-specific implant design, enabled by advanced imaging and three-dimensional printing technology, continues to improve implant fit and long-term functional outcomes relative to standardized off-the-shelf implant systems. Manufacturers that can develop cost-competitive personalized implant manufacturing capability are well positioned to capture demand from surgeons and patients increasingly seeking anatomically optimized surgical solutions.
Recent Developments:
-
In November 2024, Zimmer Biomet completed the acquisition of OrthoGrid Systems Inc., adding the company's AI-powered fluoroscopy-based Hip AI surgical assistance product and over 40 patents to its total hip replacement portfolio.
-
In October 2025, Zimmer Biomet received FDA breakthrough device designation for an iodine-treated total hip replacement system designed to prevent post-surgical joint infections, following approval for the device in Japan in September 2025.
-
Smith & Nephew's CORI surgical system, launched for total hip implants in early 2022, expanded its installed base to more than 1,000 systems globally by year-end 2024.
Hip Replacement Market Key Players
-
Zimmer Biomet Holdings, Inc.
-
DePuy Synthes (Johnson & Johnson MedTech)
-
Stryker Corporation
-
Smith & Nephew plc
-
MicroPort Scientific Corporation
-
B. Braun SE
-
Medacta International SA
-
Corin Group
-
Exactech, Inc.
-
Enovis Corporation
-
Aesculap, Inc.
-
Conformis, Inc.
-
Waldemar Link GmbH & Co. KG
-
Amplitude Surgical
-
MatOrtho Limited
-
CeramTec GmbH
-
Meril Life Sciences Pvt. Ltd.
-
United Orthopedic Corporation
-
OrthoGrid Systems Inc. (Zimmer Biomet)
-
Aditya Hip
Hip Replacement Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 8.18 Billion |
| Market Size by 2035 | USD 13.20 Billion |
| CAGR | CAGR of 4.90% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (Total Hip Replacement, Partial Hip Replacement, Hip Resurfacing, Revision) • By Material (Metal, Ceramic, Polyethylene, Composites) • By Fixation Type (Cemented, Cementless, Hybrid) • By End-User (Hospitals, Ambulatory Surgical Centers, Orthopedic Clinics) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Zimmer Biomet Holdings, Inc., DePuy Synthes (Johnson & Johnson MedTech), Stryker Corporation, Smith & Nephew plc, MicroPort Scientific Corporation, B. Braun SE, Medacta International SA, Corin Group, Exactech, Inc., Enovis Corporation, Aesculap, Inc., Conformis, Inc., Waldemar Link GmbH & Co. KG, Amplitude Surgical, MatOrtho Limited, CeramTec GmbH, Meril Life Sciences Pvt. Ltd., United Orthopedic Corporation, OrthoGrid Systems Inc. (Zimmer Biomet), Aditya Hip |
Frequently Asked Questions
Key players include Zimmer Biomet Holdings, Inc., DePuy Synthes, Stryker Corporation, Smith & Nephew plc, MicroPort Scientific Corporation, and B. Braun SE, among other global orthopedic device manufacturers.
Continued expansion of robotic-assisted surgical platform adoption and continued growing demand for personalized hip implants represent the primary opportunities.
Growth is primarily driven by the increase in elderly population combined with advancements in technology, including robotic-assisted surgical systems and three-dimensional-printed implants.
By Product Type, Total Hip Replacement dominated the market with approximately 62.60% share in 2025, reflecting its status as the gold-standard surgical intervention for severe hip joint damage.
North America dominated the market with approximately 34.60% share in 2025, driven by rapid adoption of customized hip implants and favorable health reimbursement policies.
