
Knee Replacement Market Report Scope & Overview:
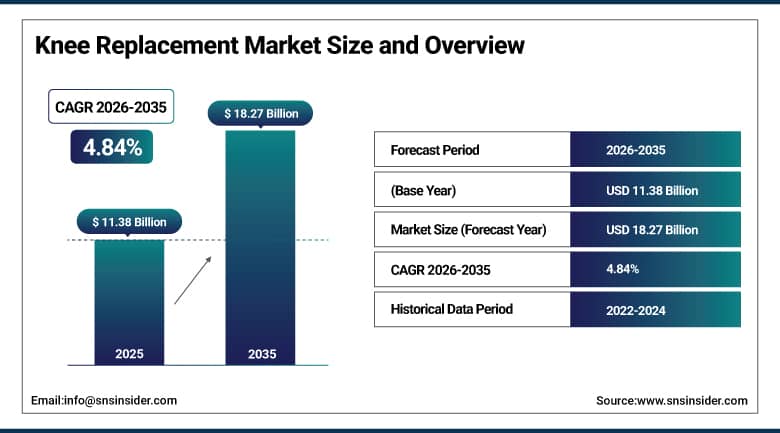
The Knee Replacement Market was valued at USD 11.38 Billion in 2025 and is expected to reach USD 18.27 Billion by 2035, growing at a CAGR of 4.84% from 2026-2035.
The Knee Replacement Market is expanding as osteoarthritis rises and populations age. More patients now seek surgery to regain mobility and stay active. Total knee replacement remains the main procedure and accounts for most implant sales. Robotic systems, patient-specific implants and cementless designs are changing surgical practice. Procedures are also moving from hospitals to ambulatory surgical centers. Price controls in several countries and recall risk limit revenue growth for implant makers. Surgeon shortages and long waiting lists affect access in many health systems. The market is expected to grow as demand for joint surgery rises in both mature and emerging economies.
⮞In October 2025, the American Joint Replacement Registry of the American Academy of Orthopaedic Surgeons reported more than 4.4 million hip and knee arthroplasties recorded from 2012 to 2024. The registry figure shows the scale of joint replacement activity in the U.S.
To Get More Information On Knee Replacement Market - Request Free Sample Report
Knee Replacement Market Trends:
-
Rapid adoption of robotic-assisted systems for total and partial knee surgery
-
Shift of knee procedures to ambulatory surgical centers
-
Growth of patient-specific and cementless implant designs
-
Price controls and volume-based procurement in China and India
-
Portfolio changes through acquisitions and separations among large orthopedic companies
U.S. Knee Replacement Market Outlook:
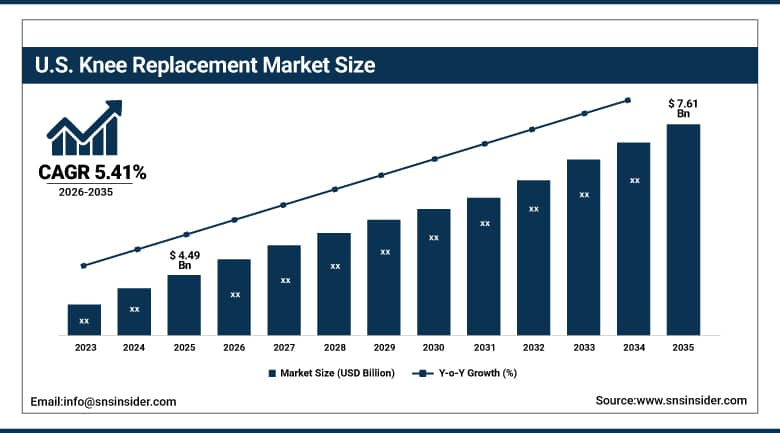
The U.S. Knee Replacement Market was valued at USD 4.49 Billion in 2025 and is expected to reach USD 7.61 Billion by 2035, growing at a CAGR of 5.41% from 2026-2035.
The U.S. Knee Replacement Market is the largest national market and benefits from a large elderly population and broad insurance coverage. Medicare covers a high share of procedures, so payment rules strongly influence volumes and device prices. Obesity and sports injuries increase the number of younger patients seeking surgery. Robotic platforms are spreading quickly across hospitals and surgery centers. Outpatient knee surgery is growing as payers favor lower cost sites. Implant makers face pressure from hospital price negotiations and recall liability. Tariff policy on imported devices adds sourcing uncertainty. Demand is therefore expected to rise with an aging population and new surgical technology.
⮞In August 2026, Zimmer Biomet reported second quarter U.S. knee sales of USD 455.00 million, up 1.4% from the prior year. The result shows steady procedure demand in the U.S. despite pricing pressure.
Knee Replacement Market Segment Analysis:
-
By Product Type, the Total Knee Replacement segment dominated the Knee Replacement Market with approximately 68.87% share in 2025, while the Revision Knee Replacement segment is the fastest growing with a CAGR of approximately 6.44%.
-
By Implant Type, the Fixed-Bearing Implants segment dominated the Knee Replacement Market with approximately 58.10% share in 2025, while the Mobile-Bearing Implants segment is the fastest growing with a CAGR of approximately 6.74%.
-
By Surgical Technology, the Manual Surgery segment dominated the Knee Replacement Market with approximately 72.64% share in 2025, while the Robotic-Assisted Surgery segment is the fastest growing with a CAGR of approximately 10.17%.
-
By End User, the Hospitals segment dominated the Knee Replacement Market with approximately 67.40% share in 2025, while the Ambulatory Surgical Centers segment is the fastest growing with a CAGR of approximately 6.90%.
By Product Type, Total Knee Replacement Dominates the Knee Replacement Market and Revision Knee Replacement Grows Fastest
Total knee replacement leads because it is the standard treatment for advanced osteoarthritis that involves more than one compartment of the joint. Surgeons have decades of outcome data, and implant designs are well established across brands. Payers cover the procedure widely, and patients report strong pain relief and improved mobility. Hospitals also have the training, instruments and rehabilitation programs needed to run high volumes. These advantages keep total knee systems at the center of sales for the largest orthopedic companies and support steady unit growth in every region. Strong registry evidence and familiar instruments also lower training needs for new surgeons, which helps manufacturers sell total knee systems in both mature and emerging markets.
Revision knee replacement is growing fastest because the first generation of younger primary patients is now living long enough to need a second operation. Infection, loosening and wear drive revision cases, and complex revisions need specialized implants with stems, wedges and constrained designs. Surgeons also refer difficult cases to high volume centers, which concentrates demand. Higher revision rates among obese and younger patients add to the trend. Because revision systems carry higher prices than primary implants, growth in this segment raises revenue faster than procedure counts alone. Specialist centers in the United States and Europe are building dedicated revision programs, and implant makers support them with trial instruments, augments and surgeon education.
⮞In April 2025, restor3d received FDA 510(k) clearance for the iTotal Identity CR 3DP Porous total knee system, the first cementless option in its patient-specific line. The clearance shows continued innovation in primary total knee systems.
By Implant Type, Fixed-Bearing Implants Dominates the Knee Replacement Market and Mobile-Bearing Implants Grows Fastest
The fixed-bearing implants dominate because the polyethylene insert is fixed to the tibial tray, thus providing reliable stability and ease of implantation. Fixed-bearing implants have been used by the majority of surgeons and possess proven durability according to long-standing registries. In addition, there are multiple vendors offering fixed-bearing knee implants; such designs are compatible with surgical robotic planning. For hospitals, it provides the advantage of standardizing instruments and simplifying inventory management. Thus, these factors make fixed-bearing knee implants the default choice for primary operations and secure the dominance of fixed-bearing knee implants even with growing popularity of alternatives.
The mobile-bearing implants demonstrate the most significant growth rate due to the fact that the rotating insert in this type of design may help to reduce wear and increase natural mobility in younger and more active patients. In certain cases, doctors prefer mobile-bearing implants because they prolong the life of an artificial joint and minimize the probability of revision. Recent design innovations solved problems with potential dislocation of the bearing and high sensitivity to the technique.
⮞In September 2025, United Orthopedic received FDA 510(k) clearance for a stem extension line within its U2 Total Knee System. The clearance shows continued expansion of implant ranges.
By Surgical Technology, Manual Surgery Dominates the Knee Replacement Market and Robotic-Assisted Surgery Grows Fastest
Manual surgery leads because most hospitals still perform knee replacements with conventional instruments and mechanical alignment guides. The approach needs lower capital investment and is familiar to surgeons in every country. In many emerging markets and smaller hospitals, robots are too costly or lack trained staff. Outcomes with manual technique are well documented and acceptable to payers. As a result, conventional instrument sets continue to generate the majority of procedures, even though surgical centers are adding technology and the gap is narrowing each year. Capital budgets, surgeon preference and the lack of strong evidence on long-term survival also slow replacement of manual methods in public hospitals.
Robotic-assisted surgery is growing fastest because it improves implant positioning and supports personalized alignment plans. Hospitals use robots to attract surgeons and patients and to differentiate their orthopedic services. Companies are launching compact and lower cost systems that fit ambulatory surgical centers. Software updates, data analytics and open platforms that support several implant brands also widen adoption. Early evidence suggests fewer outliers and more consistent soft tissue balancing, which encourages investment. The installed base of robots is expected to keep rising as procedure volumes shift to technology-enabled care. Hospitals that adopt robots often report higher case volumes, and suppliers bundle disposable tracking arrays and software licenses that create recurring revenue per procedure.
⮞In May 2026, THINK Surgical announced that its TMINI miniature robotic system had reached its 5,000th total knee case, one year after the 1,000th. The milestone shows rapid adoption of compact robotic platforms.
By End User, Hospitals Dominates the Knee Replacement Market and Ambulatory Surgical Centers Grows Fastest
Hospitals lead because they perform most knee replacements, especially complex, revision and high risk cases that need inpatient support. They have operating rooms, anesthesia teams, implant inventories and rehabilitation services in one place. Many payers still favor hospital settings for older patients with several health conditions. Large systems also purchase robots and negotiate volume contracts with implant suppliers. These strengths keep hospitals at the center of the market, although payment policy and patient preference are slowly moving suitable cases toward outpatient settings. They also manage complications such as infection and stiffness, which require readmission and specialist care that surgery centers are not designed to provide.
Ambulatory surgical centers are growing fastest because payers and patients prefer lower cost settings for healthy, motivated patients. Faster recovery protocols, regional anesthesia and improved pain control allow same-day discharge. Centers are installing robotic systems to compete with hospitals and attract surgeons. Medicare has also widened the list of procedures covered in these centers. Implant companies are creating streamlined instrument sets and training programs for outpatient teams, and operators of surgery center networks report strong joint replacement growth as capacity expands. Standard surgical checklists, preoperative education and home physical therapy programs increase the share of patients who qualify for outpatient surgery each year.
⮞In November 2025, the U.S. Centers for Medicare and Medicaid Services finalized its calendar year 2026 outpatient rule, which adds 289 procedures to the ambulatory surgical center covered list. The change expands the range of musculoskeletal surgery that can move to outpatient sites.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
U.S. |
89.44 |
|
Europe |
Germany |
28.40 |
|
Asia Pacific |
China |
34.20 |
|
Latin America |
Brazil |
62.50 |
|
Middle East & Africa |
Saudi Arabia |
31.80 |
North America Knee Replacement Market Insights
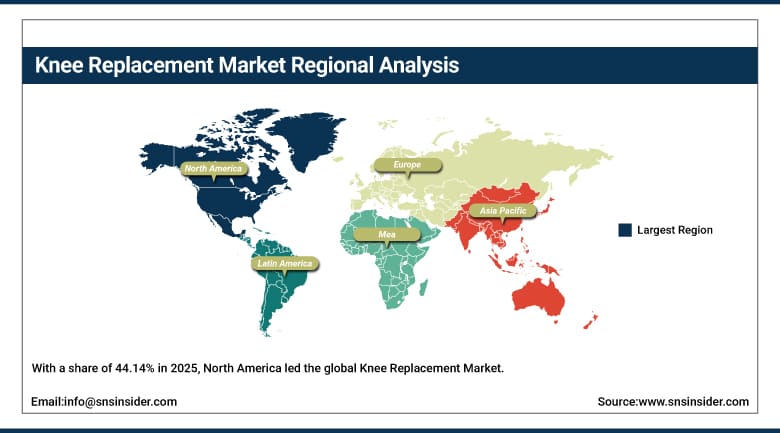
With a share of 44.14% in 2025, North America led the global Knee Replacement Market. The United States accounts for most regional demand because of its aging population, high rates of obesity and widespread insurance coverage. Canada contributes through publicly funded hip and knee programs that aim to reduce waiting times. Stryker, Zimmer Biomet, DePuy Synthes, Smith+Nephew, Enovis, restor3d and Ortho Development operate in the region, and competition among them is intense. Hospitals and surgery centers adopt new technology quickly. Large academic centers and private orthopedic groups also run clinical studies that shape device adoption and give the region early access to new designs.
Robotic surgery is a defining feature of the regional market. Hospitals and surgery center operators are installing systems from several suppliers, and surgeons increasingly expect access to planning software. Outpatient migration continues as Medicare widens covered sites and payers reward lower cost care. At the same time, buyers push for lower prices, and trade policy raises sourcing uncertainty for devices made abroad. Recalls and legal claims create financial risk for suppliers, as shown by recent restructuring among smaller implant makers. Skilled orthopedic surgeons are concentrated in metropolitan areas, so rural patients may travel long distances for surgery, and tele-rehabilitation is helping to close this gap.
⮞In April 2026, Tenet Healthcare said its USPI ambulatory surgery unit added about 150 robotic surgery programs in the first quarter. The addition shows how outpatient operators are building joint replacement capacity.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Knee Replacement Market Insights
Europe is the second largest region and is led by Germany, the United Kingdom, France, Italy and Spain. National registries track outcomes closely, which helps hospitals compare implants and encourages evidence-based purchasing. Aging populations support steady demand, although public budgets and tender processes limit price growth. Companies such as Medacta, Waldemar Link and Smith+Nephew maintain strong positions, and regional makers benefit from close relations with surgeons. Germany holds the highest procedure volumes and a well-developed network of specialist orthopedic clinics. Switzerland and Italy add strong manufacturing and surgical expertise, and a number of regional companies export implants and instruments to other markets.
The European Medical Device Regulation has raised the cost of clinical evidence and certification, and some small manufacturers have withdrawn products. Waiting lists in several public systems remain long, which pushes patients toward private clinics and cross-border care. Robotic systems are spreading more slowly than in the United States because of capital costs and tender rules. Tariff announcements on exports to the United States affect European makers that rely on American sales, and some are reviewing manufacturing locations. Public hospitals increasingly demand outcome data and long warranties from suppliers, which gives companies with strong registry records an advantage in tenders.
⮞In October 2025, the German Arthroplasty Registry reported 173,252 primary knee implantations for 2024. The figure shows the volume of knee surgery in the largest European market.
Asia Pacific Knee Replacement Market Insights
Asia Pacific is projected to be the fastest growing region, with a CAGR of 9.37% during 2026-2035. China, Japan, India, South Korea and Australia lead regional demand. Rapid aging in Japan and China, rising incomes and improved insurance coverage increase the number of patients who can pay for surgery. India has a very large population with knee disease and a growing private hospital sector. Local manufacturers are gaining share, and global companies are expanding training and service networks across the region. Australia and South Korea contribute high procedure rates per capita, and strong clinical research programs encourage the early uptake of advanced implants and navigation tools.
Government pricing policy strongly shapes the market. China's national volume-based procurement programs have cut knee implant prices sharply, which increases patient access but squeezes supplier margins. India has capped knee implant prices and extended the limits, which favors local manufacturers with lower cost structures. Domestic robotic systems are being introduced at lower prices than imported platforms. Medical tourism in Thailand, India and Singapore adds further demand for high quality joint replacement at competitive prices. Training programs sponsored by manufacturers help improve surgeon skills in fast growing markets, and partnerships with local distributors extend reach into secondary cities.
⮞In January 2025, China Daily reported that the average price of an artificial knee in China's national joint procurement fell from 32,000 yuan to 5,000 yuan. The decline shows the scale of price pressure on implant suppliers in the region.
MEA & Latin America Knee Replacement Market Insights
The Latin American markets include Brazil, the largest, Mexico, Argentina, and Colombia. Public health care has long waiting lists for knee replacement surgeries while private hospitals treat insured patients paying for modern implant devices. In Mexico, there are already developed large-scale surgical programs in the public sector aimed at reducing the waiting list. The currency fluctuations and dependence on imported devices affect the prices, while tenders focus on cost factors. International companies rely on distributors and training programs for the establishment of surgeon networks. In addition, private hospitals are investing in orthopedic centers while regional medical tourism is driving the demand for modern implants and surgical technologies.
In the Middle East and Africa regions, Saudi Arabia and the United Arab Emirates are leading the demand due to investments into specialty hospitals and medical tourism in the national health programs. Private hospitals in the Gulf area are already offering robotic knee surgery and drawing patients from the region. South Africa has developed orthopedic industry while other countries of Africa have poor surgical capabilities. Growth drivers include obesity and diabetes, while the main barriers to adoption are the high device price and lack of trained surgeons in low-income countries.
⮞In January 2025, Almoosa Specialist Hospital in Saudi Arabia reported 300 robotic knee replacements, which it described as the highest number in the Kingdom. The figure shows growing adoption of robotic techniques in the Gulf.
Market Dynamics:
Growth Drivers: Osteoarthritis Burden and Technology Adoption
Rising osteoarthritis is the main driver of the market. Knee joints are the most commonly affected site, and prevalence increases with age, obesity and prior injury. As people live longer and stay active, more of them seek surgery to relieve pain and restore movement. Health systems in developed and emerging economies are expanding capacity to manage these patients. The pool of candidates for replacement is large and growing, which supports steady procedure volumes and implant demand throughout the forecast period. Rising rates of obesity and diabetes increase joint stress and complicate care, which raises the number of younger patients who reach surgery earlier than in past decades.
Technology adoption strengthens growth. Robotic platforms, patient-specific implants, advanced bearing materials and digital planning tools improve outcomes and attract surgeons and patients. Hospitals use these tools to compete and to build high volume joint programs. Faster recovery protocols and outpatient pathways lower the cost per case and open surgery to more patients. Reimbursement support in several countries and rising disposable income in Asia further widen access. Together these factors lift demand for higher value systems and services. Awareness campaigns and better diagnostic imaging also bring more patients into treatment pathways, and employers and insurers increasingly view joint replacement as a way to restore work capacity.
⮞In July 2023, the World Health Organization reported that about 528 million people had osteoarthritis in 2019, with the knee the most common site at 365 million cases. The figure shows the large patient base behind knee replacement demand.
Restraints: Cost Pressure, Recalls and Limited Surgical Capacity
Cost constraints form another significant barrier. Reimbursement cuts and price caps on implants are being implemented by the payers and governments as evidenced in China and India. Hospitals become more aggressive in negotiating prices while group purchasing organizations ask for discounts. Patients with inadequate coverage delay surgeries. The high capital cost of robotic systems combined with servicing costs becomes too expensive for smaller hospitals. This constraint lowers the profitability of smaller manufacturers due to the reduced revenue per procedure. Interruptions within supply chain and tariffs on imported components can increase cost and affect deliveries of implants and instruments to hospitals.
Another risk is the possibility of implant defect leading to recalls and revision cases. Defects result in recalls, revisions, lawsuits that harm company reputation and force the company to restructure its operations. Approval process is taking much longer than before in some parts of the world. Stricter regulatory standards and restrictions are being set. Insufficient number of orthopedic surgeons and operation theater personnel reduces the number of operations performed in most of public health systems. Long wait lists and poor access to rehabilitation services slow down growth in lower and middle income countries.
⮞In September 2025, Exactech received court approval for the sale of its assets to an investor group as part of its restructuring. The case shows the financial risk that product issues can create for implant makers.
Opportunities: Low-Cost Robotics and Outpatient Joint Programs
Low-cost robotics offers a significant opportunity. Domestic and regional manufacturers are launching knee robots that cost far less than established platforms, which brings technology to hospitals in India, Southeast Asia and Latin America. Lower prices widen the buyer base beyond large academic centers. Implant companies can pair robots with implant sales and training services, creating recurring revenue. Open platforms that work with several implant brands also give hospitals flexibility and lower the barrier to adoption. Data from robotic procedures can feed predictive models that guide implant selection and recovery planning, adding value beyond the device itself.
Outpatient joint programs are a second opportunity. As payers favor lower cost sites, surgery center operators are building dedicated joint replacement lines. Suppliers that provide compact instrument sets, remote monitoring and recovery programs can win these customers. Younger and more active patients also create demand for personalized and cementless implants. Emerging markets with growing insurance coverage and medical tourism provide additional growth, particularly for companies that adapt pricing and training to local needs. Companies that localize production and training in India, China and Brazil can lower prices without loss of quality and reach patients who currently rely on conservative treatment.
⮞In November 2024, Meril introduced its MISSO knee robot in India and said the system requires about 66% less investment than imported robotic systems. The claim shows the push toward lower cost surgical robotics.
Recent Developments:
-
In July 2026, Stryker began the full U.S. launch of its Mako RPS handheld robotic system for total knee replacement. The Mako platform has supported more than 2.5 million procedures, and the new system extends robotic access to more hospitals and surgery centers.
-
In October 2025, Johnson & Johnson announced plans to separate its DePuy Synthes orthopedics business from the rest of the company. The business includes the ATTUNE knee and VELYS robotic platforms, and the separation is targeted for the next two years.
-
In August 2026, Smith+Nephew reported the first knee and shoulder cases with its CORI XT robotic system. The system builds on the CORI platform and aims to widen access to robotic surgery for hospitals and surgery centers.
-
In December 2025, MicroPort Orthopedics launched its SkyWalker robotic system in India, with a first procedure at a hospital in Hyderabad. The system pairs with the NitrX Evolution implant and expands the company's presence in Asia.
Knee Replacement Market Key Players:
-
Stryker Corporation
-
Zimmer Biomet Holdings, Inc.
-
Johnson & Johnson MedTech (DePuy Synthes)
-
Smith+Nephew plc
-
Medacta International SA
-
MicroPort Orthopedics Inc.
-
Enovis Corporation (LimaCorporate)
-
restor3d, Inc.
-
Exactech, Inc.
-
Meril Life Sciences Pvt. Ltd.
-
United Orthopedic Corporation
-
Waldemar Link GmbH & Co. KG
-
Ortho Development Corporation
Knee Replacement Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 11.38 Billion |
| Market Size by 2035 | USD 18.27 Billion |
| CAGR | CAGR of 4.84% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (Total Knee Replacement, Partial Knee Replacement, Revision Knee Replacement, and Patellofemoral Replacement) • By Implant Type (Fixed-Bearing Implants and Mobile-Bearing Implants) • By Surgical Technology (Manual Surgery, Robotic-Assisted Surgery, and Patient-Specific Instrumentation) • By End User (Hospitals, Ambulatory Surgical Centers, and Specialty Orthopedic Clinics) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Stryker Corporation, Zimmer Biomet Holdings, Inc., Johnson & Johnson MedTech (DePuy Synthes), Smith+Nephew plc, Medacta International SA, MicroPort Orthopedics Inc., Enovis Corporation (LimaCorporate), restor3d, Inc., Exactech, Inc., Meril Life Sciences Pvt. Ltd., United Orthopedic Corporation, Waldemar Link GmbH & Co. KG, Ortho Development Corporation |

Frequently Asked Questions
Key opportunities include low-cost robotic systems, outpatient joint replacement programs, patient-specific and cementless implants, and expansion in emerging markets.
Key players include Stryker, Zimmer Biomet, Johnson & Johnson MedTech (DePuy Synthes), Smith+Nephew, Medacta, MicroPort Orthopedics, Enovis (Lima), restor3d, Exactech, Meril, United Orthopedic, Waldemar Link and Ortho Development.
Rising osteoarthritis, population aging and the adoption of robotic and patient-specific technology are the main growth factors.
By Product Type, the Total Knee Replacement segment dominated the market in 2025 with an estimated 68.87% share, supported by its role as the standard treatment for advanced osteoarthritis.
North America dominated the market with a share of 44.14% in 2025, driven by an aging population, broad insurance coverage and fast adoption of new technology.
