
Lab-Grown Diamonds Market Report Scope & Overview:
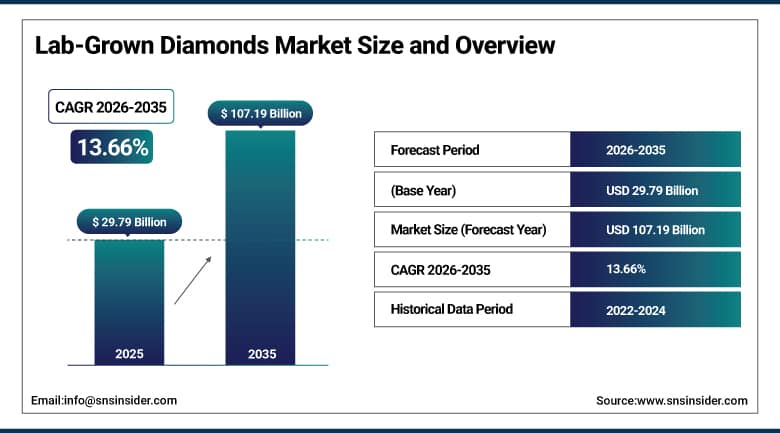
The Lab-Grown Diamonds Market was valued at USD 29.79 Billion in 2025 and is expected to reach USD 107.19 Billion by 2035, growing at a CAGR of 13.66% from 2026-2035.
The Lab-Grown Diamonds Market is witnessing significant growth due to the growing preference for more affordable and sustainable options as compared to natural diamonds. The growing concerns regarding the environmental impact and social implications of diamond mining have encouraged consumers to opt for lab-grown diamonds in their jewelry and fashion applications. Advances in CVD and HPHT technologies are improving the quality and consistency of diamonds as well as providing better scalability in the manufacturing process. Moreover, decreasing costs of production and greater availability in retail stores are contributing to market growth. Adoption in industrial applications such as cutting, drilling, electronics, and heat dissipation is also fueling market growth.
⮞The Kimberley Process reported in July 2026 that global rough diamond output slipped nearly 8% in 2025. The contraction in mined supply strengthens the case for lab-grown stones among jewelers seeking dependable volumes.
To Get More Information On Lab-Grown Diamonds Market - Request Free Sample Report
Lab-Grown Diamonds Market Trends
-
Steep wholesale price deflation is moving lab-grown stones toward everyday jewelry price points.
-
Bridal buyers are shifting to lab-grown center stones in heavier carat weights.
-
Diamond wafers are gaining traction in semiconductor, power electronics and thermal management designs.
-
Chinese and Indian producers are expanding polished output, cutting capacity and export networks.
-
Terminology debates, independent grading and online ring configurators are reshaping how stones are marketed.
U.S. Lab-Grown Diamonds Market Outlook
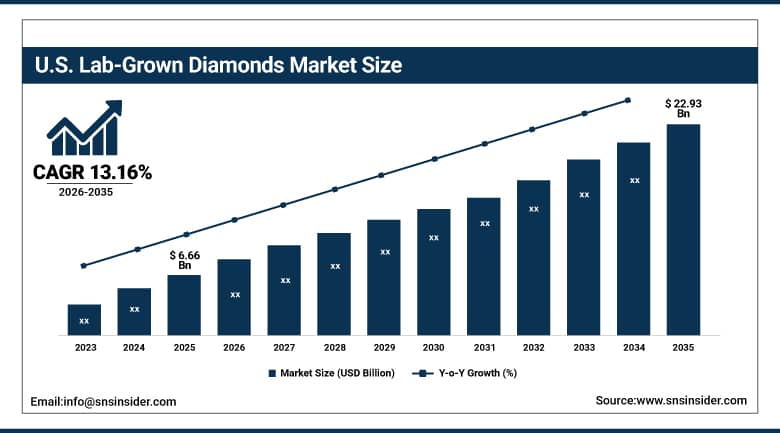
The U.S. Lab-Grown Diamonds Market was valued at USD 6.66 Billion in 2025 and is expected to reach USD 22.93 Billion by 2035, growing at a CAGR of 13.16% from 2026-2035.
The U.S. Lab-Grown Diamonds Market is shaped by a fashion sector that has embraced lab-grown center stones at scale. Couples trade up to larger carat weights at lower price points. Retailers are building dedicated collections backed by independent grading reports. Industrial buyers use synthetic crystals in abrasives, cutting tools and optical windows. Technology firms are evaluating diamond heat spreaders for power electronics and laser systems. Customs treatment and tariff changes continue to influence sourcing decisions. Online configurators are shortening the path from design to delivery. These conditions make the United States a bellwether for pricing, consumer acceptance and product innovation.
⮞The Knot Worldwide reported in February 2026 that lab-grown center stones accounted for 61% of all engagement ring purchases among surveyed U.S. couples. The finding confirms that bridal demand anchors consumption across the country.
Lab-Grown Diamonds Market Segment Analysis
-
By Method, the High Pressure High Temperature (HPHT) segment dominated the Lab-Grown Diamonds Market with approximately 57.77% share in 2025, while the Chemical Vapor Deposition (CVD) segment is the fastest growing with a CAGR of approximately 14.76%.
-
By Size, the Up to 2 Carats segment dominated the Lab-Grown Diamonds Market with approximately 63.72% share in 2025, while the Above 4 Carats segment is the fastest growing with a CAGR of approximately 15.66%.
-
By Application, the Fashion segment dominated the Lab-Grown Diamonds Market with approximately 72.50% share in 2025, while the Industrial segment is the fastest growing with a CAGR of approximately 14.86%.
-
By Distribution Channel, the Specialty Jewelry Stores segment dominated the Lab-Grown Diamonds Market with approximately 39.50% share in 2025, while the Online Retail segment is the fastest growing with a CAGR of approximately 15.96%.
By Method, High Pressure High Temperature (HPHT) Dominates Lab-Grown Diamonds Market; Chemical Vapor Deposition (CVD) to Register Fastest Growth.
High pressure high temperature growth leads because the process is cost-effective, repeatable and suited to large-scale manufacturing. Presses deliver consistent batches of strong crystals with uniform physical and optical properties, which lowers the cost per stone for jewelers and tool makers. Established clusters in China focus on abrasives and mid-clarity gemstones, where volume and price outweigh premium clarity. Mature equipment and accumulated operating know-how keep this route the default choice for bulk producers serving both gem and industrial buyers.
Chemical vapor deposition is advancing fastest because it gives tight control over purity and crystal quality. Reactors scale to produce high-clarity and large stones, which supports premium engagement rings and statement pieces. The same control yields high-purity wafers for radio frequency filters and quantum sensors, opening demand well beyond jewelry. Lower energy use, smaller equipment footprints and close oversight of growth chemistry also draw new entrants and encourage steady capacity additions across several producing regions and downstream end markets.
⮞Reuters reported in October 2026 that Henan Province accounts for about 80% of China's lab-grown diamond output. Such concentration of presses and reactors in one province supports the scale economics behind high-volume production.
By Size, Up to 2 Carats Dominate Lab-Grown Diamonds Market; Above 4 Carats to Register Fastest Growth.
Up to 2 carats lead because they sell at affordable prices and are easier for jewelers to produce, stock and sell. The 1 to 2 carat range matches the most popular engagement and wedding purchases, and it also suits everyday earrings and pendants. Millennial and Gen Z shoppers value affordability, ethical sourcing and sustainability, and this weight band lets them satisfy all three priorities without stretching a household budget or compromising on sparkle, cut quality or certification.
above 4 carats are growing fastest as CVD reactors make large, high-clarity crystals commercially possible. Consumers want sizeable stones at prices well below mined equivalents, which favors statement jewelry, oversized engagement rings and bespoke luxury pieces. Rising disposable income among affluent buyers supports this trading-up behavior, and custom design services let jewelers capture premium margins on commissioned pieces. Lab-grown pricing also lets shoppers choose a heavier stone for the same budget, a trade-off that mined diamonds rarely allow.
⮞In September 2026, 36Kr reported that Power Diamond had grown a single lab-grown crystal of 247.82 carats, described as a record. Progress in large single-crystal growth underpins the move toward heavier stones.
By Application, Fashion Dominates Lab-Grown Diamonds Market; Industrial to Register Fastest Growth.
The Fashion segment dominates the Lab-Grown Diamonds Market due to extensive utilization of lab-grown gemstones in engagement rings, necklaces, earrings, bracelets, and other jewelry products. Increasing consumer preference for affordable and ethically sourced diamond alternatives is encouraging adoption across fashion and luxury jewelry categories. Their comparable physical, chemical, and optical properties to natural diamonds further strengthen consumer acceptance. Additionally, growing product availability through established jewelry brands, independent designers, and online retailers is expanding accessibility and supporting demand across global fashion markets.
Industrial use is expanding fastest because the exceptional hardness of diamond suits cutting, grinding and drilling tools. Tools wear out, so replacement demand is recurring and high in volume. Growth is reinforced by electronics, semiconductors, optics, medical devices and precision engineering. These fields need consistent crystal structure and dependable thermal performance, which engineered material delivers more reliably than mined stones. Reactor-grown crystals can also be shaped to exact specifications, a feature tool makers and chip designers value highly.
⮞The U.S. Geological Survey reported in February 2026 that about 97% of U.S. industrial diamond apparent consumption was synthetic. The figure shows how thoroughly engineered material has displaced mined stones in technical uses.
By Distribution Channel, Specialty Jewelry Stores Dominate Lab-Grown Diamonds Market; Online Retail to Register Fastest Growth.
Specialty jewelry stores lead because high-value diamond purchases still call for in-store verification and personal consultation. Shoppers inspect stones under magnification and compare certified options with trained staff before committing to a ring. Branded chains reinforce trust by curating lab-grown collections and by offering aftercare, resizing and upgrade programs, services that online sellers find harder to match at the same level of confidence. Store visits also support custom design work, resizing appointments and later upgrades of the original stone.
Online retail is rising fastest as digital shopping becomes routine for high-ticket jewelry. Competitive pricing, wider selection and side-by-side comparison tools let buyers evaluate hundreds of certified stones within minutes. Custom ring configurators allow customers to choose the stone, cut and setting. Transparent grading reports reduce the hesitation once linked to buying a diamond without seeing it in person or visiting a showroom. Free returns and virtual consultations further lower the barrier for first-time buyers and younger shoppers.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
34.87% |
|
North America |
United States |
76.50% |
|
Europe |
Germany |
20.22% |
|
Middle East & Africa |
United Arab Emirates |
27.82% |
|
Latin America |
Brazil |
42.00% |
Asia Pacific Lab-Grown Diamonds Market Insights
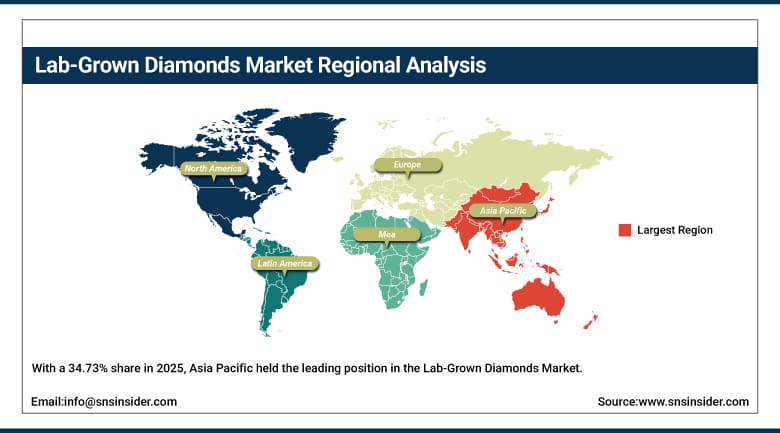
With a 34.73% share in 2025, Asia Pacific held the leading position in the Lab-Grown Diamonds Market. China anchors regional supply through dense clusters of growth presses and CVD reactors, while India has built a large cutting and polishing industry that converts rough crystals into certified stones for export. Japan contributes precision single-crystal technology aimed at electronics and optics. Lower manufacturing costs, deep technical labor pools and proximity to jewelry manufacturers keep the region at the center of global production and trade. Smaller producers across Southeast Asia are beginning to add capacity.
Looking ahead, the region is projected to record the fastest growth in the market, advancing at a CAGR of 14.76% from 2026 to 2035. Rising disposable incomes in urban China and India are building a local jewelry customer base that did not exist at scale a decade ago. Producers are also shifting toward functional diamond for thermal management and semiconductor uses, which widens the addressable market beyond gemstones. Export-oriented polishing hubs and expanding online retail add further momentum. Government support for advanced materials in several economies also encourages investment in electronic-grade crystals.
⮞Shanghai Customs data released in August 2026 showed that lab-grown diamond exports through the Shanghai Diamond Exchange rose 65.3% in the first half of 2026. The jump highlights the export orientation of Chinese output.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Lab-Grown Diamonds Market Insights
North America ranked second, holding a 29.12% share of the Lab-Grown Diamonds Market in 2025. The United States supplies most of the regional demand through a bridal market that has moved decisively toward lab-grown center stones. Canada adds a smaller but steadily growing retail base. National jewelry chains, independent retailers and online-first brands compete on certified inventory and transparent pricing, which keeps the product visible to mainstream shoppers across income groups. Gift-giving occasions such as anniversaries and graduations add year-round volume.
Technology buyers form the second pillar of regional demand. Designers of power electronics, laser systems and sensing equipment evaluate diamond heat spreaders and optical windows because the material conducts heat efficiently and tolerates harsh operating conditions. Trade policy and customs treatment of synthetic stones influence landed costs and sourcing choices, while investor interest in advanced materials supports pilot production of electronic-grade crystals. Research universities and national laboratories contribute process know-how that suppliers can commercialize. Radiation detection and aerospace electronics programs add specialized demand.
Europe Lab-Grown Diamonds Market Insights
Europe represented 21.04% of the Lab-Grown Diamonds Market in 2025, with Germany, the United Kingdom, Italy, France and Spain forming the main demand centers. Established jewelry manufacturing in Italy and Germany gives lab-grown collections a ready route to retailers. Consumer protection rules require clear disclosure of how a stone was made, and buyers in the region respond well to sustainability and traceability messages in store and online. Bridal demand in the United Kingdom has been an early adopter of certified lab-grown rings.
Antwerp remains the principal trading hub for rough and polished diamonds, and its dealers are gradually widening their lab-grown handling and certification services. Regional policy support for semiconductor manufacturing is encouraging production of electronic-grade diamond. Luxury groups are also testing lab-grown lines in fashion jewelry, which supports steady growth in entry-level and mid-priced collections across several countries. Industrial toolmakers in Germany continue to specify synthetic grit for precision machining. Sustainability reporting expectations push jewelers to document stone origin and energy use.
⮞In January 2026, the Antwerp World Diamond Centre reported that synthetic diamonds accounted for just 0.37% of Antwerp's total 2025 diamond trade. The low share shows how much room remains for lab-grown integration within Europe's established trading channels.
MEA & Latin America Lab-Grown Diamonds Market Insights
In the Middle East and Africa, the United Arab Emirates operates as the leading hub for trading and re-exporting lab-grown stones. Dubai dealers connect Indian and Chinese producers with buyers across the Gulf, Africa and South Asia. Saudi Arabia and South Africa are developing retail demand as young consumers adopt certified lab-grown jewelry for weddings, family gifting and festive occasions. Free zone infrastructure, secure vaulting and certification services reinforce the position of the region as a trading center. Jewelers in the Gulf are expanding lab-grown counters to meet demand.
Latin America remains at an earlier stage of adoption, with Brazil and Mexico leading regional demand. Growing middle-class populations and a strong gifting culture support jewelry sales, while online marketplaces make imported stones easier to reach. Limited local production keeps the region dependent on Asian suppliers, so currency movements and import duties shape retail pricing and availability. Wider consumer education on certification and origin is expected to build trust over time. Rising awareness among younger shoppers is expected to lift demand for certified bridal stones.
⮞The Dubai Multi Commodities Centre reported in August 2026 that the United Arab Emirates traded 76.9 million carats of lab-grown diamonds in 2025, an increase of 91.5% over the previous year. The volume confirms the emirate's role as a gateway for global lab-grown trade.
Market Dynamics
Growth Drivers: Lower production costs and wider bridal acceptance are raising demand for lab-grown diamonds
Reducing cost curves are pushing the price of synthetic diamonds to a point where people who consider diamond jewelry a one-off purchase are now able to afford them. The reactors and presses supply consistently certified diamonds for less than mined diamonds. Younger generations prioritize traceability and sustainability in products and are willing to complete their purchase online using certificates of authenticity. Increased spending power in developing countries is making it a more common occurrence, and first time purchasers opt for bigger stones within the same price range. Retailers are increasing their product range with lab created gems that fall into bridal jewelry and fashion lines.
Technology industry demands provide a second boost. Diamonds are needed for cutting, grinding, drilling and polishing tools due to their durability and tolerance resistance. Lines of battery production need diamond tools, new radio frequency filters require high purity substrates, and quantum sensing programs use engineered nanodiamonds. All these uses of diamonds share the same reactor supply capacity, providing companies with an opportunity to adjust their technical grade outputs according to changes in demand. Growth in electronics manufacturing in Asia is boosting demand for technical grade offtake.
⮞India's lab-grown diamond exports reached USD 151.4 million in September 2026, up 40.7% year on year, according to data from the Gem and Jewellery Export Promotion Council. The export surge reflects strong overseas demand for polished lab-grown stones.
Restraints: Price erosion and shifting perceptions of rarity are weakening resale confidence in lab-grown diamonds
Rapid price erosion is the most visible constraint on value growth. As output expands, stones lose the exclusivity that once supported premium positioning, and resale values trail those of mined diamonds. Buyers also weigh lab-grown diamonds against alternatives such as white sapphire, which keep the entry ticket low. Perceptions of limited rarity discourage some luxury shoppers, while confusion over falling prices makes retailers cautious about inventory commitments and long-term guarantees. Natural diamond marketers continue to emphasize rarity and heritage, which reinforces the resale comparison.
Operating challenges compound these demand-side concerns. Reactor investment is capital intensive, and CVD wafers face thermal management problems when thicker than about 1 millimeter. Overcapacity in mature clusters keeps pricing under pressure and squeezes smaller producers. Inconsistent terminology across markets and uneven disclosure rules add friction at the point of sale, since shoppers cannot always compare descriptions, grading reports and claims on equal terms. Smaller sellers lack the scale to absorb inventory write-downs when prices fall quickly. Financing costs for new reactors remain high in many markets.
⮞CIBJO, the World Jewellery Confederation, decided in September 2026 to recommend “synthetic” as the only term for non-mined diamonds, rejecting “laboratory-grown.” The divergence from common trade usage may prolong labeling uncertainty at the point of sale.
Opportunities: Diamond wafers for chips, sensing and thermal management are opening demand beyond jewelry
The semiconductor and photonics sector represents the most expansive avenue for growth. The wafer material conducts heat much more effectively than silicon or silicon carbide, making it attractive to designers of power electronics, radio frequency devices and advanced packaging. Quantum sensing using nitrogen vacancy centers, radiation detection and aerospace electronics are being explored by research institutions and government funding programs. Suppliers who are capable of providing larger diameter wafers with controllable impurity levels can charge premium prices, not as susceptible to deflation from consumer prices. Research projects are already testing prototype designs.
Jewelry also offers areas to explore. Unique colors, weight and cuts are still limited at the premium end of the market, and added-value services like warranties, cleaning programs and upgrade packages enhance customer loyalty. Sustainability marketing through traceability and low carbon footprint can be leveraged to differentiate the brand in markets where sustainability marketing is part of the purchasing decision process. Latin America, the Middle East and Africa are still nascent markets, offering plenty of runway for retail expansion. D2C brands can also sell design services along with the stone.
⮞In December 2025, Invest in Spain, the Spanish government's investment agency, reported a USD 2.77 billion investment in a new diamond production plant aimed mainly at chip manufacturing, supported by public funding under the national semiconductor program. The project illustrates the commercial shift of lab-grown capacity toward electronics.
Recent Developments:
-
June 2026, Orbray reported a reproducible 3-inch wafer-scale single-crystal diamond process together with its development partner, with a 4-inch version under development and 2-inch wafers for thermal bonding prepared for volume production in Gresham, Oregon.
-
June 2025, Swarovski added an Octagon cut to its IGI-certified lab-grown diamond line and expanded its Italian network to 12 direct stores, with 10 new points of sale planned for the second half of the year.
-
August 2026, Pandora reported that sales of its lab-grown diamond jewelry fell 20% in the second quarter of 2026, with diamonds contributing only a small portion of overall earnings. The result highlights the price sensitivity of the mainstream category as wholesale values continue to decline and shoppers weigh lab-grown pieces against fashion alternatives.
-
May 2025, De Beers Group announced its intention to close Lightbox, its lab-grown diamond jewelry brand, and to keep its synthetic materials business focused exclusively on industrial solutions, consolidating CVD production at a single facility.
Lab-Grown Diamonds Market Key Players
-
Element Six
-
Diamond Foundry
-
Orbray
-
Swarovski
-
Pandora
-
Henan Huanghe Whirlwind
-
Zhongnan Diamond
-
Henan Liliang
-
Power Diamond
Lab-Grown Diamonds Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 29.79 Billion |
| Market Size by 2035 | USD 107.19 Billion |
| CAGR | CAGR of 13.66% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Method (HPHT and CVD) • By Size (Up to 2 Carats, 2 to 4 Carats, and Above 4 Carats) • By Application (Fashion and Industrial) • By Distribution Channel (Specialty Jewelry Stores, Online Retail, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Element Six, Diamond Foundry, Orbray, Swarovski, Pandora, Henan Huanghe Whirlwind, Zhongnan Diamond, Henan Liliang, Power Diamond |

Frequently Asked Questions
Element Six, Diamond Foundry, Orbray, Swarovski and Pandora are the key players in the Lab-Grown Diamonds Market, among others.
Opportunities arise from semiconductor applications, premium colored gemstones, value-added retail services, and expanding consumer awareness across emerging regional markets.
The major growth factor is the combination of falling production costs and rising consumer acceptance, especially among bridal buyers and younger shoppers who prefer certified, ethically sourced stones at prices well below mined diamonds.
The Up to 2 Carats segment dominated the Lab-Grown Diamonds Market in 2025 with a share of 63.72%. Affordable pricing, ease of production for jewelers and strong demand for engagement rings and everyday jewelry in the 1 to 2 carat range support the segment.
Asia Pacific dominated the Lab-Grown Diamonds Market in 2025 with a share of 34.73%.
