
Low Dielectric Materials Market Report Scope & Overview:
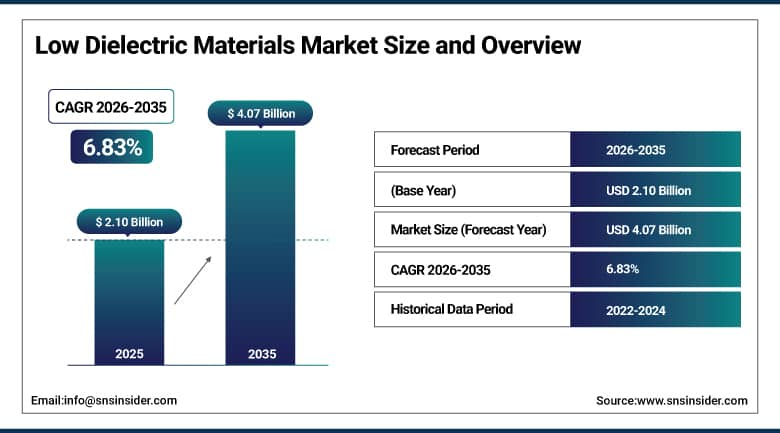
The Low Dielectric Materials Market size was valued at USD 2.10 Billion in 2025 and is expected to reach USD 2.24 Billion in 2026, rising to USD 4.07 Billion by 2035. The market is projected to grow at a CAGR of 6.83% during 2026–2035. Low dielectric materials are insulating polymers, resins and ceramics that combine a low dielectric constant with low signal loss, so that fast electrical signals can pass through circuit boards, antennas, cables and chip packages with little distortion. Rising data rates in artificial intelligence servers, 5G networks and satellite links are lifting demand for these materials.
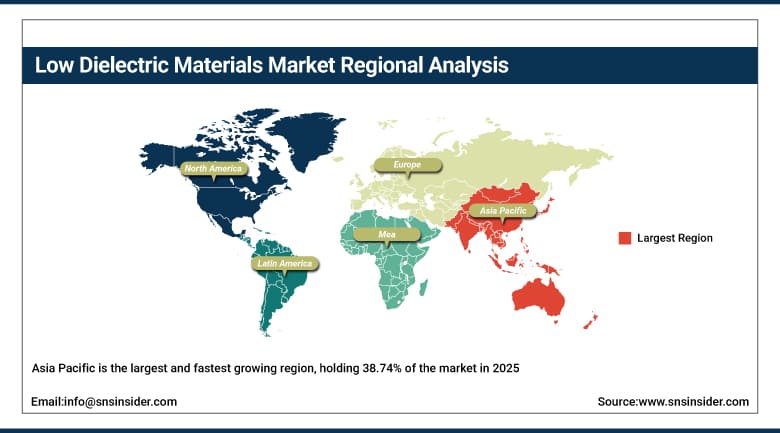
Asia Pacific accounted for the largest share of the market, at 38.74% in 2025, supported by dense laminate, circuit board and semiconductor manufacturing in China, Taiwan, Japan and South Korea. The region is also the fastest growing. North America follows, helped by data center investment and chip packaging programs, while Europe contributes through automotive radar, industrial electronics and aerospace uses. Latin America and Middle East & Africa are expanding from smaller bases as telecom networks, data center projects and local electronics assembly grow, although most advanced grades are still imported from Asia, North America and Europe.
To Get More Information On Low Dielectric Materials Market - Request Free Sample Report
Key Report Takeaways
-
By type, thermoplastics held a 45.37% share in 2025, while thermosets are the fastest growing.
-
By material, fluoropolymers held a 32.31% share in 2025, while cyclic olefin copolymer is the fastest growing.
-
By application, printed circuit boards held a 43.28% share in 2025, while antennas are the fastest growing.
-
By end-use industry, consumer electronics held a 31.76% share in 2025, while data centers are the fastest growing.
-
By region, Asia Pacific held a 38.74% share in 2025 and is also the fastest growing.
Market Trends and Insights
Laminate makers are moving to resin systems with lower loss and tighter control of the glass weave. Modified polyphenylene ether, hydrocarbon and cyanate ester resins are replacing conventional epoxy in high-speed boards, and quartz or low-profile glass cloth is paired with smoother copper foil to reduce signal attenuation.
Materials are also being designed for higher frequencies and thinner builds. Liquid crystal polymer films, cyclic olefin copolymers and fluoropolymer laminates serve millimeter wave antennas, while build-up films and photoimageable dielectrics support finer lines in advanced chip packages.
Drivers Impact Analysis
|
Driver |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Artificial intelligence servers and data center build-out |
+3.52% |
Global |
Medium term (2 to 4 years) |
|
5G-Advanced and 6G network development |
+2.31% |
Asia Pacific and North America |
Long term (4 years or more) |
|
Semiconductor and advanced packaging investment |
+1.64% |
Asia Pacific and North America |
Medium term (2 to 4 years) |
|
Automotive radar and electric vehicle electronics |
+0.58% |
Europe and Asia Pacific |
Medium term (2 to 4 years) |
|
Satellite communication and defense electronics |
+0.40% |
North America and Europe |
Long term (4 years or more) |
Artificial Intelligence Servers and Data Center Build-Out
Training and inference clusters move enormous volumes of data between processors, memory and switches, and every added gigabit raises the penalty for signal loss on the board. Low loss laminates, prepregs and resins are therefore specified for accelerator boards, switch trays and backplanes. The IPC reported in September 2026 that North American circuit board shipments rose 23.50% year over year, a sign of strong demand for the boards that use these materials. Each new server generation lifts the material grade required, which raises revenue per board.
5G-Advanced and 6G Network Development
Mobile operators are densifying networks and moving into higher frequency bands, where base station antennas, radio units and backhaul links need substrates with a stable dielectric constant. The 3GPP reported in March 2026 that its study of scenarios and requirements for 6G radio access was 60.00% complete, with technology proposals to follow before specifications are submitted by mid-2030. Early research on millimeter wave and sub-terahertz bands is already pushing suppliers toward liquid crystal polymer, fluoropolymer and cyclic olefin grades with very low loss.
Semiconductor and Advanced Packaging Investment
Chip makers are building new fabrication and packaging capacity, and each advanced package uses insulating films, substrates and underfills with low permittivity to limit delay between closely spaced interconnects. The Semiconductor Industry Association reported in August 2026 that global semiconductor sales reached USD 403.30 Billion in the second quarter of 2026, a rise of 35.10% from the first quarter. Higher chip output and larger package sizes are expected to increase consumption of build-up films and photosensitive dielectrics. Packaging substrates for accelerators also grow in layer count, which multiplies material use per unit.
Automotive Radar and Electric Vehicle Electronics
Advanced driver assistance systems depend on 77 GHz radar sensors, and each vehicle now carries several of them, along with high-speed cameras, central computing units and in-vehicle networks. These modules need laminates and plastics that hold stable electrical properties across wide temperature swings and years of vibration. Electric vehicles also add power electronics and battery management boards with demanding insulation requirements. Automakers in Europe and China are specifying higher grade materials as sensor counts per vehicle rise. Rising content per vehicle makes this a dependable source of volume.
Satellite Communication and Defense Electronics
Low earth orbit constellations, airborne radar and electronic warfare systems operate at high frequencies and require lightweight, thermally stable dielectrics. Phased array antennas use multilayer boards made from ceramic-filled polytetrafluoroethylene, polyimide and liquid crystal polymer, and radomes depend on materials that pass radio waves with minimal loss. Government procurement of sensing, communication and missile defense systems supports stable orders for qualified suppliers, and long program lives keep approved materials in production for many years. Space agencies and defense ministries also fund research into radiation-tolerant and low-outgassing dielectric systems.
Restraints Impact Analysis
|
Restraint |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Restrictions on fluorinated chemicals |
-0.71% |
Europe and North America |
Medium term (2 to 4 years) |
|
Raw material cost and supply tightness |
-0.49% |
Global |
Short term (2 years or less) |
|
Processing complexity and manufacturing yield |
-0.27% |
Asia Pacific and Europe |
Medium term (2 to 4 years) |
|
Long qualification cycles |
-0.15% |
Global |
Long term (4 years or more) |
Restrictions on Fluorinated Chemicals
Fluoropolymers are the largest material group, so proposals to limit per- and polyfluoroalkyl substances create planning uncertainty. The risk and socio-economic committees of the European Chemicals Agency met in December 2025 to evaluate the universal restriction proposal, and further consultation steps were scheduled for 2026. Although many electronics uses may receive time-limited exemptions, customers are already testing hydrocarbon, polyimide and cyclic olefin alternatives. Producers must invest in emission controls, reporting and substitute grades, which adds cost and may slow new fluoropolymer approvals.
Raw Material Cost and Supply Tightness
Specialty inputs such as high purity quartz, low-profile glass cloth, ultra-smooth copper foil and polyphenylene ether oligomers are produced by few suppliers, and demand from artificial intelligence boards has outpaced capacity. Shortages lengthen lead times and allow suppliers to pass on higher prices, which squeezes laminate makers and board fabricators with fixed-price contracts. Fluorspar, a feedstock for fluoropolymers, is also concentrated in a few countries. Smaller consumers find it hard to secure allocations, so some delay launches or accept lower grade materials.
Processing Complexity and Manufacturing Yield
Low dielectric materials are often harder to process than standard epoxy systems. Polytetrafluoroethylene has poor adhesion and needs plasma treatment before copper plating, while liquid crystal polymer demands precise temperature control during lamination and cyclic olefin parts can be brittle. Hybrid stack-ups that mix low loss and conventional layers raise the risk of warpage and delamination. Lower yields and extra process steps increase board cost, and fabricators with limited experience may stay with familiar materials even when electrical performance would improve.
Long Qualification Cycles
Electronics makers test any new dielectric thoroughly before approval, covering electrical stability, thermal cycling, humidity resistance, flame retardancy and long term reliability. Telecommunications, automotive and aerospace customers often require one to three years of qualification, and a change in resin or glass cloth can trigger a fresh round. These cycles delay revenue for new entrants and make customers cautious about switching suppliers. Producers must fund sampling, application support and test facilities in advance of any volume orders. Longer lead times for qualification therefore favor incumbents.
Low Dielectric Materials Segment Analysis
By Type, Thermoplastics Dominate Low Dielectric Materials Market; Thermosets to Register Fastest Growth.
Thermoplastics hold a 45.37% share in 2025, helped by fluoropolymers, cyclic olefin copolymers, liquid crystal polymers and polyphenylene sulfide that offer intrinsically low permittivity without the need for chemical curing. They can be extruded, molded or cast into films, wire insulation and antenna housings, which suits high volume production. Their resistance to moisture, strong chemical stability and recyclability of scrap further support steady purchases from cable, connector and antenna manufacturers. Established supply chains and low conversion costs sustain their lead.
Thermosets are projected to expand at a CAGR of 7.63% during 2026–2035. Cyanate ester, hydrocarbon, bismaleimide and modified polyphenylene ether resins can be cured into rigid, heat resistant laminates that match the glass transition and dimensional needs of multilayer boards. Artificial intelligence servers and base stations call for these low loss resin systems, and laminate makers are scaling production lines and developing formulations that process like conventional epoxy. Producers in Taiwan and Japan are expanding output to meet this demand.
By Material, Fluoropolymers Dominate Low Dielectric Materials Market; Cyclic Olefin Copolymer to Register Fastest Growth.
Fluoropolymers account for 32.31% of the market in 2025 because polytetrafluoroethylene and related grades offer one of the lowest dielectric constants and loss factors among practical materials. They keep these properties across wide frequency and temperature ranges, and they resist chemicals and heat. Radar boards, satellite payloads, base station antennas and coaxial cables have relied on them for decades, so established qualification records give suppliers a strong position. Producers also supply films, tapes and filled composites that extend usage.
Cyclic olefin copolymer is anticipated to register a CAGR of 8.21% over 2026–2035. Its amorphous structure delivers a low dielectric constant, very low moisture uptake and good optical clarity, and it can be injection molded into thin, precise parts. Antenna modules, lenses for sensors, high-frequency films and capacitor films are widening its use, and its freedom from fluorine appeals to buyers preparing for chemical restrictions. Suppliers in Japan and Europe are adding production lines to meet requests from antenna developers.
By Application, Printed Circuit Boards Dominate Low Dielectric Materials Market; Antennas to Register Fastest Growth.
Printed circuit boards represent a 43.28% share in 2025 since nearly every high-speed or high-frequency electronic system needs laminates, prepregs and resin-coated copper to guide signals. Servers, switches, routers, base stations and test equipment all use multilayer boards with controlled impedance, and each step up in data rate calls for a lower loss grade. The scale of the global board industry gives this application a lasting lead over cables and microelectronics. This breadth keeps demand resilient across cycles.
Antennas are expected to grow at a CAGR of 8.54% from 2026 to 2035. Millimeter wave handsets, phased array base stations, vehicle radar and satellite terminals place radiating elements on low loss substrates or inside radomes, where small changes in permittivity alter beam shape. Antenna-in-package designs, smart glass antennas and low earth orbit terminals are multiplying the number of antennas in each device, and each one needs carefully chosen dielectric materials. Material suppliers are responding with dedicated grades.
By End-Use Industry, Consumer Electronics Dominates Low Dielectric Materials Market; Data Centers to Register Fastest Growth.
Consumer electronics holds a 31.76% share in 2025 as smartphones, tablets, laptops, wearables and wireless earbuds ship in very large numbers, and each device contains flexible circuits, antennas and high-speed interconnects. Liquid crystal polymer films, modified polyimide and low loss laminates support multi-band radios and fast wired links inside these products. Annual upgrade cycles, thinner designs and the addition of Wi-Fi 7 and ultra-wideband features keep volumes high. Brands also value light weight, which favors thin films over bulky parts.
Data centers are projected to advance at a CAGR of 9.37% during 2026–2035. Operators are installing artificial intelligence clusters whose boards, cables and optical modules run at 224 gigabits per second and above, which demands ultra-low-loss laminates and low-skew glass. Spending on racks, networking and power continues to climb, and procurement teams increasingly set material specifications early, giving qualified suppliers visibility into multi-year demand. Optical transceivers and active electrical cables add further volume, since each link needs high grade insulation.
Geography Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
37.52% |
|
North America |
United States |
84.17% |
|
Europe |
Germany |
26.91% |
|
Latin America |
Brazil |
46.58% |
|
Middle East & Africa |
Saudi Arabia |
27.64% |
Asia Pacific Low Dielectric Materials Market
Asia Pacific is the largest and fastest growing region, holding 38.74% of the market in 2025 and projected to expand at a CAGR of 7.59% over 2026–2035. China leads regional demand because it hosts the largest base of laminate, board and cable producers, as well as fast-growing 5G and data center deployment. Taiwan, Japan and South Korea add advanced packaging, resin chemistry and handset component supply that anchor the regional value chain. Government support for local supply chains adds to this momentum.
India is emerging as a new production base, as 10 semiconductor projects had been approved by the government by April 2026, covering fabrication, assembly and packaging. Southeast Asian countries, notably Malaysia and Vietnam, attract board and module assembly, which draws laminate suppliers closer to customers. Local producers in China are also raising their share of mid-grade laminates and resins, narrowing the technology gap with Japanese suppliers. Supplier audits and joint development projects with global board makers are very common in the region today.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Low Dielectric Materials Market
North America accounted for 27.14% of the market in 2025. The U.S. market was valued at USD 479.72 Million in 2025 and is projected to register a CAGR of 6.97% during 2026–2035. Hyperscale data center operators, aerospace and defense primes, and satellite communication companies create demand for high-grade laminates, ceramic-filled polytetrafluoroethylene and radome materials, and several leading material developers are headquartered in the region. The region is also active in photonic, quantum and radar research that demands custom dielectric materials.
Public funding is strengthening the local base, as the Department of Commerce announced USD 1.40 Billion in advanced packaging awards in January 2025, including USD 300.00 Million for substrates and materials research. Canada contributes through telecom equipment and photonics, while Mexico belongs to Latin America yet supplies assembly capacity for North American electronics. Tighter supply chain security rules encourage buyers to qualify regional sources of resins and laminates. Utilities, railways and public safety agencies are also upgrading their communication links.
Europe Low Dielectric Materials Market
Europe held 22.37% of the market in 2025, with Germany as the leading country. The region has a strong automotive electronics sector, and radar sensors, connectivity modules and central computing units for vehicles need stable, low-loss insulating materials. German and French producers of industrial automation, medical imaging and aerospace equipment also buy high-frequency laminates, while specialty chemical companies in Belgium, Switzerland and Austria supply resins and films. Medical device makers add demand for low-loss cables and compact antennas in connected equipment.
The United Kingdom and the Nordic countries contribute through telecom equipment, space systems and defense electronics. Environmental policy plays a large role, since proposed restrictions on fluorinated substances are driving research on hydrocarbon, polyimide and cyclic olefin alternatives. Investment in European semiconductor and data center capacity is expected to maintain steady demand, although high energy costs weigh on local resin and film production. European space agencies and satellite manufacturers also regularly order radiation-resistant laminates and low-outgassing resins for spacecraft payloads.
Latin America Low Dielectric Materials Market
Latin America represented 6.43% of the market in 2025, with Brazil as the leading country. Electronics assembly zones in Manaus and Sao Paulo, along with 5G network rollouts by national carriers, create steady demand for imported laminates, cables and antenna components. Most advanced materials are brought in from Asia and North America, so regional purchasing depends on exchange rates and customs procedures, and local value creation is concentrated in cable insulation and assembly. Local brands of consumer electronics add modest volumes of flexible circuits.
Mexico is an important second market, because its border manufacturing plants assemble servers, automotive electronics and telecom equipment for North American customers. Chile, Colombia and Argentina are building mobile and fiber networks, which raises demand for antennas and coaxial cables. Growth is moderate and tied to telecom investment cycles, while distributors and regional compounders play a key role in supplying small and medium volumes. Because buyers are price sensitive, suppliers often offer standard grades from regional warehouses with short delivery times.
Middle East & Africa Low Dielectric Materials Market
Middle East & Africa held 5.32% of the market in 2025. Saudi Arabia and the United Arab Emirates lead demand through 5G deployment, smart city projects and new hyperscale data centers, which require antennas, cabling and server hardware built with low-loss materials. Telecom operators are also investing in fiber and microwave backhaul that relies on low-loss cables and radomes. Israel adds a cluster of semiconductor, radar and defense electronics firms, and its exports support regional demand for high-frequency laminates and microelectronic dielectrics.
South Africa and Egypt are building mobile infrastructure, and satellite ground stations are spreading across the African continent. Local production of advanced dielectric materials remains limited, so almost all supply is imported through distributors serving telecom integrators and defense contractors. Large project spending in the Gulf countries is expected to make the region one of the steadier contributors, although purchasing is uneven from year to year. Training programs and local assembly partnerships are slowly widening the technical base for future adoption.
Competitive Landscape
The Low Dielectric Materials Market is moderately concentrated. Specialty chemical groups, laminate producers and fluoropolymer manufacturers compete on electrical performance, process compatibility, reliability data and supply security. Japanese, American, European and Chinese suppliers each hold strong positions in selected materials, while a long tail of regional laminate and compounding firms serves local customers, and the five leading companies account for a share below half of global sales.
Vendors pursue capacity expansion, new resin and laminate launches, joint development with board fabricators and chip makers, and longer term supply agreements. Many are adding production in Asia close to customers, while others are developing fluorine-free grades and ultra-low-loss systems for 224 gigabit signaling to prepare for chemical regulation and the next generation of servers.
Low Dielectric Materials Industry Leaders
1. Rogers Corporation: U.S. maker of high-frequency laminates such as RO3000, RO4000 and RT/duroid series.
2. The Chemours Company: Fluoropolymer producer supplying Teflon-based materials for copper-clad laminates and cables.
3. SABIC: Chemical group supplying NORYL modified polyphenylene ether resins and oligomers for laminates.
4. Panasonic Industry: Japanese producer of MEGTRON low-loss circuit board materials for servers and networks.
5. Resonac: Japanese materials group supplying copper-clad laminates and resins for high-speed boards.
Companies Covered in this Report
-
Rogers Corporation
-
The Chemours Company
-
SABIC
-
Panasonic Industry
-
Resonac
-
DIC Corporation
-
TOPAS Advanced Polymers
-
Daikin Industries
-
Advanced Chip and Circuit Materials (ACCM)
-
Ventec International Group
-
Eray Technology
Recent Industry Developments
-
August 2025: Sichuan Dongfang Insulating Material announced a new project to produce 20,000 tons a year of electronic materials for high-speed communication substrates.
-
December 2025: SABIC announced another expansion of its polyphenylene ether oligomer capacity for laminates used in artificial intelligence and 5G data center boards.
-
January 2026: Resonac announced a 30.00% price increase for copper-clad laminates used in artificial intelligence servers.
-
March 2026: Panasonic Industry committed funds to an additional MEGTRON production line in Guangzhou, China, for multilayer board materials used in artificial intelligence servers.
-
March 2026: Ventec International Group launched its chiplam portfolio, which includes low-loss materials for high-speed and radio frequency packaging and test applications.
-
April 2026: ACCM introduced Celeritas SF1600, a low-loss laminate with a dielectric constant of 2.80 and a dissipation factor of 0.0007 for PCIe 7 designs.
-
May 2026: Eray Technology signed a pre-listing counseling agreement to fund expansion in low-loss laminates for artificial intelligence servers and satellite boards.
Scope and Research Methodology
This study estimates the Low Dielectric Materials Market for 2025 as the base year and forecasts it through 2035. The scope covers insulating polymers, resins, films, laminates and ceramics sold for their low dielectric constant and low dissipation factor, including fluoropolymers, modified polyphenylene ether, polyimide, cyclic olefin copolymer, cyanate ester and liquid crystal polymer. Values are reported in USD at the material producer level. Silicon-based interlayer dielectrics deposited inside wafer fabrication lines are outside the scope. Segmentation covers type, material, application, end-use industry and region. Both finished materials and intermediate forms such as resin systems, prepregs, laminates, films and compounds are considered, and revenue from testing or service activity is excluded.
Secondary research included company annual reports, investor presentations and filings, regulator and government databases, trade association data, product documentation, and peer-reviewed and industry publications. Primary research consisted of structured interviews and surveys with executives, product and business heads, procurement managers, laminate and board fabricators and end-user stakeholders across the value chain. These inputs were used to validate adoption rates, grade mix and pricing. Interviews covered the Americas, Europe and Asia Pacific, and responses were compared with supplier disclosures to test the reliability of grade mix and price assumptions.
Market size was built from the bottom up using producer revenue, capacity and shipment data, and cross-checked from the top down against circuit board output, semiconductor packaging activity and telecom and data center equipment spending. Triangulation across these views fixed the base year value. Forecasts consider technology transitions, chemical regulation, capacity additions and macroeconomic conditions, and the model was run under conservative, base and optimistic cases. Price trends, product mix, capacity utilization and regional demand were modeled separately for each material before being combined into the global totals and regional splits. An analyst quality review checked logic, sources and consistency across segments before release.
Low Dielectric Materials Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 2.10 Billion |
| Market Size by 2035 | USD 4.07 Billion |
| CAGR | CAGR of 6.83% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (Thermoplastics, Thermosets, and Ceramics) • By Material (Fluoropolymers, Modified Polyphenylene Ether, Polyimide, Cyclic Olefin Copolymer, Cyanate Ester, Liquid Crystal Polymer, and Others) • By Application (Printed Circuit Boards, Antennas, Microelectronics, Wire & Cable, and Radomes) • By End-Use Industry (Consumer Electronics, Telecommunications, Data Centers, Automotive, and Aerospace & Defense) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | The Chemours Company, SABIC, Panasonic Industry, Resonac, DIC Corporation, TOPAS Advanced Polymers, Daikin Industries, Advanced Chip and Circuit Materials (ACCM), Ventec International Group, Eray Technology |

Frequently Asked Questions
The Low Dielectric Materials Market was valued at USD 2.10 Billion in 2025 and is projected to reach USD 4.07 Billion by 2035, growing at a CAGR of 6.83% during 2026–2035.
Asia Pacific leads, with a 38.74% share in 2025, supported by the concentration of laminate, board and semiconductor manufacturing.
Asia Pacific is also expected to grow fastest, at a CAGR of 7.59% during 2026–2035, led by China.
Thermoplastics, fluoropolymers, printed circuit boards and consumer electronics lead, while thermosets, cyclic olefin copolymer, antennas and data centers grow fastest.
Rogers Corporation, The Chemours Company, SABIC, Panasonic Industry and Resonac lead, along with Huntsman, DIC and TOPAS Advanced Polymers.
