
Medical Robots Market Report Scope & Overview:
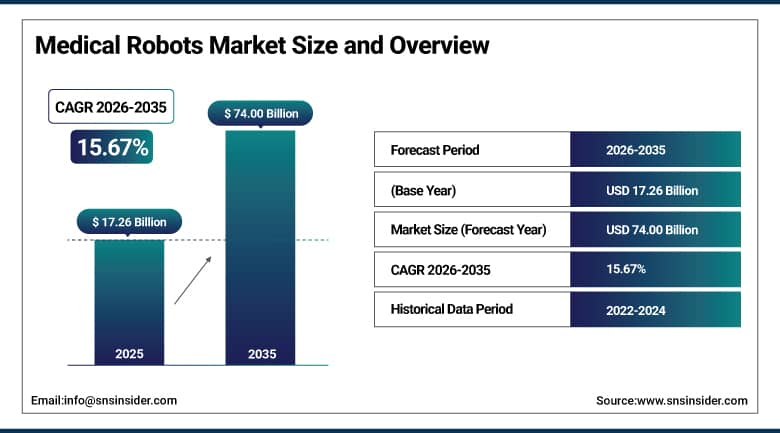
The Medical Robots Market was valued at USD 17.26 Billion in 2025 and is estimated at USD 19.96 Billion in 2026. It is projected to reach USD 74.00 Billion by 2035, advancing at a CAGR of 15.67% from 2026 to 2035. Hospitals are adopting robotic platforms to improve surgical precision, shorten recovery, and relieve pressure on scarce operating room staff, while rehabilitation and hospital automation robots extend the market beyond the operating room. Growing procedure volumes, new platform launches, and wider clinical evidence continue to support steady capital spending across hospitals worldwide.
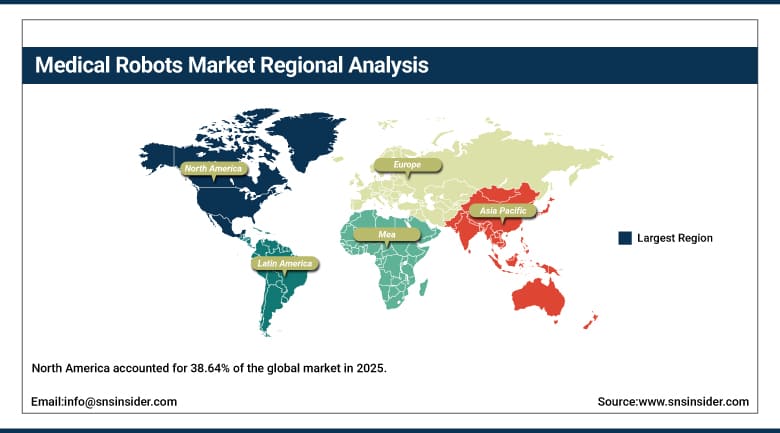
North America was the largest regional market in 2025 with a 38.64% share. Early adoption of robotic surgery, strong reimbursement, and a large installed base of systems keep the region ahead. Europe follows as national health services invest in robotic programs. Asia Pacific is expected to register the fastest expansion over the forecast period because China, Japan, and India are building surgical capacity, approving domestic platforms, and increasing hospital investment in advanced equipment. Together, the United States and Canada account for most installed systems, and the region hosts most of the leading manufacturers and training centers.
To Get More Information On Medical Robots Market - Request Free Sample Report
Key Report Takeaways
- By product type, surgical robots held a 52.47% share in 2025, while rehabilitation robots are the fastest growing.
- By application, laparoscopy accounted for a 34.91% share in 2025, while neurology is the fastest growing.
- By end user, hospitals represented a 55.62% share in 2025, while ambulatory surgical centers are the fastest growing.
- By component, instruments and accessories commanded a 41.37% share in 2025, while services are the fastest growing.
- By region, North America led with a 38.64% share in 2025, while Asia Pacific is the fastest growing.
Market Trends and Insights
Artificial intelligence is entering the operating room. Systems now offer image-based guidance, automated camera control, and procedure analytics, and several developers are testing autonomous steps in orthopedic cutting and suturing.
Compact and handheld robots are spreading in orthopedics. Lower capital cost and smaller footprints allow ambulatory surgical centers and community hospitals to adopt robotic assistance without dedicated operating room redesign.
New soft-tissue platforms are widening competition. Additional multi-arm systems have gained regulatory authorization or are under review, giving hospitals more choice on price, instrument design, and service terms.
Remote surgery is moving from demonstration to limited commercial use. Faster networks and low-latency control software allow surgeons to operate on patients in other provinces and countries under approved programs.
Drivers Impact Analysis
|
Driver |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Rising Adoption of Robot-Assisted Surgery |
+6.43% |
Global, led by North America and Western Europe |
Medium term (2 to 4 years) |
|
Workforce Shortages and Surgeon Productivity |
+4.62% |
Global |
Short term (2 years or less) |
|
AI, Imaging, and Navigation Advances |
+3.97% |
North America, Europe, and Asia Pacific |
Medium term (2 to 4 years) |
|
Ambulatory Surgery Center Expansion and Coverage |
+3.14% |
North America |
Short term (2 years or less) |
|
Aging Population and Chronic Disease Burden |
+1.71% |
Global |
Long term (4 years or more) |
Rising Adoption of Robot-Assisted Surgery
Surgeons and hospitals increasingly prefer robotic assistance for procedures that benefit from precise instrument control, such as urology, gynecology, general surgery, and joint replacement. Shorter stays, fewer complications, and consistent technique support the clinical and economic case. NHS England reported in June 2025 that about 70,000 robotic operations took place during 2023 and 2024, and it expects the number to rise sharply by 2035. Public health systems are therefore planning robotic capacity alongside conventional theaters. Hospitals respond by expanding robotic schedules.
Workforce Shortages and Surgeon Productivity
Hospitals face shortages of experienced surgeons, anesthetists, and operating room nurses, and robotic platforms help each team do more with less physical strain. Ergonomic consoles reduce surgeon fatigue, which can extend careers and increase case capacity. Automation of pharmacy compounding, supply delivery, and disinfection also frees clinical staff for patient care. Administrators see these systems as a way to protect throughput when hiring is difficult, and this argument has strengthened purchasing decisions across both public and private hospitals. Efficiency gains are therefore closely watched.
AI, Imaging, and Navigation Advances
Better cameras, preoperative planning software, and real-time navigation are turning robots into data-driven tools. Machine learning supports tissue recognition, instrument tracking, and performance feedback for training. The International Federation of Robotics reported in October 2025 that medical robot sales nearly doubled in 2024 to about 16,700 units. Continuous software updates add value to installed systems, so providers earn recurring revenue and hospitals extend the useful life of their equipment. Surgeons also gain objective performance data that supports credentialing, outcome tracking, and quality improvement programs.
Ambulatory Surgery Center Expansion and Coverage
More procedures are shifting from hospitals to ambulatory surgical centers, particularly in orthopedics, urology, and gynecology. The Centers for Medicare & Medicaid Services finalized a 2026 payment rule in November 2025 that added more than 500 procedures to the covered list for these centers. Compact robotic platforms with lower purchase cost suit this setting, and surgeons who use robotic assistance in hospitals expect similar tools in the centers where they also operate. This trend is expected to continue as payment parity improves.
Aging Population and Chronic Disease Burden
Older populations require more joint replacement, cardiac, cancer, and neurological care, and they also need rehabilitation after stroke or injury. Robotic gait trainers and exoskeletons help therapists deliver repetitive, measurable exercise to larger numbers of patients. Surgical robots support the growing volume of procedures in older adults by limiting blood loss and speeding recovery. Rising rates of obesity and cancer add further demand for precise minimally invasive techniques over the long term. Demand from both patient groups is expected to remain durable.
Restraints Impact Analysis
|
Restraint |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
High Upfront and Recurring Cost |
-1.86% |
Global, strongest in smaller hospitals |
Medium term (2 to 4 years) |
|
Surgeon Training and Skilled Staff Gaps |
-1.12% |
Global |
Medium term (2 to 4 years) |
|
Regulatory Approval Complexity |
-0.78% |
United States and Europe |
Long term (4 years or more) |
|
Safety and Cybersecurity Concerns |
-0.44% |
Global |
Long term (4 years or more) |
High Upfront and Recurring Cost
A surgical robot typically requires a large capital outlay, proprietary instruments, annual service contracts, and room modification. Smaller hospitals and rural facilities often cannot justify these costs against modest procedure volumes. In April 2025 the National Institute for Health and Care Excellence allowed five soft-tissue systems to be used during a three-year evidence generation period, which reflects continuing questions about cost-effectiveness. Leasing and per-procedure pricing are spreading but add complexity to hospital budgets. Hospitals therefore often delay purchases until volumes justify them.
Surgeon Training and Skilled Staff Gaps
Robotic surgery needs structured training, simulation, and proctored cases before surgeons reach proficiency. The learning period lengthens operating time at first and can reduce schedule efficiency. Hospitals also need technicians who can set up, sterilize, and maintain the systems. Smaller centers struggle to hire these staff, and surgeons who rotate between hospitals may not have access to the same platform everywhere, which slows adoption of new systems and limits utilization of those already installed. Training programs are expanding but still take time.
Regulatory Approval Complexity
Robotic systems are combination products of hardware, software, and instruments, and each new indication often requires clinical evidence and agency review. Novel platforms may need the De Novo pathway, which can take many months. The U.S. Food and Drug Administration published draft guidance on premarket submissions for robotically assisted surgical devices in September 2026, and developers must plan for changing documentation expectations as well as differing rules in Europe, China, and Japan. Smaller companies find the cost of multiple submissions especially heavy.
Safety and Cybersecurity Concerns
Mechanical failure, instrument defects, and software faults can harm patients and trigger recalls, so hospitals demand strong safety records. Connected robots also create cybersecurity exposure, since remote service links and cloud analytics increase the number of possible entry points. Developers must invest in secure design, monitoring, and incident response. Perceived risk, even when events are rare, can delay purchasing decisions and require additional validation before hospital committees approve new platforms. Hospitals increasingly request security documentation from vendors before signing purchase agreements.
Medical Robots Market Segment Analysis
By Product Type, Surgical Robots Dominate Medical Robots Market; Rehabilitation Robots to Register Fastest Growth.
Surgical robots lead because they command the highest unit prices and carry recurring instrument and service revenue. Procedures in urology, gynecology, general surgery, and orthopedics have moved quickly to robotic assistance, and each new platform clearance widens the list of covered operations. Hospitals view these systems as a marker of advanced care. Surgical robots accounted for 52.47% of the market in 2025. Training programs, proctoring networks, and strong surgeon preference reinforce the lead of this category across hospital departments.
Rehabilitation robots are growing fastest as therapy centers and hospitals adopt exoskeletons, gait trainers, and upper-limb devices for stroke and spinal cord injury. These systems deliver repeatable training and record patient progress, which helps justify reimbursement. An aging population and wider home use of wearable devices support a CAGR of 18.12% from 2026 to 2035. Home-based devices that connect to clinic dashboards are appearing, and insurers increasingly accept robotic therapy for patients with limited mobility after serious injury.
By Application, Laparoscopy Dominates Medical Robots Market; Neurology to Register Fastest Growth.
Laparoscopy holds the top position because soft-tissue procedures in the abdomen and pelvis suit multi-arm robots with wristed instruments and three-dimensional vision. Hysterectomy, hernia repair, colorectal surgery, and prostatectomy are performed in large numbers, and surgeon familiarity is high. Established training pathways support rapid uptake. Laparoscopic procedures represented 34.91% of the market in 2025. Surgeon training for these procedures is well established, and hospitals can recover robot investment quickly because of the steady flow of routine gynecologic and abdominal cases.
Neurology is growing fastest as robots assist with electrode placement, biopsy, and spine and cranial procedures that require sub-millimeter accuracy. Integration with imaging and stereotactic planning raises confidence in difficult cases. Epilepsy, movement disorder, and tumor programs continue to expand, supporting a CAGR of 17.08% from 2026 to 2035. Surgeons also value the ability to plan trajectories in advance and to verify position during the procedure, which reduces the risk of damage to critical structures near the brain and spine.
By End User, Hospitals Dominate Medical Robots Market; Ambulatory Surgical Centers to Register Fastest Growth.
Hospitals are at the helm because they have the most complex surgeries, have the capital budget for the expensive robots, and have the specialist surgeons that can use them. The larger organizations purchase several robots that can be used by different departments, while the academic organizations function as training centers. In 2025, hospitals comprised 55.62% of the market. Constant financial resources, specialist surgeons, and ability to accommodate emergency and complex surgery cases are some of the reasons why hospitals continue being major buyers despite the rise in outpatients.
The ambulatory surgical centers are growing at the highest rate due to their low costs and preference of payers and patients for low cost care outside hospitals. Robotic equipment, which is compact and relatively low in price and can be used for orthopedic and urological surgery, is suitable for such an organization. The Medicare expansion that allows patients to receive outpatient care and the 17.46% CAGR until 2035 is some of the factors for growth of ambulatory surgical centers.
By Component, Instruments and Accessories Dominate Medical Robots Market; Services to Register Fastest Growth.
Instruments and accessories lead because each procedure consumes single-use or limited-use items, which generate recurring revenue long after a system is installed. Growing procedure volumes on an expanding installed base keep demand high. Manufacturers also design instruments to work only with their own platforms. Instruments and accessories represented 41.37% of the market in 2025. Because each procedure uses new instruments, revenue scales with case volume, and hospitals cannot switch suppliers once surgeons train on a particular platform and instrument set.
Services are growing fastest as hospitals sign multiyear contracts for maintenance, training, software updates, and remote monitoring. Subscription models spread the cost of ownership and keep systems current. As the installed base ages and more systems enter service, this segment is projected to advance at a CAGR of 16.58% from 2026 to 2035. Hospitals also value predictable budgeting, uptime guarantees, and access to remote diagnostics, which makes service agreements an increasingly important part of platform sales and long-term customer retention.
Geography Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
84.73% |
|
Europe |
Germany |
27.64% |
|
Asia Pacific |
China |
35.47% |
|
Middle East & Africa |
Saudi Arabia |
35.27% |
|
Latin America |
Brazil |
45.93% |
North America Medical Robots Market
North America accounted for 38.64% of the global market in 2025. The region has the largest installed base of surgical robots, strong reimbursement for minimally invasive procedures, and a dense network of academic medical centers that train surgeons. Most leading manufacturers are headquartered there, and hospitals compete on access to advanced technology. Rapid growth of outpatient surgery adds demand for compact platforms. Training fellowships and industry-sponsored surgical education centers help new surgeons gain proficiency in short periods across the United States and Canada.
The United States contributed USD 5.65 Billion in 2025 and is projected to grow at a CAGR of 15.94% from 2026 to 2035. Hospital systems continue to add robots across orthopedics, urology, and general surgery, and private equity-backed surgery centers are following. Canada contributes through provincial programs that fund robotic systems in major teaching hospitals and cancer centers. Orthopedic robots are spreading quickly in outpatient joint replacement programs, and several hospital networks now require robotic capability when recruiting surgeons for high-volume service lines.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Medical Robots Market
The second most significant regional market is Europe due to health service provision in individual countries, advanced medical device manufacturing and conducting clinical research. Germany, France, UK and Italy are leading in installation numbers, and several states are drafting their national plans for robotic surgery. Health technology assessment organizations are more actively studying available data on new solutions and influencing the pace of their implementation in practice. Public procurement usually includes training and maintenance together with robots and requires many months of negotiations that favor companies offering local service and having strong evidence of their effectiveness.
Competitive soft tissue and orthopedic robotic solutions have been developed in Europe, and local production companies can provide short and reliable supply chain and close cooperation with hospitals. The regulation of medical devices increases documentation needs, but also provides trust of physicians. The rehabilitation robotics has become widespread in Germany and Switzerland, where specialized rehabilitation clinics use exoskeletons in their standard treatment. There is telemedicine associated rehabilitation program and research centers in university hospitals, and cross-border cooperation in surgery contributes to sharing protocols of new procedures.
Asia Pacific Medical Robots Market
The Asia Pacific is the fastest-growing region, with a CAGR of 17.34% between 2026 and 2035. China is authorizing and deploying indigenous surgical robots, Japan is providing insurance cover for robotic procedures, and India is installing systems in private hospital chains. Large number of patients along with the demands from the increasing middle class for high-quality surgery fuel the spending. The government programs aimed at the manufacture of medical devices and the development of modernized hospitals in China and India drive the production and distribution of surgical robots.
Local companies are reducing prices and creating services networks, which make robotic surgery affordable to hospitals. South Korea and Australia are providing mature adopters along with good surgeon training programs. Telesurgical experiments performed in China show the interest of the region in making specialists available in remote regions despite the differences in the insurance coverage in some markets. Hospitals in Japan, South Korea, and Australia have already started adopting single-port and orthopedic robots, and surgeon training exchanges with Southeast Asia transfer skills to nearby countries.
Latin America Medical Robots Market
Latin America is led by Brazil, where private hospital networks and leading public university hospitals have installed surgical robots in major cities. Mexico, Argentina, and Colombia add demand through private insurers and medical tourism. Hospitals often start with a single system and expand once case volumes justify the investment. Public hospitals face tight budgets, so most installations are in private institutions that serve insured patients and international visitors. Distributors play an important role by arranging financing, surgeon training, and maintenance for hospitals.
Currency volatility and import costs raise the effective price of robotic systems, and public budgets limit adoption outside large urban centers. Manufacturers respond with leasing, local training centers, and partnerships with distributors. As procedure volumes rise and regional surgeons gain experience, the region should offer gradual growth. Surgeon societies in Brazil and Mexico are organizing credentialing courses, and early adopters publish local outcome studies that help persuade insurers to reimburse robotic procedures. Cooperation with regional teaching hospitals is expanding trained operator numbers.
Middle East & Africa Medical Robots Market
Middle East & Africa is still the smallest region in terms of coverage, but Gulf states are working on specialized hospitals and national health strategies that have advanced surgical technology. Saudi Arabia and UAE have already installed robotic technology in major hospitals and international surgeons for training. Governments' health strategies in the Gulf encourage advanced surgery training programs, medical cities bring international surgeons, and partnerships with foreign companies allow training and proctoring for local teams. Robotic surgery is advertised by hospitals in order to attract patients from other countries.
In other parts of the region, the problem is high prices and lack of surgical capacity. South Africa is the leader in the development of the private hospital sector and it is where the most installations in the region are located. In the future, donor projects and regional training programs will increase access to robot-assisted treatments. Private hospital companies in Kenya, Nigeria, and Morocco are considering robotic surgery programs in cooperation with foreign partners, but the main problems are poor electricity supply, lack of biomedical engineers, and import taxes.
Competitive Landscape
The market is moderately concentrated. A few global surgical robotics leaders hold a large share of installed systems, while orthopedic specialists, radiosurgery providers, rehabilitation firms, and new soft-tissue entrants compete in specific procedures. Competition depends on clinical evidence, instrument range, platform cost, and the quality of training and service. High regulatory and capital barriers protect established leaders, although new authorizations are widening hospital choice.
Vendors pursue acquisitions, product launches, and strategic alliances. Purchases of robotics start-ups add autonomy and imaging capabilities, while new clearances extend platforms into additional indications such as cardiac and urologic surgery. Partnerships between established device makers and robotics developers combine commercial reach with new technology, and handheld systems are introduced to reach ambulatory surgical centers.
Medical Robots Market Industry Leaders
1. Intuitive Surgical: Developer of the da Vinci multi-port and single-port soft-tissue systems and the Ion bronchoscopy platform.
2. Medtronic: Maker of the Hugo robotic-assisted surgery system for soft-tissue procedures and a broad surgical technology portfolio.
3. Stryker: Developer of the Mako SmartRobotics platform for knee, hip, and shoulder arthroplasty.
4. Zimmer Biomet: Provider of the ROSA robotic platform for knee, hip, shoulder, and brain procedures.
5. Johnson & Johnson MedTech: Developer of the OTTAVA soft-tissue robotic surgical system and other robotic-assisted orthopedic technology.
Companies Covered in this Report
- Intuitive Surgical
- Medtronic
- Stryker
- Zimmer Biomet
- Johnson & Johnson MedTech
- Accuray
- Globus Medical
- Smith+Nephew
- CMR Surgical
- PROCEPT BioRobotics
- Distalmotion
- Medicaroid
- Microbot Medical
- Lifeward
- MicroPort MedBot
- Moon Surgical
- Wandercraft
Recent Industry Developments
- March 2025: Moon Surgical received FDA clearance for ScoPilot, an artificial intelligence feature for its Maestro surgical assistant system.
- May 2025: MicroPort MedBot received approval from China's regulator for its Toumai tele-robotic surgical system for commercial clinical use.
- September 2025: Microbot Medical received FDA 510(k) clearance for its LIBERTY single-use endovascular robotic system.
- October 2025: Zimmer Biomet completed its acquisition of Monogram Technologies, adding autonomous orthopedic robotics.
- December 2025: Medtronic received FDA clearance for its Hugo robotic-assisted surgery system for urologic procedures.
- January 2026: Intuitive Surgical received FDA clearance for da Vinci 5 in selected cardiac procedures.
- June 2026: Smith+Nephew announced the first clinical cases with its CORI XT handheld robotics platform for knee and shoulder arthroplasty.
- July 2026: Johnson & Johnson MedTech received De Novo authorization from the FDA for its OTTAVA robotic surgical system.
Scope and Research Methodology
This report defines the Medical Robots Market as the commercial value of robotic systems, instruments, accessories, and related services used for surgery, rehabilitation, radiosurgery, hospital and pharmacy automation, and telepresence in healthcare settings. It covers equipment sold to hospitals, ambulatory surgical centers, rehabilitation centers, and other care providers. The base year is 2025, the forecast period runs from 2026 to 2035, and all values are stated in USD. Segmentation covers product type, application, end user, component, and region. Training services, spare parts, and software subscriptions are included when sold with robotic systems, while general surgical instruments and conventional equipment are excluded from market value. Rehabilitation devices sold for home use are included.
The research program combines secondary and primary work. Secondary research draws on company annual reports, investor presentations and filings, regulator and government databases, trade association data, product documentation, and peer-reviewed and industry publications. Primary research consists of structured interviews and surveys with executives, product and business heads, procurement teams, and end-user stakeholders across the value chain. These conversations validate assumptions, adoption rates, and pricing, and they test how demand is expected to change by procedure and region. Findings from both routes are cross-referenced to resolve conflicts and identify gaps, and company disclosures are reviewed for installed base, instrument usage, and contract terms.
Market engineering follows a bottom-up build from vendor revenue and installed base data, cross-checked top-down against hospital capital spending and procedure volumes. Estimates are triangulated across these routes until the results converge within an acceptable range. Forecasts incorporate adoption, regulation, technology change, and macroeconomic conditions. Sensitivity checks test pricing, procedure growth, and installation assumptions, and senior analysts review every estimate and narrative section. Regional estimates are checked against hospital counts, surgical volumes, and national health expenditure so that country totals align with the global figure. Scenario analysis then stresses assumptions on system placements, instrument utilization, and pricing.
Medical Robots Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 17.26 Billion |
| Market Size by 2035 | USD 74.00 Billion |
| CAGR | CAGR of 15.67% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (Surgical Robots, Rehabilitation Robots, Non-Invasive Radiosurgery Robots, Hospital and Pharmacy Robots, and Telepresence Robots) • By Application (Laparoscopy, Orthopedics, Neurology, Cardiology, and Others) • By End User (Hospitals, Ambulatory Surgical Centers, Rehabilitation Centers, and Others) • By Component (Instruments and Accessories, Robotic Systems, and Services) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Intuitive Surgical, Medtronic, Stryker, Zimmer Biomet, Johnson & Johnson MedTech, Accuray, Globus Medical, Smith+Nephew, CMR Surgical, PROCEPT BioRobotics, Distalmotion, Medicaroid, Microbot Medical, Lifeward, MicroPort MedBot, Moon Surgical, Wandercraft |

Frequently Asked Questions
The market was valued at USD 17.26 Billion in 2025 and is estimated at USD 19.96 Billion in 2026. It is projected to reach USD 74.00 Billion by 2035.
The market is projected to expand at a CAGR of 15.67% from 2026 to 2035.
North America led with a 38.64% share in 2025. Asia Pacific is the fastest-growing region, with a CAGR of 17.34% from 2026 to 2035.
Surgical robots, laparoscopy, hospitals, and instruments and accessories lead their axes. Rehabilitation robots, neurology, ambulatory surgical centers, and services grow fastest.
Intuitive Surgical, Medtronic, Stryker, Zimmer Biomet, and Johnson & Johnson MedTech are the best-documented manufacturers.
