
Mirror Coatings Market Report Scope and Overview
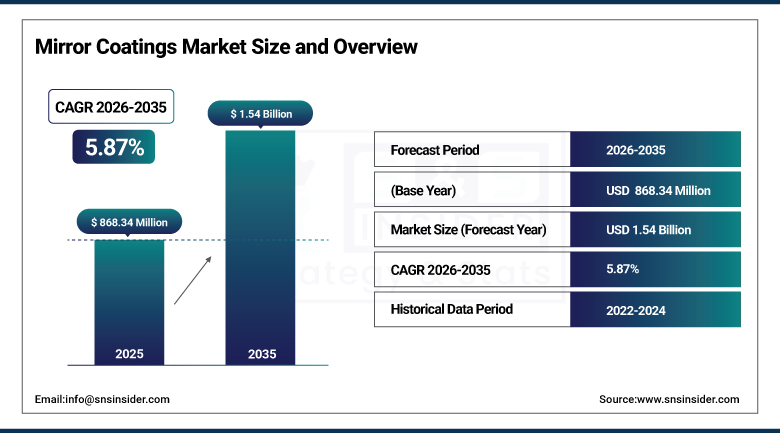
The Mirror Coatings Market was valued at USD 868.34 Million in 2025 and is estimated at USD 919.31 Million in 2026. The market is forecast to reach USD 1.54 Billion by 2035, registering a CAGR of 5.87% from 2026 to 2035. Growth reflects steady construction and interior design activity, rising use of mirrors in vehicles, and the build-out of solar power plants that rely on reflective surfaces. Asia Pacific led the market in 2025, while North America held a share of 17.93%, and Asia Pacific is also expected to expand fastest as building and solar capacity rise across the region.
To Get more information Mirror Coatings Market - Request Free Sample Report
Key Market Trends & Insights
-
By resin type: Polyurethane held the largest market share of 47.63% in 2025.
-
By technology: Solvent-based coatings held the largest market share of 44.26% in 2025.
-
By end use: Architectural held the largest market share of 49.38% in 2025.
-
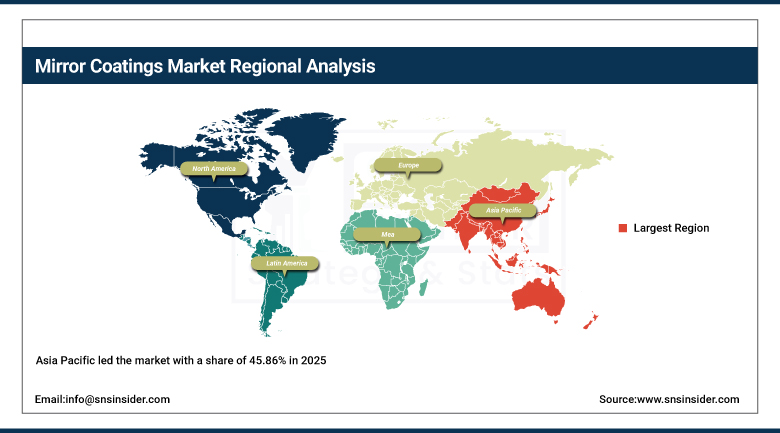
By region: Asia Pacific held the largest regional share of 45.86% in 2025, followed by Europe at 19.42% and North America at 17.93%.
-
Asia Pacific is projected to register the fastest regional CAGR of 6.94% from 2026 to 2035.
-
The U.S. is the leading country market in North America, supported by home improvement spending and solar installations.
Growth Outlook
Solar power is turning mirrors into industrial components as well as household items. In April 2026, the International Renewable Energy Agency reported that the world added 510 GW of solar photovoltaic capacity in 2025, along with about 1 GW of concentrated solar power. Concentrated solar plants use large fields of silvered glass mirrors that must hold their reflectivity for decades, so the backing paints and protective layers that guard the silver layer are critical to plant performance. Rising solar investment therefore supports demand for durable mirror coatings.
Vehicle production adds a second source of demand. In April 2026, the International Organization of Motor Vehicle Manufacturers reported that global vehicle production reached 96.40 million units in 2025, an increase of 3.90%. Each vehicle carries interior and exterior mirrors, and newer models add heated, auto-dimming, and camera-linked mirror assemblies that need coatings with strong adhesion and corrosion resistance. Commercial vehicle makers also fit larger mirrors and mirror arms, and replacement demand follows the large fleet in use, which keeps orders steady through the cycle.
Market Dynamics
Driver: Concentrated Solar Build-Out and Heliostat Demand Are Raising the Need for Durable Mirror Coatings
Solar thermal projects use mirrors at a scale that few other applications match. In June 2025, REN21 reported in its Global Status Report that global concentrated solar power capacity reached 7.20 GW at the end of 2024, with a pipeline in China of about 8.10 GW and 4.80 GW planned for 2026 to 2030. Heliostat and trough mirrors operate outdoors for many years, so developers specify backing paints that resist humidity, salt, and ultraviolet exposure, and suppliers with proven field records gain preference in tenders. Operators also demand warranties that cover reflectivity loss, which pushes mirror makers to qualify coatings with documented test results.
China is the main source of new capacity. In January 2026, the China Solar Thermal Alliance and the CSP Committee of the China Renewable Energy Society reported that the country connected nine concentrated solar plants with 900 MW of capacity in 2025, an increase of 107.00% from the previous year, taking cumulative capacity to 1,738.20 MW. Local mirror makers and coating suppliers are expanding output to serve these projects, and the same plants create demand for protective coatings that extend mirror life and lower maintenance cost. Developers also look to local supply to cut logistics cost and delivery times. Local content rules also favor regional suppliers.
Restraint: Metal Price Swings and Weak Construction Activity Limit Growth in Mature Segments
Silver is the main reflective metal used in mirrors, and any changes in the price of silver will affect the total cost of the product. In April 2026, The Silver Institute, in its annual World Silver Survey, indicated that there had been a deficit in the silver market for five consecutive years ending in 2025, and it expected another deficit of 46.30 million ounces in 2026. Any shortages in supply increase the uncertainty in pricing and put pressure on mirror producers, which they in turn transfer to coating suppliers via their price negotiations. Uncertainty is also created by resin and pigment prices. Mirrors producers tend to enter into short-term agreements with coating suppliers.
Construction softness is putting pressure on the largest end-use segment. As stated by the National Bureau of Statistics of China, the output of cement in 2025 fell by 6.90%, totaling 1.69 billion tonnes in January 2026, while the output of plate glass dropped by 3.00%, totalling 97.59 million weight cases in 2025. Soft construction activity implies less demand for architectural and decorative mirrors, while scattered players are pressured by margins. Stringent regulations regarding the solvents being used make reformulation expensive for manufacturers using solvents in their products. Regulations related to the environmental compliance of waste streams generated from silvering lines containing silver and tin salts add cost.
Opportunity: Low-VOC Coatings, Smart Mirrors, and Nanotechnology Create New Demand
Regulation is creating room for cleaner products. In May 2025, the Ministry of Industry and Information Technology of China issued the GB 30981.1-2025 standard on limits of harmful substances in architectural coatings, effective from 1 June 2026, which adds limits for semi-volatile organic compounds and biocides and requires disclosure. Such rules encourage a shift to water-based and low-VOC systems, and suppliers with lead-free and low-emission backing paints can gain share as buyers update specifications in other markets as well. Mirror makers that serve export markets also need to meet buyer rules on restricted substances, which supports demand for certified products.
There is a second opportunity with product innovation as well. Mirrors having screens and other technologies such as sensor and lighting require the coating that will not only protect the reflecting material but will not affect images on the screen either. Anti-fog, self-cleaning, and antimicrobial nano-coating is valuable in washrooms, health care centers, and even automobiles. Such coatings generate margins more significant than ordinary paint products. Suppliers of these materials can form long-term associations with clients, which upgrade the line. Mirrors needed in fitness studios, hotel areas, and healthcare centers require hygiene coating resistant to cleaning materials.
Market Characteristics & Concentration
The Mirror Coatings Market is Fragmented, with a mix of specialty chemical firms, glass groups, and regional paint makers. A small number of suppliers offer complete systems that include silvering chemicals, backing paints, and protective layers, while many local producers sell standard paints to mirror factories close to their plants. Pricing differs widely between standard paints and premium systems for solar and automotive uses. Specialty suppliers also compete through custom color and finish options for decorative uses.
Product quality shapes competition. Mirror makers look for coatings that resist copper loss, edge corrosion, and moisture, and they test candidates over long periods before approving them. Suppliers invest in technical service so that coating lines run at high speed with stable results, and approvals from large mirror makers form a barrier for new entrants. Long qualification periods protect suppliers once they are approved. Trial runs on customer lines are common before supply starts.
Regional presence is important because mirrors and paints are heavy to ship, and mirror factories sit close to float glass plants. Suppliers expand in Asia, the Middle East, and Eastern Europe to stay near customers, and some pair with equipment makers to offer complete lines. Joint ventures between glass groups and coating suppliers are also common in emerging regions. Distribution partners also help suppliers reach smaller mirror factories in these regions.
Analyst Perspective
The mirror coatings business is moving from a commodity paint market toward a performance market. Silver prices, environmental rules, and longer warranty expectations are pushing mirror makers to demand backing systems that protect the reflective layer for decades, particularly in solar and automotive uses. Suppliers that offer lead-free, low-solvent, and water-based systems, and that prove durability in field and laboratory tests, will capture the largest share of growth. Asia Pacific will set the pace as building activity and solar capacity expand together. An SNS Insider Analyst, Santosh Bhul, commented, "Durability and environmental compliance are now the deciding factors for mirror makers, and suppliers that deliver both will gain share across architectural and solar uses."
Segment Analysis
Resin Type Insights
Polyurethane accounted for the largest share of 47.63% in 2025. Polyurethane backing paints offer strong adhesion to the silver and copper layers, good flexibility, and resistance to humidity and edge corrosion, which are the main failure modes in mirrors. They suit high-speed coating lines and are widely used for architectural and decorative mirrors. Their balance of cost and durability keeps them the default choice for many mirror factories. Suppliers also offer products with low odor and fast curing to raise line speed and reduce rejects. Suppliers also provide technical service on film thickness and curing. Technical data is closely reviewed.
Acrylic is estimated to grow at the highest CAGR of 6.38% between 2026 and 2035. Acrylic resins offer a fast drying process, reduced odor, and can be utilized in water-based coating formulations meeting stringent environmental standards. Manufacturers who are keen on reducing solvent contents are shifting to acrylic resins; suppliers are also working to increase the adhesion and moisture resistance properties of their products. Growth will be significant in areas where strict standards are being imposed for coating materials. They are also producing hybrid formulations containing features of both polyurethane and acrylic resins. Prices are declining.
Technology Insights
Solvent-based coatings accounted for the largest share of 44.26% in 2025. These products have a long record of performance, dry quickly, and give consistent films on high-speed lines. Many mirror factories have equipment and curing ovens tuned for solvent systems, so switching takes time and capital. Producers continue to supply solvent-based paints, particularly in regions where regulation is less strict. Regulation in Europe and North America is the main reason some buyers are changing. Producers also upgrade formulations with better adhesion to meet quality needs while keeping line speed high for buyers.
The nanotechnology-based coatings will witness the highest growth at a CAGR of 7.68% from 2026 to 2035. The use of nanoadditives makes scratch-resistance, barrier properties, anti-fogging, and self-cleaning characteristics more effective and enables the use of thinner coating layers. High demand is driven by applications in premium mirrors, in the automotive industry, and in solar reflectors requiring high durability. Increased cost makes the adoption of this segment in general-purpose mirrors difficult, but the improved functionality helps in growing usage. Water-based types minimize fire hazards and reduce the ventilation requirement in the factories, favoring their use.
End Use Insights
Architectural accounted for the largest share of 49.38% in 2025. Mirrors are used in homes, offices, hotels, retail stores, and public buildings for walls, wardrobes, bathrooms, and fitness spaces, and construction and renovation activity set the pace of orders. Large volumes of flat mirrors are produced in Asia and sold worldwide. Suppliers value this segment for its scale, and it is the base for most mirror factories. Furniture makers and wardrobe suppliers also add steady volumes. Retail displays and hospitality interiors also add large volumes of custom mirrors each year.
Solar Power is projected to grow at the fastest CAGR of 7.92% from 2026 to 2035. Concentrated solar plants and heliostat fields use large silvered mirrors that must keep their reflectivity for decades in harsh outdoor conditions. Government programs, particularly in China and the Middle East, are adding capacity, and developers demand strict durability data from coating suppliers. Automotive and Transportation also grows steadily as vehicles add more mirror functions. Developers also require extended warranties on reflectivity. Suppliers also develop coatings for mirrors in transport equipment, where vibration resistance matters.
Regional Insights
North America held a share of 17.93% of the market in 2025, behind Asia Pacific and Europe. The region has a mature residential and commercial renovation market, a large vehicle base, and growing solar installations. Mirror makers in the region focus on high-quality and custom products and import standard mirrors from Asia. Canada adds demand through construction and automotive supply chains. Local suppliers also benefit from strong technical service networks. Suppliers also support customers with testing.
U.S. Mirror Coatings Market
The U.S. Mirror Coatings Market was valued at USD 125.08 Million in 2025 and is projected to expand at a CAGR of 5.41% from 2026 to 2035. Home improvement spending, hospitality renovation, and vehicle production support demand for mirrors, while environmental rules in states such as California shape coating choices. Coating suppliers focus on low-VOC systems and technical support for mirror fabricators. Suppliers also provide training and testing support to fabricators, and larger firms operate regional laboratories. Producers also develop low-VOC products for state rules. Home renovation remains a core driver of orders for mirror makers.
In March 2026, the Solar Energy Industries Association and Wood Mackenzie reported that the country installed 43.20 GWdc of solar capacity in 2025, a decline of 14.00%, though solar still made up 54.00% of new grid capacity. Utility-scale solar adds demand for reflective components, and developers continue to place orders for mirrors and coated glass for solar projects. Concentrated solar and heliostat projects remain small in number, but they carry high specifications and strong margins for suppliers able to meet them. Tender rules also reward long field records. Suppliers that offer certified products and documented test records are favored by project developers and large installers.
Europe Mirror Coatings Market
The European region represented 19.42% of the total market share in 2025; however, countries such as Germany, Italy, France, and Spain were the key domestic markets. In March 2026, Eurostat announced that the production of construction in EU in January 2026 dropped by 2.00% compared to the previous year. This is an indication of weak near-term demand for architectural mirrors. There are very stringent environmental regulations, and water-based and lead-free products dominate. The region has top manufacturers of mirror chemicals and coatings.
Automotive production supports steady demand, and in April 2026 the European Automobile Manufacturers Association reported that world car production reached 78.70 million units in 2025, an increase of 4.20%, with the EU accounting for 14.60% of global car output. Spain remains an important market for concentrated solar mirrors. Italian producers of mirror chemicals also supply many global customers. Producers in the region also supply products to mirror makers in other markets, including the Middle East and Africa. Local coating laboratories also support product approvals for customers across the region.
Asia Pacific Mirror Coatings Market
Asia Pacific led the market with a share of 45.86% in 2025 and is projected to register the fastest regional CAGR of 6.94% from 2026 to 2035, led by China, India, Japan, and South Korea. In April 2026, India reported record solar capacity additions of about 45 GW in fiscal 2026, as stated by the Union Minister for New and Renewable Energy, which adds demand for solar reflective products as well as for glass and mirrors.
The region hosts the largest mirror and float glass production base, and low-cost mirror exports from China, India, and Southeast Asia supply many global markets. Local coating suppliers compete on price, while international suppliers focus on premium and solar products. Rising urbanization and middle-class spending support demand for decorative and architectural mirrors. Government programs for housing and infrastructure further support demand for mirrors. Local mirror makers also expand lines with new coaters. Local suppliers also gain from short delivery times.
Get Customized Report as per Your Business Requirement - Enquiry Now
Latin America Mirror Coatings Market
Latin America accounted for 8.64% of the market in 2025, led by Brazil and Mexico. Residential construction, retail development, and automotive assembly support demand for mirrors, and the region imports many mirrors and coating materials from Asia and Europe. Local mirror makers serve building projects and furniture producers, and solar projects in Chile and Brazil add interest in reflective products. Coating suppliers pursue distributor partnerships and local technical service. Local currencies and import costs also shape demand.
Middle East & Africa Mirror Coatings Market
The Middle East and Africa held 8.15% of the market in 2025, led by Saudi Arabia, the United Arab Emirates, and South Africa. Large construction and hospitality projects drive demand for architectural mirrors, and Gulf countries are building solar and concentrated solar capacity. New float glass and coated glass lines in the Gulf support local mirror production. Imports still cover much of the demand for coatings, and suppliers work through distributors and project-based sales. Local partners also help suppliers reach project buyers.
Key Mirror Coatings Market Company Insights
Companies in the mirror coatings market are focusing on lead-free and water-based backing paints, long-life protective layers for solar mirrors, and nano coatings with added functions. Suppliers also work with glass makers and equipment makers to offer complete mirror lines. Capacity additions close to float glass plants, licensing agreements, and new coating equipment are shaping the competitive picture.
Key Mirror Coatings Companies:
-
Fenzi
-
Gujarat Guardian
-
Diamon-Fusion
-
AGC Plasma Technology Solutions
-
Hind High Vacuum
-
VON ARDENNE
Recent Developments
-
In July 2026, SEPCOIII commissioned a flexible assembly line in Qingdao for wind-resistant heliostats used in large concentrated solar power plants.
-
In June 2026, VON ARDENNE, together with Fraunhofer IST, received the Joseph von Fraunhofer Prize for the EOSS industrial optical sputtering system for precision coatings.
-
In May 2026, Gujarat Guardian held a groundbreaking for a second float line and a wet coater with 72,000 tonnes of annual capacity that supports mirror manufacturing, with completion planned by mid-2028.
-
In March 2026, AGC Plasma Technology Solutions presented a vertical inline vacuum coater for optical multilayer coatings and new sputtering magnet bars at Optatec 2026.
-
In January 2026, Diamon-Fusion International granted Nanoveu exclusive worldwide rights to deploy its nanocoatings in the concentrated solar power sector under a multi-year licensing agreement.
-
In December 2025, GulfGuard, a joint venture between Guardian Glass and ZOUJAJ, announced plans for a second float line and a second sputter coater in Jubail, Saudi Arabia.
Scope and Research Methodology
The study defines the Mirror Coatings Market as coatings applied to mirrors to protect and support the reflective metal layer, mainly backing paints and protective layers based on polyurethane, epoxy, acrylic, and other resins, together with related silvering and surface protection products. Reflective glass for building facades, anti-reflective lens coatings, mirror substrates, and mirror hardware are outside the scope. The base year is 2025, the forecast period runs from 2026 to 2035, and all values are expressed in USD. The segmentation covers resin type, technology, end use, and region, along with leading countries in each region. Both original equipment and replacement uses are considered.
The research program combines secondary and primary research. Secondary research draws on company annual reports, investor presentations and filings, government and regulator databases, trade association statistics, product documentation, and peer-reviewed and industry publications. Primary research consists of structured interviews and surveys with executives, product and business heads, procurement leaders, and end-user stakeholders at coating suppliers, mirror manufacturers, and glass groups. These discussions validate assumptions on coating consumption per square meter, pricing, and adoption. Interview responses are weighted by the seniority and product relevance of each respondent and cross-checked against company disclosures.
Market engineering follows a bottom-up build from supplier revenue, mirror output, and coating consumption per unit, cross-checked top-down against construction, vehicle, and solar installation indicators. Triangulation across both approaches narrows differences before values are finalized. Forecasts reflect drivers such as construction activity, solar capacity, regulation, and macroeconomic conditions, and every estimate passes through an analyst quality review that tests consistency across segments, regions, and years. Sensitivity checks test the effect of changes in silver prices, construction output, and solar capacity on each segment, and country values are aligned so that regional totals add to the global value. The final review confirms consistency across years. Forecasts are refreshed as new data arrives.
Mirror Coatings Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 868.34 Million |
| Market Size by 2035 | USD 1.54 Billion |
| CAGR | CAGR of 5.87% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Resin Type (Polyurethane, Epoxy, Acrylic, and Others) • By Technology (Solvent-based, Water-based, and Nanotechnology-based) • By End Use (Architectural, Automotive & Transportation, Decorative, Solar Power, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Fenzi, Gujarat Guardian, Diamon-Fusion, AGC Plasma Technology Solutions, Hind High Vacuum, VON ARDENNE |

Frequently Asked Questions
The market was valued at USD 868.34 Million in 2025 and is projected to reach USD 1.54 Billion by 2035.
Asia Pacific led the market with a 45.86% share in 2025, ahead of Europe at 19.42% and North America at 17.93%.
Asia Pacific is expected to grow the fastest, at a CAGR of 6.94% from 2026 to 2035.
Polyurethane led the resin type segment with a 47.63% share in 2025, and architectural led the end use segment.
Key players include Fenzi, Gujarat Guardian, Diamon-Fusion, AGC Plasma Technology Solutions, and Hind High Vacuum.
