
Missile Seekers Market Report Scope & Overview:
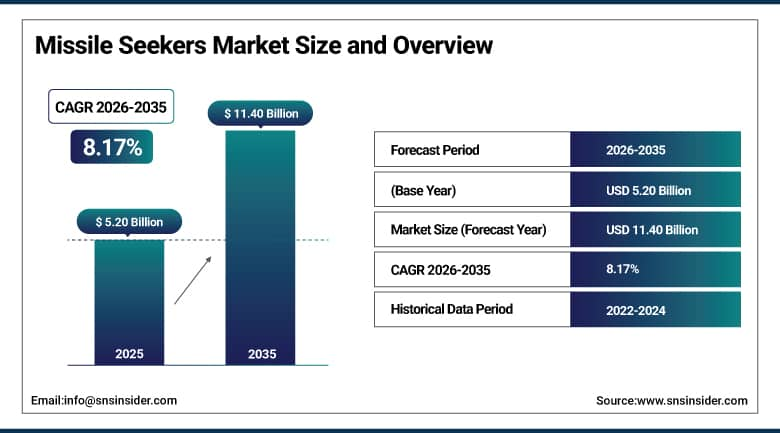
The Missile Seekers Market was valued at USD 5.20 Billion in 2025 and is expected to reach USD 11.40 Billion by 2035, growing at a CAGR of 8.17% from 2026-2035.
Missile seeker systems have become the epitome of precision attack technology systems because of the use of sensors and complex guidance algorithms in these systems for detecting, targeting, and destroying valuable targets. These missile seekers that are used for detecting, tracking, and guiding of missiles are becoming more complex due to the use of advanced sensing technologies and signal processing methods since the contemporary warfare environment requires greater precision. The industry has been witnessing robust growth due to growing modernization efforts within the defense sector, procurement of advanced missiles, and requirements for precision guided weapon systems in the modern warfare environment where development of innovative missile seekers is an essential strategy for maintaining superiority in the battlefield. Growth is being further driven by military modernization efforts, regional security concerns, asymmetric warfare, counter-air and anti-ship operations, and the development of counter-ballistic missiles systems.
In July 2025, the U.S. Department of Defense awarded Raytheon, an RTX Corporation business, a contract valued at up to USD 3.50 billion for AMRAAM Production Lots 39 and 40. AMRAAM uses an onboard active radar for terminal target acquisition and interception, featuring active radar guidance that enables autonomous terminal engagement and allows the launching platform to maneuver, engage other targets, or disengage from the fight, reflecting sustained defense procurement demand for proven, combat-validated seeker technology across allied air forces worldwide.
Market Size and Forecast
-
Market Size in 2026E: USD 5.62 Billion
-
Market Size by 2035: USD 11.40 Billion
-
CAGR (2026-2035): 8.17%
-
Fastest Growing Region: Asia Pacific
-
Largest Region: North America
To Get More Information On Missile Seekers Market - Request Free Sample Report
Missile Seekers Market Trends
-
Rising adoption of multi-mode seekers combining infrared, radar, and laser sensing for improved target discrimination.
-
Growing investment in counter-UAS missile seeker technology addressing proliferating drone threats worldwide.
-
Expanding development of dual-mode seekers improving performance in complex, electronically contested combat environments.
-
Increasing demand for seeker systems supporting hypersonic weapon development programs across major defense powers.
-
Rising integration of sensor-fusion software and counter-countermeasure functions improving target-recognition accuracy.
-
Growing collaboration between defense primes on interoperable seeker technologies enhancing aircraft survivability systems.
U.S. Missile Seekers Market Outlook
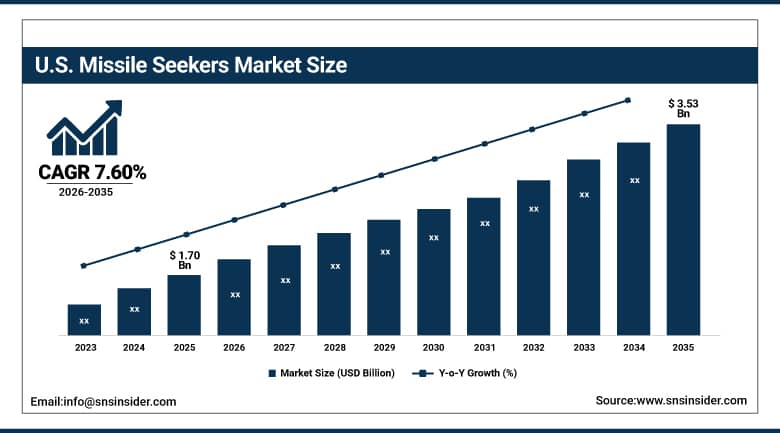
The U.S. Missile Seekers Market was valued at USD 1.70 Billion in 2025 and is expected to reach USD 3.53 Billion by 2035, growing at a CAGR of 7.60% from 2026-2035.
The US Missile Seekers Market is set to remain positively impacted by continued increases in defense budgets, rising geopolitical tensions, and the significant presence of missile system manufacturers and seeker technologies in the country. Domestic procurement will continue to focus on both legacy seekers and multi-mode seekers which can operate effectively despite the presence of sophisticated countermeasures and electronic warfare capabilities. The country’s large-scale efforts towards replenishing depleted munition stocks due to continuous support to allied nations will continue to fuel the demand for seekers in the country. Hypersonic weapon development efforts within the country will need advanced seeker technologies which can perform efficiently at supersonic speeds and extremely high temperatures.
In September 21, 2026, the U.S. Army awarded Lockheed Martin an indefinite delivery, indefinite quantity contract worth up to USD 1.2 billion to produce Increment 2 of the Precision Strike Missile, following a second flight test that demonstrated the missile's ability to engage moving maritime targets. Increment 2 adds a multimode seeker designed to enable the missile to engage moving land and maritime targets, expanding the Army's long-range strike options and moving the program from development and flight testing into full production, advancing the nation's next-generation long-range precision fires capability.
Missile Seekers Market Segment Analysis
-
By Seeker Type, the Infrared segment dominated the Missile Seekers Market with approximately 38.60% share in 2025, while the Active Radar segment is the fastest growing with a CAGR of approximately 8.60%.
-
By Missile Mission, the Surface-to-Air & Air-Defense segment dominated the Missile Seekers Market with approximately 34.60% share in 2025, while the Counter-UAS segment is the fastest growing with a CAGR of approximately 13.90%.
-
By Component, the Signal Processing & Electronics segment dominated the Missile Seekers Market with approximately 42.60% share in 2025, while the Cooling & Thermal Management segment is the fastest growing with a CAGR of approximately 9.60%.
-
By Platform, the Ground-Based segment dominated the Missile Seekers Market with approximately 44.60% share in 2025, while the Airborne segment is the fastest growing with a CAGR of approximately 9.20%.
By Seeker Type, Infrared Dominates the Missile Seekers Market and Active Radar Grows Fastest
Infrared seekers, particularly imaging infrared focal plane array variants, dominate the market due to their wide deployment across air-to-air and anti-armor missile programs spanning virtually every major air force and ground combat vehicle fleet worldwide. This dominance reflects decades of accumulated infrared sensing expertise and a deeply established manufacturing and supply chain base capable of delivering both the raw sensor arrays and the accompanying signal processing electronics required for reliable target lock-on across a wide range of atmospheric and battlefield obscurant conditions. Infrared seekers continue to benefit from their passive operating mode, which allows a missile to home in on a target's heat signature without emitting any detectable radar energy, an important tactical advantage in contested electromagnetic environments where active emissions can reveal a launching platform's position or trigger countermeasure activation well before intercept. Continued refinement of cooled and uncooled infrared detector arrays, combined with advances in image processing algorithms capable of distinguishing genuine targets from flares and other decoys, continues to reinforce infrared seekers' position as the single largest seeker type category across the broader missile seekers market.
Active radar seekers represent the fastest-growing seeker type, reflecting their extensive and expanding use across air-to-air, surface-to-air, anti-ship, anti-radiation, and missile-defense systems that increasingly demand fire-and-forget engagement capability. Active radar guidance enables autonomous terminal engagement that allows the launching aircraft or platform to disengage, maneuver, or prosecute additional targets immediately after missile release, a capability that continues to reshape modern air combat doctrine and drive sustained procurement of radar-guided munitions across allied air forces. Passive radio-frequency and millimeter-wave technologies embedded within modern active radar seekers continue to improve performance against fast-moving targets and within electronically contested environments where jamming and spoofing threats have grown increasingly sophisticated. As defense budgets worldwide continue prioritizing precision-strike capability over less discriminate munitions, active radar seeker demand continues to climb faster than the broader, infrared-dominated seeker category, positioning this technology at the center of next-generation missile procurement programs across major defense powers.
By Missile Mission, Surface-to-Air & Air-Defense Dominates the Missile Seekers Market and Counter-UAS Grows Fastest
Surface-to-air and air-defense missiles dominate the market due to high procurement volumes driven by the sheer scale of national and allied air-defense network requirements, spanning short-range point-defense systems through long-range strategic interceptor programs designed to counter increasingly diverse aerial threats. Countries worldwide continue to invest heavily in layered air-defense architectures capable of countering everything from conventional aircraft and cruise missiles to increasingly capable ballistic missile threats, and each layer within these architectures typically requires its own dedicated seeker technology optimized for the specific engagement envelope and target characteristics involved. The scale of recent multiyear procurement agreements for major air-defense interceptor programs, several of which have reached tens of billions of dollars in total contract value, continues to underscore just how central surface-to-air and air-defense missiles remain to overall global seeker demand. This sustained, large-volume procurement activity across virtually every major and mid-tier military power worldwide continues to anchor surface-to-air and air-defense missiles' position as the largest mission category within the broader missile seekers market.
Counter-UAS missiles represent the fastest-growing mission segment, registering the highest projected growth rate as the proliferation of low-cost, readily available unmanned aerial systems continues to create an urgent and rapidly evolving threat that conventional air-defense systems were never originally designed to address. Recent conflicts have demonstrated with striking clarity how swarms of inexpensive drones can overwhelm traditional air-defense architectures, prompting defense ministries worldwide to accelerate development and procurement of dedicated counter-UAS interceptor systems equipped with seekers specifically optimized to detect and track small, slow-moving, and often low-radar-cross-section targets that larger conventional seekers struggle to reliably engage. This urgent operational requirement, combined with the sheer scale of drone proliferation across both state and non-state actors, continues to drive sustained above-market growth for counter-UAS missile seeker technology as militaries race to close this genuine and rapidly widening capability gap.
By Component, Signal Processing & Electronics Dominates the Missile Seekers Market and Cooling & Thermal Management Grows Fastest
Signal processing and electronics hold the largest component share, as modern seekers require high-speed processors, radio-frequency electronics, target-recognition algorithms, counter-countermeasure functions, and sensor-fusion software to reliably distinguish genuine targets from clutter, decoys, and increasingly sophisticated electronic interference. This component category represents the genuine computational brain of a modern missile seeker, translating raw sensor data into the split-second targeting decisions that ultimately determine engagement success, and the growing complexity of this processing challenge continues to command an outsized share of overall seeker development investment. As adversaries continue fielding more sophisticated electronic countermeasures, decoy systems, and low-observable platform designs, seeker manufacturers must continuously refine their signal processing algorithms to maintain reliable target discrimination capability, a technological arms race that shows no sign of slowing and continues to reinforce this component category's position as the largest and most strategically important element of the broader missile seeker architecture.
Cooling and thermal management represents the second-fastest-growing component category, as increasingly powerful signal processing electronics and higher-performance infrared detector arrays continue to generate substantial heat loads that must be efficiently managed within the extremely constrained volume and weight envelope of a missile airframe. This thermal management challenge has grown considerably more acute as seekers incorporate ever more sophisticated cooled infrared detectors and higher-throughput processing chips, both of which demand precise temperature regulation to maintain sensor sensitivity and processing reliability throughout a missile's flight envelope, particularly during high-speed engagements where aerodynamic heating adds further thermal stress. Continued development of hypersonic weapon systems, which subject onboard electronics to extreme thermal environments throughout sustained high-Mach flight, continues to reinforce sustained above-market growth for advanced cooling and thermal management solutions across the broader missile seeker component supply chain.
By Platform, Ground-Based Dominates the Missile Seekers Market and Airborne Grows Fastest
Ground-based platforms dominate the market due to large-scale land-based air and missile defense deployment across virtually every major military power, spanning fixed strategic installations through mobile, road-transportable interceptor batteries designed to provide layered protection for critical infrastructure and population centers. The sheer geographic scale of national air-defense requirements, combined with the proliferation of increasingly mobile and dispersed ground-based interceptor systems designed to complicate adversary targeting, continues to drive substantial and sustained seeker procurement across this platform category. Ground-based systems also benefit from a generally less constrained size, weight, and power envelope relative to airborne platforms, allowing for larger, more capable seeker and processing architectures that can deliver superior detection range and target discrimination capability, further reinforcing this platform category's position as the largest source of missile seeker demand worldwide.
Airborne platforms represent the fastest-growing platform category, reflecting sustained fighter aircraft modernization programs and the continued proliferation of increasingly capable air-to-air and precision air-to-surface munitions across both fifth-generation and upgraded legacy fighter fleets worldwide. As air forces worldwide continue transitioning toward stealthier, more capable fighter platforms carrying internally mounted precision munitions, demand for compact, high-performance seeker technology optimized for airborne integration continues to accelerate faster than the broader, ground-based-dominated market. Continued development of extended-range air-to-air missiles and increasingly sophisticated air-launched anti-ship and land-attack munitions, each requiring seeker technology capable of reliable operation across increasingly demanding launch and engagement envelopes, continues to reinforce sustained above-market growth for airborne missile seeker platforms through the forecast period.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
84.60% |
|
Europe |
Germany |
29.60% |
|
Asia Pacific |
China |
39.60% |
|
Middle East & Africa |
United Arab Emirates |
32.60% |
|
Latin America |
Brazil |
24.60% |
North America Missile Seekers Market Insights
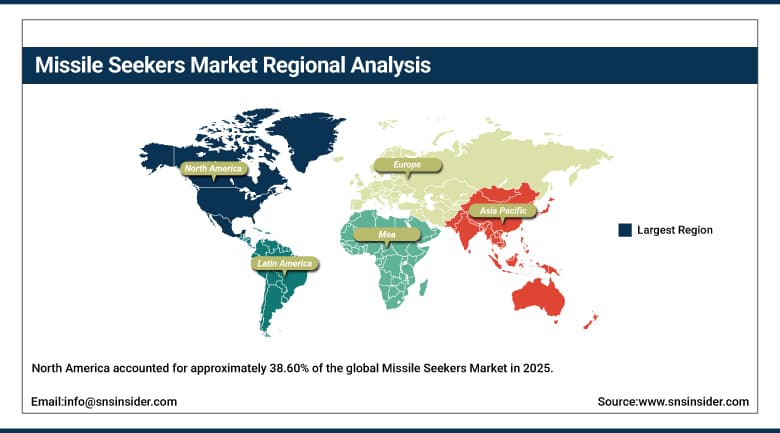
North America accounted for approximately 38.60% of the global Missile Seekers Market in 2025, making it the largest regional market, supported by the United States' position as the world's largest defense spender and home to the majority of leading missile prime contractors and seeker technology developers. Sustained congressional appropriations for munitions replenishment, combined with a deep and continuously expanding pipeline of next-generation missile development programs spanning hypersonic weapons, counter-UAS interceptors, and multimode precision-strike munitions, continues to reinforce North America's position as the anchor market for global seeker demand. The region's defense industrial base benefits from decades of accumulated seeker development expertise concentrated within a relatively small number of prime contractors, each maintaining extensive vertical integration across sensor design, signal processing, and final missile assembly that continues to reinforce genuine barriers to entry for prospective new competitors.
Canada is contributing incremental regional demand as its own defense modernization programs and participation in continental air-defense architecture continue to expand. Continued domestic investment in production capacity expansion, exemplified by recently announced multiyear, multibillion-dollar procurement agreements aimed at tripling certain interceptor production rates by the end of the decade, is expected to sustain North America's leading position through the forecast period, even as growth in percentage terms moderates relative to faster-expanding markets pursuing rapid indigenous defense industrial base development.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Missile Seekers Market Insights
Asia Pacific is the fastest-growing regional market, driven by escalating regional security tensions, sustained defense modernization investment, and the continued expansion of indigenous missile development programs across China, India, Japan, and South Korea. Rising territorial disputes and broader strategic competition across the region continue to drive substantial government investment in both offensive precision-strike capability and increasingly sophisticated layered air-defense architectures, each requiring dedicated seeker technology procurement at a pace that continues to outstrip growth in more mature Western defense markets. China's rapidly expanding domestic missile development and manufacturing base continues to anchor regional demand, supported by substantial state investment in indigenous seeker technology development aimed at reducing reliance on imported systems.
India's expanding indigenous defense manufacturing capability, reinforced by government policy explicitly prioritizing domestic missile and seeker technology production over imports, continues to contribute meaningful incremental regional growth. Japan and South Korea contribute additional scale through established defense electronics sectors increasingly integrating advanced seeker technology into both indigenous missile programs and license-produced Western systems, while continued regional security tensions across multiple flashpoints continue to reinforce sustained government appetite for expanded missile defense and precision-strike capability, positioning Asia Pacific to remain the fastest-growing regional market for missile seeker technology through the forecast period.
Europe Missile Seekers Market Insights
Europe represents a significant share of the global Missile Seekers Market, with regional demand substantially reinforced by the continent's evolving security environment and sustained multiyear defense spending increases across NATO member states responding to heightened regional security concerns. Germany's substantial defense industrial base, combined with the broader European push toward strengthening indigenous defense manufacturing capability and reducing reliance on non-European suppliers for critical munitions components, continues to anchor sustained regional seeker demand across both established and emerging missile programs. Regional defense contractors, including several long-established European missile prime contractors, continue to pursue collaborative development programs aimed at pooling research and development investment across multiple national defense ministries to accelerate next-generation seeker technology development.
The United Kingdom, France, and Italy contribute significant regional demand as national defense modernization programs continue to extend advanced seeker technology adoption across both air-defense and precision-strike munitions programs. Continued collaborative European defense procurement initiatives, aimed at achieving greater strategic autonomy in critical defense technology areas including missile guidance and seeker systems, are expected to sustain steady regional growth through the forecast period as European nations continue rebuilding depleted munitions stockpiles and modernizing legacy air-defense architectures inherited from prior decades.
MEA & Latin America Missile Seekers Market Insights
The Middle East & Africa market is driven significantly by consistent defense modernization spending in Israel, Saudi Arabia, and the United Arab Emirates, where continued regional security challenges persist, ensuring significant purchases of indigenous and imported missiles that rely on seeker technology by government entities. In Israel, there exists the recognized ability to design missiles and seekers in an indigenous fashion, and domestic defense companies continue exporting advanced seeker-equipped interceptors and precision-guided weapons to allied countries around the world, demonstrating the strategic significance of the region in relation to its market size.
The Latin America market is relatively small, but Brazil has been driving growth due to the gradual implementation of defense modernization programs in a less-than-lavish environment for defense spending compared to other regions of the world. Missile seeker technology continues to be analyzed by regional governments in terms of defense modernization strategy, but commercial-scale indigenous production of missile seekers in Latin America is still considerably less mature than in the more mature defense industry markets.
Market Dynamics
Growth Drivers: Defense Modernization and Precision-Strike Demand
Rising defense modernization programs represent the primary driver of Missile Seekers Market growth, as military forces worldwide continue procuring advanced missile systems requiring increasingly sophisticated seeker technology capable of reliable operation against ever more capable adversary countermeasures and evasion tactics. The growing need for precision-guided munitions in modern warfare continues to reinforce this trend, as military doctrine across virtually every major armed force increasingly prioritizes precision engagement capability over less discriminate munitions, both to minimize collateral damage and to maximize the operational and cost efficiency of increasingly expensive modern weapons systems. Regional security concerns, spanning territorial disputes, renewed great-power competition, and sustained regional conflicts, continue to drive substantial government defense spending increases that flow directly into expanded missile procurement programs requiring advanced seeker technology.
Increasing procurement of advanced missile systems represents a second major growth driver, as recent conflicts have vividly demonstrated both the strategic value and the sheer consumption rate of precision-guided munitions during sustained combat operations, prompting many nations to substantially expand standing munitions stockpiles well beyond prior peacetime procurement baselines. The rise in asymmetric warfare, combined with growing counter-air and anti-ship operational requirements across an increasingly contested global maritime and aerial environment, continues to reinforce sustained demand for increasingly capable, multi-mission seeker technology across virtually every major missile category and platform.
Restraints: Technical Complexity and Extended Development Timelines
Technical complexity represents a meaningful restraint on market growth, as developing seeker technology capable of reliably discriminating genuine targets from increasingly sophisticated decoys, electronic countermeasures, and cluttered battlefield environments continues to demand substantial, sustained research and development investment that only a limited number of established defense contractors possess the accumulated expertise and infrastructure to reliably deliver. This technical barrier to entry continues to concentrate the most advanced seeker development work among a relatively small number of established prime contractors, limiting the pace at which genuinely new competitive entrants can meaningfully challenge incumbent suppliers across the most demanding seeker technology categories.
Extended development and qualification timelines represent a further restraint, as new seeker technology must undergo rigorous, multiyear testing and certification processes before achieving operational deployment, a timeline that can meaningfully lag behind the pace at which adversary countermeasure technology continues to evolve. This qualification complexity continues to constrain how quickly seeker manufacturers can translate genuine technical innovation into fielded operational capability, occasionally leaving defense forces reliant on legacy seeker technology for longer than ideal while next-generation systems complete their full development and testing cycle.
Opportunities: Multi-Mode Seeker Innovation and Counter-UAS Technology Development
Continued advancement in multi-mode seeker technology represents a substantial opportunity, as manufacturers that can successfully combine infrared, radar, and laser sensing modalities within a single seeker package are positioned to capture demand from defense customers seeking genuinely improved target discrimination and countermeasure resistance across an increasingly contested electromagnetic and infrared battlespace. The growing adoption of multi-sensor fusion seekers for improved tracking and target discrimination continues to represent one of the clearest technology investment priorities across virtually every major missile development program worldwide, positioning manufacturers with genuine multi-mode integration expertise to capture disproportionate future program awards.
The continued development of dedicated counter-UAS seeker technology offers a further substantial avenue for growth, as the proliferation of low-cost unmanned aerial threats continues to create urgent, sustained procurement demand across virtually every major military power worldwide. Manufacturers that can deliver cost-effective, reliably discriminating seeker technology specifically optimized for small, slow, low-radar-cross-section target engagement are well positioned to capture significant new program awards as defense ministries worldwide continue racing to close this genuine and rapidly widening operational capability gap across both fixed installation and mobile force protection applications.
Recent Developments:
-
On May 11, 2026, Lockheed Martin's QuadStar missile successfully completed a Next-Generation Short-Range Interceptor seeker characterization test at White Sands Missile Range, New Mexico. The test displayed a 100% success rate in the missile seeker finding its designated target, marking a key milestone in the U.S. Army's competitive interceptor development program.
-
In 2025, Raytheon, an RTX Corporation business, was awarded a contract valued at USD 105.6 million for missile parts, funded jointly through fiscal 2025 missile procurement, weapons procurement, and Foreign Military Sales appropriations. The award was managed through the Air Force Lifecycle Management Center at Robins Air Force Base, Georgia.
Missile Seekers Market Key Players
-
Raytheon Technologies Corporation (RTX)
-
Lockheed Martin Corporation
-
Northrop Grumman Corporation
-
Thales Group
-
BAE Systems plc
-
Leonardo S.p.A.
-
Hensoldt AG
-
Saab AB
-
Rafael Advanced Defense Systems Ltd.
-
Elbit Systems Ltd.
-
The Boeing Company
-
MBDA
-
Diehl Defence GmbH & Co. KG
-
Aselsan A.S.
-
Analog Devices, Inc.
-
L3Harris Technologies, Inc.
-
Kongsberg Gruppen ASA
-
Bharat Dynamics Limited
-
Israel Aerospace Industries Ltd.
-
Mitsubishi Electric Corporation
Missile Seekers Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 5.20 Billion |
| Market Size by 2035 | USD 11.40 Billion |
| CAGR | CAGR of 8.17% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Seeker Type (Infrared, Active Radar, Semi-Active Laser, and Passive Radar) • by Missile Mission (Surface-to-Air & Air-Defense, Air-to-Air, Anti-Ship, and Counter-UAS) • by Component (Signal Processing & Electronics, Optics & Sensors, and Cooling & Thermal Management) • by Platform (Ground-Based, Airborne, and Naval) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Raytheon Technologies Corporation (RTX), Lockheed Martin Corporation, Northrop Grumman Corporation, Thales Group, BAE Systems plc, Leonardo S.p.A., Hensoldt AG, Saab AB, Rafael Advanced Defense Systems Ltd., Elbit Systems Ltd., The Boeing Company, MBDA, Diehl Defence GmbH & Co. KG, Aselsan A.S., Analog Devices, Inc., L3Harris Technologies, Inc., Kongsberg Gruppen ASA, Bharat Dynamics Limited, Israel Aerospace Industries Ltd., Mitsubishi Electric Corporation |

Frequently Asked Questions
Key players include Raytheon Technologies Corporation, Lockheed Martin Corporation, Northrop Grumman Corporation, Thales Group, BAE Systems plc, Leonardo S.p.A., and Hensoldt AG, among other defense prime contractors.
Continued advancement in multi-mode seeker technology and continued development of dedicated counter-UAS seeker technology represent the primary opportunities for manufacturers.
Growth is primarily driven by rising defense modernization programs combined with increasing procurement of advanced missile systems and growing need for precision-guided munitions.
By Seeker Type, Infrared dominated the market with approximately 38.60% share in 2025, reflecting wide deployment across air-to-air and anti-armor missile programs worldwide.
North America dominated the market with approximately 38.60% share in 2025, supported by the United States' position as the world's largest defense spender.
