
Nanowire Battery Market Report Scope & Overview:
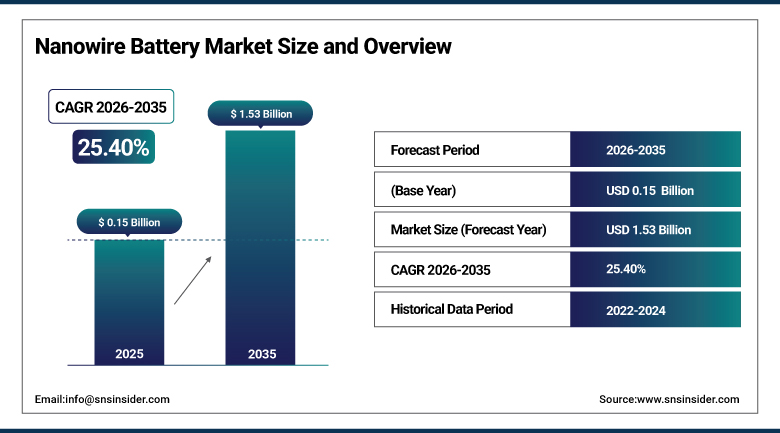
The Nanowire Battery Market was valued at USD 0.15 Billion in 2025 and is expected to reach USD 1.53 Billion by 2035, growing at a CAGR of 25.40% from 2026-2035.
The Nanowire Battery Market covers rechargeable batteries whose electrodes use nanowires, thin strands of silicon, germanium, metal oxides or other materials, to hold more lithium and swell less than standard graphite anodes. The result is higher energy density, faster charging and longer life. Products serve drones, consumer devices, aerospace, electric vehicles and storage. Growth is supported by demand for lighter, longer-lasting batteries, while high cost, scale-up risk and limited cycle life data shape adoption.
⮞In 2024, Amprius introduced SiCore, a commercially available silicon-anode battery platform offering up to 400 Wh/kg and 1,200 charge cycles. Its existing SiMaxx platform retained silicon nanowire technology, with reported energy density reaching 500 Wh/kg.
To Get more information Nanowire Battery Market - Request Free Sample Report
Nanowire Battery Market Trends
-
Silicon nanowire anodes that raise energy density in drone and aerospace cells
-
Fast-charging cells for electric vehicles and consumer devices
-
Hybrid nanostructures that combine silicon with carbon to reduce swelling
-
Scaling of pilot lines and contract manufacturing in South Korea and the United States
-
Defense funding for local drone and soldier-worn battery supply
-
Work on solid-state and sodium-ion designs using nanowire electrodes
U.S. Nanowire Battery Market Outlook
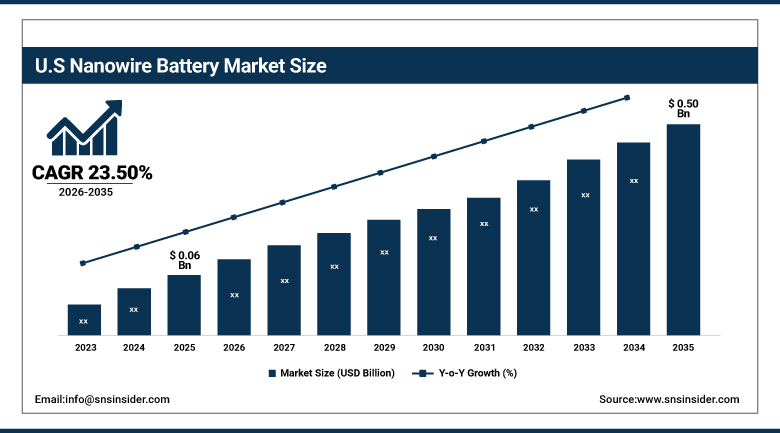
The U.S. Nanowire Battery Market was valued at USD 0.06 Billion in 2025 and is expected to reach USD 0.50 Billion by 2035, growing at a CAGR of 23.50% from 2026-2035.
The U.S. Nanowire Battery Market is the largest national market in the region, supported by a cluster of silicon anode start-ups, defense and drone programs, federal funding for battery supply chains and strong demand for high-energy cells in aerospace and electronics. Most output still goes to specialty and defense customers. Growth is moderated by high unit cost, limited volume capacity and competition from lower-cost silicon-graphite anodes.
⮞In September 2026, Amprius secured a US Department of War grant of up to $75 million to establish domestic high-volume manufacturing of advanced silicon-anode batteries. The project targets 12 million cells annually by early 2028.
Nanowire Battery Market Segment Analysis
-
By Electrode Material, silicon segment dominated the Nanowire Battery Market in 2025 with an estimated 66.00% share; transition metal oxides segment is the fastest-growing segment, with an estimated CAGR of 29.50% during 2026–2035.
-
By Battery Type, silicon nanowire anode segment dominated the Nanowire Battery Market in 2025 with an estimated 49.00% share; hybrid nanostructure segment is the fastest-growing segment, with an estimated CAGR of 30.00% during 2026–2035.
-
By Application, consumer electronics segment dominated the Nanowire Battery Market in 2025 with an estimated 38.00% share; aerospace and defense segment is the fastest-growing segment, with an estimated CAGR of 31.00% during 2026–2035.
By Electrode Material, Silicon Dominates Nanowire Battery Market; Transition Metal Oxides to Register Fastest Growth.
Silicon dominates the Nanowire Battery Market because it can store far more lithium than graphite, offering several times the theoretical capacity, and it is abundant and compatible with existing battery lines. Silicon nanowires let the material expand without cracking, which has been the main barrier to using it. Most commercial nanowire cells today use silicon anodes. Developers grow nanowires on current collectors or mix them into slurries, and processes such as chemical vapor deposition and etching are being adapted for larger volumes. Falling silane and precursor costs, and strong patent portfolios, shape who can scale. Quality control of wire length and diameter is critical for cell consistency.
Transition metal oxides are projected to register the fastest growth as researchers and developers use oxide nanowires for stable, long-life electrodes, supercapacitor hybrids and sodium or multi-valent ion cells. They offer good cycle stability and can be made with scalable methods, and early commercial interest is rising as developers look to diversify beyond silicon. Oxide nanowires such as vanadium, manganese and titanium compounds are also studied for stable cathodes, and universities and national labs partner with firms to move results into prototypes and early pilot batches.
By Battery Type, Silicon Nanowire Anode Dominates Nanowire Battery Market; Hybrid Nanostructure to Register Fastest Growth.
Silicon nanowire anode batteries dominate the Nanowire Battery Market because they are the most developed route to higher energy density, with cells already supplied for drones, high-altitude aircraft and specialty devices. Companies have shown energy densities well above conventional lithium-ion cells, and customers in defense and aerospace pay premiums for the weight savings. The design lets each wire swell and shrink without breaking the electrode, which is the main reason energy density and life improve. Cells have been shown to reach high energy per kilogram, although cycle life varies by design and customer duty cycle. Safety tests such as nail penetration and thermal abuse are required by customers.
Hybrid nanostructure batteries are projected to register the fastest growth as developers combine silicon with carbon, graphene or other materials to reduce swelling and improve cycle life. These designs are easier to produce on existing lines and may offer lower cost, making them attractive for electric vehicles and consumer products as they reach larger scale. Pre-lithiation, binders and electrolyte additives are being combined with hybrid anodes to keep first-cycle loss low. Partnerships between material suppliers and large cell makers speed adoption by testing on standard pouch and cylindrical formats.
By Application, Consumer Electronics Dominates Nanowire Battery Market; Aerospace and Defense to Register Fastest Growth.
Consumer electronics dominates the Nanowire Battery Market because phones, wearables, laptops and cameras value thin, light batteries with longer run times, and manufacturers pay for incremental gains in energy density. Silicon-rich anodes have appeared in premium devices, and nanowire designs are being tested for faster charging and smaller form factors. Product designers weigh battery volume against device thickness, and nanowire cells can hold more energy in the same space. Premium brands are willing to adopt new anode materials early if they provide visible gains in battery life. Short design cycles for devices speed adoption when cost targets are met.
Aerospace and defense is projected to register the fastest growth as drones, unmanned aircraft, satellites and soldier-worn equipment need the highest energy per kilogram. Governments are funding local supply of advanced cells, and suppliers are scaling pilot lines to fill orders. Customers accept higher prices for longer flight time and range. Satellite makers and high-altitude platforms also value low mass and stable performance across temperature ranges, and procurement budgets for military drones are increasing. Suppliers can win multi-year contracts with strong margins in this segment.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
South Korea |
31.00 |
|
North America |
United States |
90.00 |
|
Europe |
United Kingdom |
29.00 |
|
MEA |
Israel |
33.00 |
|
Latin America |
Brazil |
30.00 |
North America Nanowire Battery Market Insights
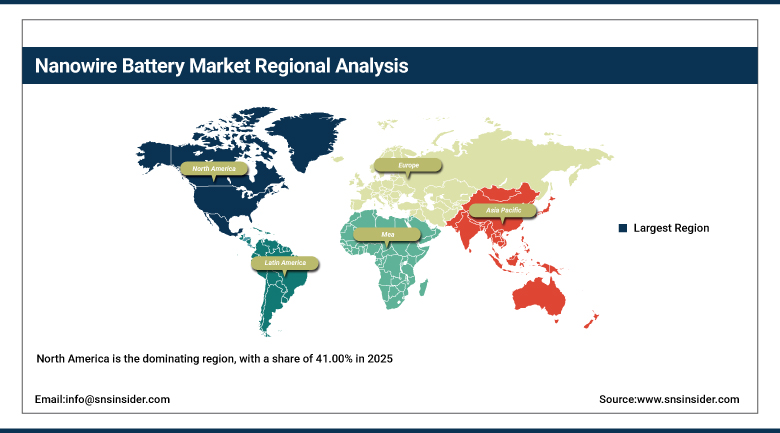
North America is the dominating region, with a share of 41.00% in 2025, and is projected to grow at a CAGR of 27.50% during 2026-2035. The United States accounts for about 90.00% of regional demand, with Canada adding volume. Amprius, Enovix, Sila, Enevate, OneD Battery Sciences, NanoGraf, Sion Power and Tesla serve the region. Funding from the Department of Defense, the Department of Energy and state programs supports pilot lines and local material supply, and several start-ups have listed on public markets, giving them access to capital for expansion. University spin-outs continue to feed new entrants into the market.
Start-ups backed by venture and government funding, and demand from defense, drone and aerospace buyers, drive the region. Federal programs support local battery supply chains. Small production volumes, high unit cost and the need to prove life and safety over time moderate growth, though pilot lines are expanding. Customers in drones, aerospace, medical devices and electric motorcycles are early adopters, and cooperation with contract manufacturers in Asia is helping suppliers scale without building all plants themselves. Defense primes are also qualifying nanowire cells for unmanned systems.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Nanowire Battery Market Insights
Europe is the third-largest region, with a share of 18.00% in 2025, and is projected to grow at a CAGR of 22.80% during 2026-2035. The United Kingdom, Germany, France and the Nordic countries lead regional demand. Nexeon, InoBat, Northvolt-linked suppliers, Varta, Umicore and research institutes serve the region. Universities in the United Kingdom, Germany and Scandinavia are active in nanowire and silicon anode research, and start-ups spin out with support from public innovation agencies. Automakers monitor progress for future platforms. Public tenders for defense electronics may include requirements for local battery supply.
Strong research, electric vehicle makers and rules on battery content support interest in advanced anodes. European drone and e-mobility firms are buying silicon-based cells from suppliers. Dependence on Asian cell supply, high energy costs and slow plant build-outs moderate growth. The EU Battery Regulation sets rules for carbon footprint, recycled content and passports, which affects how new materials are qualified. Drone and defense spending in several countries is creating new demand for high-energy cells. Nordic and German research alliances are also testing hybrid anodes for e-mobility.
Asia Pacific Nanowire Battery Market Insights
Asia Pacific shows growth with a share of 32.00% in 2025, and is projected to be the fastest-growing region, at a CAGR of 23.50% during 2026-2035. South Korea, China, Japan, Taiwan and India lead regional demand. LG Energy Solution, Samsung SDI, Panasonic, CATL, Group14 and NEO Battery Materials serve the region. South Korea accounts for about 22.00% of regional demand. South Korean cell makers are among the largest in the world and cooperate with material firms on silicon anode supply. Japan has long experience in battery materials, and Chinese firms are moving fast on silicon-carbon composites for consumer products. Strong electronics supply chains help firms move quickly from sample to mass production.
The region has the world's largest battery manufacturing base, deep materials supply and leading consumer electronics and electric vehicle makers. Silicon anode material plants are being built in South Korea and Japan, and cell makers test nanowire designs. High development cost, strict qualification and competition from lower-cost graphite anodes moderate growth. Government plans for battery industry leadership in Korea, Japan and China fund research, pilot plants and recycling. India is also building a battery ecosystem, creating future demand for advanced anodes in electric two-wheelers and storage.
⮞On March 12, 2026, Group14 Technologies began EV-scale production at its Sangju, South Korea factory, with capacity of up to 2,000 metric tons of SCC55 silicon battery material per year, enough for about 10 GWh of battery capacity. The material is a silicon-carbon composite, not a pure nanowire product.
MEA & Latin America Nanowire Battery Market Insights
In the Middle East and Africa, Israel, the United Arab Emirates, Saudi Arabia and Turkey lead demand, with growth of about 26.00% annually. Defense drone programs, solar-plus-storage projects and research centers create early demand, and Israel has a strong battery research base. Israel hosts a strong cluster of battery and materials start-ups, and defense procurement supports local suppliers. Gulf states are investing in advanced materials and energy storage as part of diversification programs. Pilot projects in solar storage are being tested in several countries.
In Latin America, Brazil, Chile and Mexico lead, with regional demand growing at about 25.00% annually. Lithium resources and growing electric vehicle and storage markets create future potential, though most advanced cells are imported and local manufacturing is limited. Brazil and Chile are positioning themselves in the lithium and battery value chain, and regional demand is expected to follow growth of electric buses and storage. Technology partnerships with suppliers will be important. Universities in Brazil are also running studies on silicon anode materials.
Market Dynamics
Growth Drivers: Energy Density Needs, Fast Charging and Defense Demand
Drones, aircraft and portable devices need more energy per kilogram, and nanowire anodes offer a clear path beyond graphite. Growth in electric aviation concepts and urban air mobility vehicles also creates demand for batteries with high energy per kilogram, a field where nanowire anodes have an advantage. Rising adoption of electric motorcycles, scooters and light vehicles needs batteries with fast charging and light weight, and these vehicles are a practical first market for new cell designs. Investor interest in next-generation batteries has stayed strong, with several firms raising capital to build pilot plants and secure feedstock, which supports a steady stream of new product announcements and partnerships through the forecast period. Standards for fast charging and energy labeling may also favor high-performance cells.
Fast charging for vehicles and phones and growing defense spending on drones and soldier systems add buyers willing to pay for better performance. Public funding for battery research and manufacturing in the United States, Europe and Asia lowers the risk of early investments. Customers in medical devices and robotics also value compact, long-lasting power sources, creating further segments for premium cells. Customers who need drones and aircraft with longer endurance, and electric motorcycles with fast charging, are ready to pay a premium today, which gives early producers revenue while costs fall. Wider use of battery swapping and rapid charging networks in Asia also encourages development of cells that tolerate high charge rates without losing capacity.
Restraints: High Cost, Scale-Up Risk and Limited Life Data
Nanowire materials cost more than graphite and need new equipment, and yields at larger scale are still being proven. Safety certification for new battery chemistries takes time, and failures in field use can damage the reputation of the entire category. Supply of high-purity silicon precursors and specialized equipment is limited, and a shortage can raise costs and delay new lines. Because suppliers are small and often unprofitable, buyers may worry about continuity of supply, and qualification of a new cell format can take over a year, delaying revenue for start-ups. Variation in test methods makes it hard for buyers to compare products from different suppliers.
Buyers want long cycle life and safety data, and silicon swelling still limits life in some designs. Competition from silicon-graphite and silicon-carbon anodes, which are cheaper and easier to scale, limits the premium that nanowire products can charge. Intellectual property disputes among developers could slow adoption or lead to licensing costs that reduce margins. Changes in tariffs and export controls on battery materials and equipment can also complicate cross-border supply chains and raise costs for developers. Customers also remain cautious about swelling, first-cycle losses and electrolyte compatibility, so they test samples for many months before placing volume orders.
Opportunities: Hybrid Designs, Contract Manufacturing and Solid-State Cells
Hybrid silicon-carbon designs and partnerships with large cell makers can bring nanowire benefits at lower cost. Licensing models and joint development agreements with large cell makers allow smaller firms to share the cost of scale-up and reach customers faster. Hybrid energy storage that combines nanowire electrodes with supercapacitor designs can serve grid support, rail and heavy equipment uses. Pairing nanowire electrodes with lithium-metal and sulfur chemistries could extend range and energy density further, and long-term research programs funded by governments are exploring these paths. Growth in high-altitude platforms and satellites that need lightweight batteries adds an application where nanowire cells can show clear advantages and secure premium contracts from space and defense customers.
Pairing nanowire anodes with solid-state or sodium-ion cells could open new markets in vehicles and storage. Recycling and reuse of silicon and other materials from spent cells can lower cost and help meet regulations on recycled content. Government procurement of local, secure battery supply for defense creates a stable base of demand for early producers. Tie-ups with consumer electronics brands and drone makers can provide early volume and feedback, helping suppliers refine products before approaching automakers. Grants from defense innovation offices can fund pilot lines and testing, lowering the cost of early scale-up for suppliers of specialty cells.
Recent Developments:
-
2022: Amprius Technologies received a $3 million contract from the United States Advanced Battery Consortium (USABC) to develop low-cost, fast-charging silicon nanowire batteries. The 30-month project targeted electric-vehicle cells exceeding 80 Ah.
-
2022: General Motors partnered with OneD Battery Sciences to research silicon-anode batteries for electric vehicles. The collaboration focused on SINANODE technology, which incorporates silicon nanowires into graphite to improve energy density, charging performance, and affordability.
Nanowire Battery Market Key Players are
-
Amprius Technologies, Inc.
-
Enovix Corporation
-
Sila Nanotechnologies Inc.
-
Group14 Technologies, Inc.
-
Nexeon Limited
-
OneD Battery Sciences
-
Enevate Corporation
-
NanoGraf Corporation
-
NEO Battery Materials Ltd.
-
LG Energy Solution, Ltd.
-
Samsung SDI Co., Ltd.
-
Panasonic Holdings Corporation
-
Contemporary Amperex Technology Co., Limited
-
Sion Power Corporation
-
24M Technologies, Inc.
-
Tesla, Inc.
-
XG Sciences, Inc.
-
NEI Corporation
-
InoBat
-
Sionic Energy
Nanowire Battery Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 0.15 Billion |
| Market Size by 2035 | USD 1.53 Billion |
| CAGR | CAGR of 25.40% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Electrode Material (Silicon, Germanium, Transition Metal Oxides, and Others) • By Battery Type (Silicon Nanowire Anode, Hybrid Nanostructure, and Others) • By Application (Consumer Electronics, Electric Vehicles, Aerospace and Defense, Energy Storage, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Amprius Technologies, Inc., Enovix Corporation, Sila Nanotechnologies Inc., Group14 Technologies, Inc., Nexeon Limited, OneD Battery Sciences, Enevate Corporation, NanoGraf Corporation, NEO Battery Materials Ltd., LG Energy Solution, Ltd., Samsung SDI Co., Ltd., Panasonic Holdings Corporation, Contemporary Amperex Technology Co., Limited, Sion Power Corporation, 24M Technologies, Inc., Tesla, Inc., XG Sciences, Inc., NEI Corporation, InoBat, Sionic Energy |

Frequently Asked Questions
Key players include Amprius Technologies, Inc., Enovix Corporation, Sila Nanotechnologies Inc., Group14 Technologies, Inc., Nexeon Limited, LG Energy Solution, Ltd., Samsung SDI Co., Ltd. and Panasonic Holdings Corporation.
Key opportunities include hybrid silicon-carbon designs, contract manufacturing and pairing nanowires with solid-state cells.
The major growth factor is demand for higher energy density and fast charging, especially in drones, defense and premium devices.
By Electrode Material, the Silicon segment dominated the market in 2025 with an estimated 66.00% share, as it stores far more lithium than graphite.
Asia Pacific dominated the market with a share of 41.00% in 2025, driven by the largest battery manufacturing base and leading electronics makers.
