
Next-generation Sequencing (NGS) Data Analysis Market Report Scope & Overview:
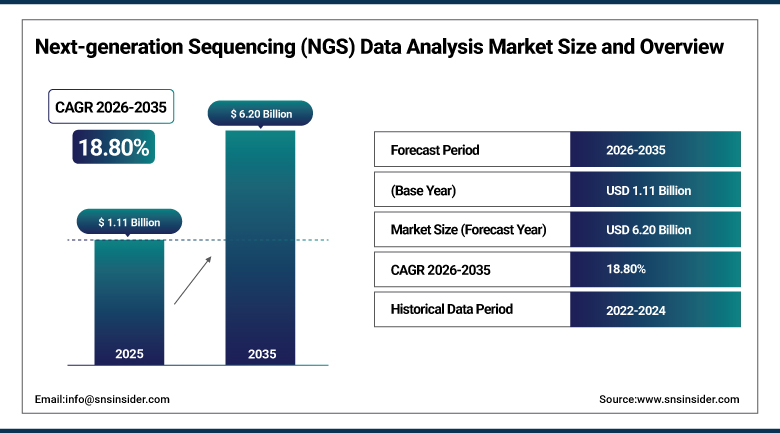
The Next-generation Sequencing (NGS) Data Analysis Market was valued at USD 1.11 Billion in 2025 and is expected to reach USD 6.20 Billion by 2035, growing at a CAGR of 18.80% from 2026-2035.
The Next-generation Sequencing (NGS) Data Analysis Market covers software, pipelines, and services that convert raw sequencer output into aligned reads, called variants, and clinical or biological interpretations. Primary analysis handles base calling, secondary analysis performs alignment and variant detection, and tertiary analysis annotates findings and links them to disease databases. Falling sequencing costs have shifted the bottleneck from generating data to interpreting it. Laboratories therefore buy commercial platforms, cloud workflows, and outsourced bioinformatics support to manage rising volumes in research, diagnostics, and drug development programs. Standards bodies and professional societies are also publishing guidance that shapes how pipelines are validated and reported.
⮞In June 2024, the European Bioinformatics Institute announced that its FIRE data archive had reached 100 petabytes. Archive growth at this scale illustrates the volume of data that analysis tools must process.
To Get more information Next-generation Sequencing (NGS) Data Analysis Market - Request Free Sample Report
Next-generation Sequencing (NGS) Data Analysis Market Trends
- Migration of sequencing pipelines to cloud and hybrid platforms
- GPU-accelerated secondary analysis shortening turnaround times
- Artificial intelligence models for variant effect prediction
- Growth of population-scale genome programs
- Integration of long-read and multiomic data into single workflows
U.S. Next-generation Sequencing (NGS) Data Analysis Market Outlook
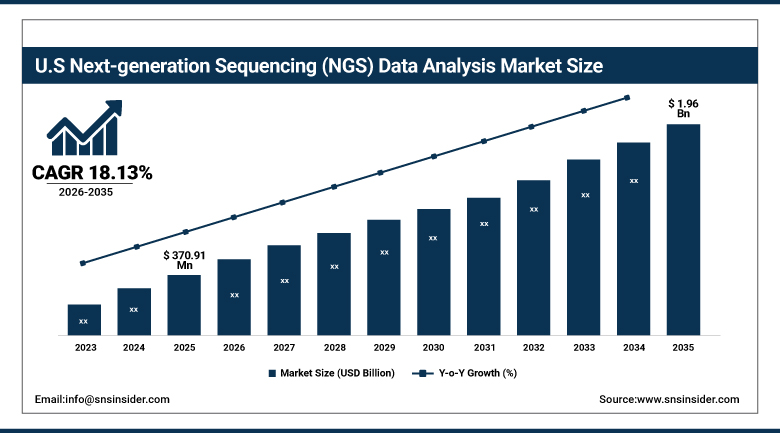
The U.S. Next-generation Sequencing (NGS) Data Analysis Market was valued at USD 370.91 Million in 2025 and is expected to reach USD 1.96 Billion by 2035, growing at a CAGR of 18.13% from 2026-2035.
The U.S. Next-generation Sequencing (NGS) Data Analysis Market is supported by large federal genomics programs, a dense network of academic medical centers, and the world's leading concentration of sequencing and bioinformatics companies. Hospitals use tumor and germline sequencing in routine oncology and rare disease care, which requires validated interpretation software. Pharmaceutical sponsors integrate genomic data into drug discovery and trial design. Cloud providers and specialist informatics firms compete to host pipelines, while clinical laboratories seek Food and Drug Administration cleared analysis tools. Data security expectations under health privacy rules shape product design. Reimbursement decisions by large insurers continue to influence which analyses laboratories choose to offer.
⮞In June 2026, the All of Us Research Program released more than 535,000 whole genome sequences containing over 1.3 billion genetic variants. Datasets of this size require scalable analysis infrastructure.
Next-generation Sequencing (NGS) Data Analysis Market Segment Analysis
- By Product, the Services segment dominated the Next-generation Sequencing (NGS) Data Analysis Market with approximately 54.10% share in 2025, while the NGS Commercial Software segment is the fastest growing with a CAGR of approximately 19.90%.
- By Read Length, the Short-Read segment dominated the Next-generation Sequencing (NGS) Data Analysis Market with approximately 70.89% share in 2025, while the Very Long-Read segment is the fastest growing with a CAGR of approximately 23.29%.
- By Application, the Clinical Diagnostics segment dominated the Next-generation Sequencing (NGS) Data Analysis Market with approximately 42.10% share in 2025, while the Agriculture and Animal Research segment is the fastest growing with a CAGR of approximately 21.40%.
- By End User, the Academic and Research Institutes segment dominated the Next-generation Sequencing (NGS) Data Analysis Market with approximately 52.60% share in 2025, while the Pharma and Biotech Companies segment is the fastest growing with a CAGR of approximately 19.40%.
By Product, Services Dominates the Next-generation Sequencing (NGS) Data Analysis Market and NGS Commercial Software Grows Fastest
Services account for the largest share of the market because many laboratories lack in-house bioinformatics staff and prefer to buy alignment, variant calling, and reporting as a managed offering. Contract genomics providers bundle sequencing with analysis, delivering ready-to-use results to clinicians and researchers. Custom pipeline development, data curation, and validation support add recurring revenue. Smaller hospitals and biotech start-ups in particular outsource analysis rather than hire specialists, which keeps service providers central to everyday project delivery across the field. Turnaround guarantees and quality certifications are common selling points in these contracts.
Commercial software is the fastest growing product group as sequencing volumes outgrow manual workflows. Licensed platforms offer graphical interfaces, audit trails, and regulatory documentation, which suit clinical laboratories. Subscription pricing and cloud deployment reduce upfront costs and let users scale compute on demand. Vendors are adding automated interpretation, population frequency filters, and links to treatment guidelines. As laboratories mature, many shift work in-house to protect sensitive data and cut per-sample costs, which directly benefits software suppliers. Integration with laboratory information systems further improves workflow efficiency for hospital customers.
⮞In July 2026, Amazon Web Services extended AWS HealthOmics private workflows to the Asia Pacific (Tokyo) and US East (Ohio) Regions. Wider regional availability of managed workflow engines supports adoption of cloud analysis.
By Read Length, Short-Read Dominates the Next-generation Sequencing (NGS) Data Analysis Market and Very Long-Read Grows Fastest
Short-read data hold the dominant position because sequencers using this chemistry remain the most widely installed and the lowest in cost per base. Mature tools exist for aligning and calling variants from short fragments, and clinical guidelines reference them extensively. Whole exome and targeted panels, the workhorses of diagnostic testing, rely on short reads. Large reference datasets and validated benchmark sets make results easy to compare across laboratories, which reinforces continued use. Cost advantages are particularly strong for large cohort projects with thousands of samples.
Very long-read analysis is expanding fastest as laboratories adopt instruments that span repeats and structural variants. These reads resolve complex regions, phase haplotypes, and detect methylation in a single run, answering questions that short fragments cannot. Software for assembly, structural variant calling, and base modification detection is maturing rapidly, and error rates keep falling. Rare disease programs and population studies increasingly add long-read sequencing to find causes missed by earlier tests, creating strong demand for specialized pipelines and visualization tools. Hybrid designs that combine short and long reads are also gaining attention among rare disease researchers.
By Application, Clinical Diagnostics Dominates the Next-generation Sequencing (NGS) Data Analysis Market and Agriculture and Animal Research Grows Fastest
Clinical diagnostics leads because sequencing now informs cancer treatment selection, rare disease diagnosis, prenatal screening, and infectious disease surveillance. Each test generates data that must be filtered, interpreted, and reported under quality systems, so laboratories rely on validated software. Reimbursement for panels and genomes has widened, which lifts sample counts. Hospital laboratories also need interpretation support from genetic specialists, creating sustained demand for decision support tools that rank variants and attach evidence from published studies. Quality management requirements add further reasons for laboratories to standardize on proven software.
Agriculture and animal research is advancing fastest from a smaller base as breeders and livestock producers apply genomic selection. Sequencing of crop varieties, pathogens, and herds produces large datasets that require specialized annotation resources. Climate pressure and food security goals encourage investment in resilient crops, while animal health programs use sequencing to trace outbreaks. Public research institutes and seed companies build bioinformatics teams, and software vendors extend their products to plant and animal reference genomes, widening the addressable market beyond human health. Open datasets from international breeding consortia help new entrants test and validate their tools.
⮞In May 2026, Datar Cancer Genetics reported FDA clearance of CellDx-Tissue, a tissue-based comprehensive genomic profiling assay covering 517 cancer genes. Cleared assays of this kind depend on validated analysis pipelines.
By End User, Academic and Research Institutes Dominates the Next-generation Sequencing (NGS) Data Analysis Market and Pharma and Biotech Companies Grows Fastest
Academic and research institutes hold the largest share because universities and public institutes generate the bulk of sequencing data through grants, consortia, and core facilities. They run large cohort studies and develop many of the open pipelines that others adopt. Core laboratories purchase commercial software and services to support multiple investigators at once. Training programs also keep demand steady, as new researchers learn on platforms that later influence purchasing decisions in industry and hospitals. Shared computing resources at national centers allow smaller groups to run large analyses.
Pharma and biotech companies are the fastest growing end users as sponsors integrate genomic evidence into target discovery, patient stratification, and companion diagnostic development. Large datasets from biobanks give drug developers new ways to validate targets, and in-house data science teams demand scalable, secure environments. Partnerships with analysis vendors and cloud providers speed up programs, while multiomic studies raise the volume per project. Competitive pressure to shorten development timelines encourages spending on automation and machine learning tools. Real-world genomic data licensed from health systems are also entering these workflows.
⮞In 2023, UK Biobank released whole genome sequence data for about 500,000 participants, and more than 300 research teams accessed it within the first two weeks. Release events like this drive academic demand for analysis platforms.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
80.00% |
|
Europe |
Germany |
24.80% |
|
Asia Pacific |
China |
30.15% |
|
Latin America |
Brazil |
48.90% |
|
Middle East & Africa |
Saudi Arabia |
31.25% |
North America Next-generation Sequencing (NGS) Data Analysis Market Insights
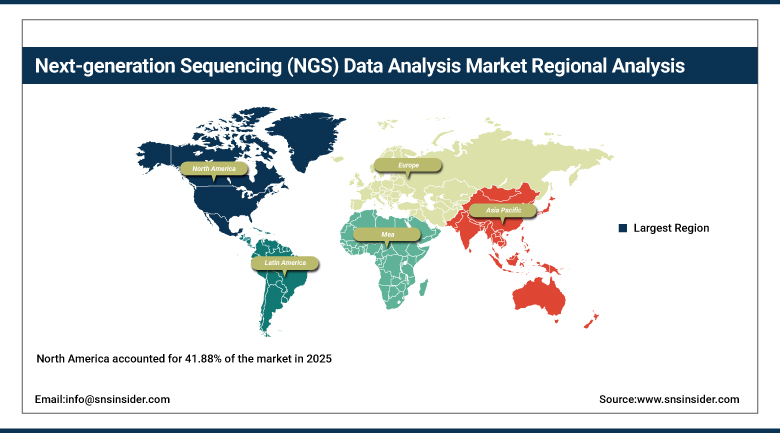
North America accounted for 41.88% of the market in 2025, holding first place on the strength of federal research funding, advanced healthcare infrastructure, and a strong base of bioinformatics vendors. The United States generates most regional demand, while Canada contributes through national precision health programs and academic genome centers. Venture capital supports start-ups in cloud genomics and artificial intelligence, and large technology companies offer dedicated life science platforms. Early adoption of clinical sequencing keeps analysis volumes high. Corporate research budgets in the region remain among the largest worldwide.
Collaboration between health systems, laboratories, and software firms shapes the regional landscape. Clinical teams adopt tumor boards supported by automated variant interpretation, while research consortia share data through secure cloud workspaces. Payers are widening coverage for genomic testing, which in turn raises sample counts. Regulatory expectations for software as a medical device influence product development, and vendors invest in compliance. A shortage of experienced bioinformaticians remains a concern, encouraging adoption of automated and low-code tools that reduce reliance on scarce specialists. Professional societies also publish interpretation standards that vendors align their products with.
⮞In March 2025, Genome Canada announced the Canadian Precision Health Initiative, aiming to build a public data resource of more than 100,000 human genomes with a total estimated investment of USD 200 million. Programs of this type expand the base of data to be analyzed.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Next-generation Sequencing (NGS) Data Analysis Market Insights
Europe ranks second, supported by national genomics programs, strong academic institutions, and growing clinical use of sequencing. Germany, the United Kingdom, France, and the Nordic countries lead adoption, and shared infrastructure for data access is being built across the European Union. Bioinformatics institutes in the region develop widely used open tools, which creates a skilled workforce and an active vendor ecosystem. Health systems are linking genomic results with electronic records to support precision medicine. Cross-border research networks add to the pool of users for shared analysis environments.
Data protection rules shape how genomic information may be stored and shared, pushing vendors to offer sovereign cloud options and federated analysis. Newborn sequencing pilots and rare disease programs increase demand for rapid, validated interpretation. Public procurement favors platforms with clear evidence and interoperability. Cooperation between countries on reference datasets and standards is gradually reducing fragmentation. Funding limits in some national systems slow roll-out, so adoption varies, but the overall direction toward routine genomic medicine is firmly established. Vendors that offer clear audit logs and consent management tools gain an edge in public tenders.
⮞In October 2025, Genomics England reported that 25,000 babies had joined its Generation Study, which screens for over 200 rare genetic conditions at more than 50 NHS sites. Newborn sequencing at scale adds to analysis workloads.
Asia Pacific Next-generation Sequencing (NGS) Data Analysis Market Insights
Asia Pacific is the fastest growing region with an expected CAGR of 19.91% from 2026 to 2035, led by China, Japan, India, Singapore, South Korea, and Australia. Government-backed genome projects, large patient populations, and expanding hospital sequencing capacity are lifting demand for analysis tools. Chinese companies supply sequencers and bioinformatics platforms at competitive prices, and Japanese and Korean institutions are building national biobanks. India is scaling population genomics through collaborative research consortia. Local technology companies are also entering the field with locally hosted analysis platforms.
Cloud adoption is accelerating as providers open regional data centers that meet local data residency rules. Singapore positions itself as a regional hub for precision medicine, while Australia has created a national genomics body to coordinate clinical services. Language and regulatory differences require localized products, which favors vendors with regional partners. Skills development remains uneven, so training programs and managed services are valuable. Rising public investment is expected to keep growth well above the global average through the forecast period. Telemedicine and remote genetic counseling services are emerging as complementary demand drivers.
⮞In November 2025, Tohoku University announced that whole genomes of 100,000 Japanese individuals had been sequenced in a decade-long cohort study. Population projects of this size set demand for scalable analysis.
MEA & Latin America Next-generation Sequencing (NGS) Data Analysis Market Insights
Latin America is building capacity through public genomics programs and university research centers in Brazil, Mexico, Argentina, and Chile. Mexico belongs to this region in market estimates, and its institutes collaborate with international consortia on population studies. Limited budgets and a shortage of bioinformatics staff slow adoption, so many laboratories depend on cloud services and outsourced analysis. Public health sequencing of pathogens has also created familiarity with pipelines that can be extended to human genomics. Regional training initiatives are helping to widen the base of qualified analysts.
The Middle East and Africa region is led by Gulf states that fund national genome programs to address inherited disease burdens. Qatar, Saudi Arabia, and the United Arab Emirates are investing in sequencing centers and local data platforms, while Africa shows growing research activity through collaborative consortia. Data sovereignty concerns encourage local hosting. Partnerships with international technology providers help transfer skills. Infrastructure and funding gaps remain across much of Africa, so progress in the wider region will be uneven over the next decade. Medical cities and flagship hospitals are the most likely early adopters of advanced analysis tools.
Market Dynamics
Growth Drivers: Falling Sequencing Costs and Faster Computing Drive Growth in the Next-generation Sequencing (NGS) Data Analysis Market
Lower sequencing costs have multiplied the amount of data produced, and each additional genome needs analysis. As sequencing spreads from research to routine clinical care, the number of samples passing through pipelines grows quickly. Laboratories seek automation to keep reporting times short and to maintain quality across thousands of cases. Software that reduces manual review and standardizes interpretation has therefore become a necessary part of the sequencing workflow rather than an optional extra. Reimbursement for genome-scale tests further encourages laboratories to scale up their analysis capacity.
Advances in computing are a second driver. Graphics processor acceleration compresses hours of alignment and variant calling into minutes, which makes same-day results feasible for urgent cases. Cloud platforms let smaller laboratories rent capacity instead of buying clusters. Faster pipelines also make it practical to rerun analyses as knowledge improves, supporting reanalysis of unsolved cases. These capabilities lower the barrier to entry for new users and are expected to widen the customer base over the forecast period. Open-source workflow languages also help laboratories move pipelines between platforms without rewriting code.
⮞In March 2025, NVIDIA reported that Parabricks 4.5 completed germline analysis in 7 minutes 56 seconds on four GPUs. Speeds of this kind change what clinical turnaround can look like.
Restraints: Data Security Rules, Skills Shortages, and Storage Burdens Restrain Growth in the Next-generation Sequencing (NGS) Data Analysis Market
Privacy and security requirements add cost and complexity. Genomic data are identifying by nature, and laws in many jurisdictions restrict where they may be stored and who may access them. Vendors must obtain certifications, build regional hosting, and manage consent records. Cross-border research collaborations face particular hurdles when data cannot leave a country. Such constraints can delay deployments and discourage smaller institutions from adopting cloud platforms, even where the technical benefits are clear. Insurance and audit costs related to data breaches add to the compliance burden.
Skills and storage form a second set of constraints. Bioinformaticians and clinical geneticists are in short supply, and interpretation of variants remains labor intensive. Raw sequence files are large, and long-term retention increases storage and backup costs. Pipelines also differ across laboratories, making results hard to compare. Validation of software for clinical use takes time and money. Together these factors tend to slow the pace of adoption among smaller hospitals and laboratories with limited budgets. Tiered storage and compression methods offer partial relief but need careful governance.
⮞In April 2025, the National Institutes of Health issued notice NOT-OD-25-083, barring institutions in countries of concern, including China and Russia, from access to its controlled-access data repositories. Access rules such as this complicate global data sharing.
Opportunities: Artificial Intelligence and Multiomics Create Opportunities in the Next-generation Sequencing (NGS) Data Analysis Market
Artificial intelligence offers a large opportunity in the interpretation step, where most clinical time is spent. Models trained on vast sequence collections can predict the effect of variants in noncoding regions, prioritize candidates in rare disease cases, and suggest regulatory mechanisms. Vendors that embed such models into reviewed, auditable workflows can improve diagnostic yield and reduce analyst workload. Pharmaceutical companies also seek these tools to identify targets, so licensing and partnership revenue is plausible. Regulators are beginning to outline expectations for transparency in algorithms used for clinical decisions.
Multiomics is a second opening. Combining genome, transcriptome, proteome, and methylation data gives a fuller picture of disease, but integrating them requires sophisticated software. Platforms that harmonize these layers and offer visual exploration will attract research and pharma users. Single-cell and spatial datasets add further volume. Companies that can deliver unified, scalable environments, ideally with clinical grade reporting, stand to capture new budgets as laboratories move beyond single-assay studies. Open standards for data exchange will determine how easily different tools can work together.
Recent Developments:
- In January 2026, Illumina completed the acquisition of SomaLogic from Standard BioTools for USD 350 million in cash at closing, plus up to USD 75 million in milestones and royalties. The deal adds proteomics to its multiomic offering and its analysis software portfolio.
- In June 2026, Roche launched AXELIOS 1, its first sequencing platform built on SBX technology, delivering reads of up to about 1,500 base pairs and same-day whole-genome results. The platform ships with the open-source XOOS analysis suite for research use.
- In February 2026, Ultima Genomics introduced the UG200 series and Solaris 2.0 workflows, with the UG200 Ultra priced at USD 1.25 million and capable of sequencing over 60,000 genomes a year. Shipments began in the second quarter of 2026.
- In August 2026, Pacific Biosciences began a global rollout of SPRQ-Nx chemistry, with whole-genome sequencing at a list price of USD 345 per genome. The company also began work on its largest population-scale program with Basecamp Research.
Next-generation Sequencing (NGS) Data Analysis Market Key Players are:
- Illumina
- Thermo Fisher Scientific
- QIAGEN
- Agilent Technologies
- F. Hoffmann-La Roche
- Bio-Rad Laboratories
- Pacific Biosciences
- DNAnexus
- Partek
- DNASTAR
- Golden Helix
- PierianDx
- Fabric Genomics
- Congenica
- SciGenom Labs
- Eurofins Scientific
- Velsera (Seven Bridges)
- Oxford Nanopore Technologies
- BGI Genomics
- 10x Genomics
Next-generation Sequencing (NGS) Data Analysis Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 1.11 Billion |
| Market Size by 2035 | USD 6.20 Billion |
| CAGR | CAGR of 18.80% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product (Services and NGS Commercial Software) • By Read Length (Short-Read, Long-Read, and Very Long-Read) • By Application (Clinical Diagnostics, Drug Discovery, Agriculture and Animal Research, and Others) • By End User (Academic and Research Institutes, Hospitals and Clinics, Pharma and Biotech Companies, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Illumina, Thermo Fisher Scientific, QIAGEN, Agilent Technologies, F. Hoffmann-La Roche, Bio-Rad Laboratories, Pacific Biosciences, DNAnexus, Partek, DNASTAR, Golden Helix, PierianDx, Fabric Genomics, Congenica, SciGenom Labs, Eurofins Scientific, Velsera (Seven Bridges), Oxford Nanopore Technologies, BGI Genomics, 10x Genomics |

Frequently Asked Questions
Key players in the market include Illumina, Thermo Fisher Scientific, QIAGEN, Agilent Technologies, F. Hoffmann-La Roche, and DNAnexus, among others.
Key opportunities include artificial intelligence for variant interpretation and multiomics platforms that unify genomic, transcriptomic, and proteomic data.
Falling sequencing costs and faster computing are the major growth factors, as larger data volumes require automated and scalable analysis.
The Services segment dominated the market in 2025 with approximately 54.10% share, as many laboratories lack in-house bioinformatics staff and prefer managed analysis.
North America dominated the market in 2025 with approximately 41.88% share, supported by federal research funding, advanced healthcare infrastructure, and a strong base of bioinformatics vendors.
