
Oil and Gas Security and Service Market Report Scope & Overview:
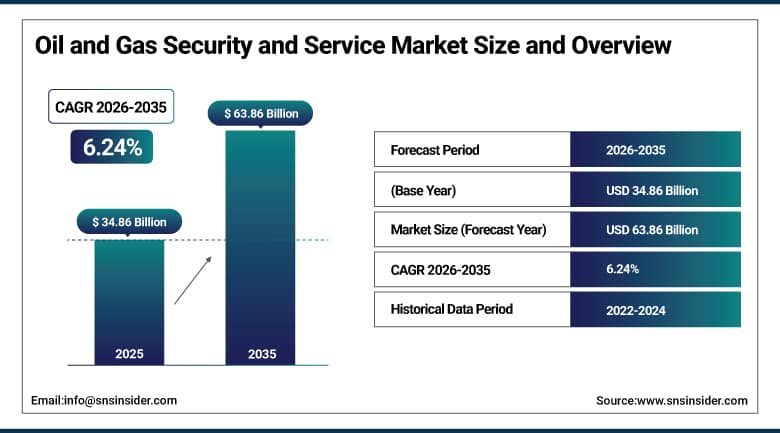
The Oil and Gas Security and Service Market was valued at USD 34.86 Billion in 2025 and is expected to reach USD 63.86 Billion by 2035, growing at a CAGR of 6.24% from 2026-2035.
The Oil and Gas Security and Service Market continues to expand as operators protect refineries, pipelines, offshore platforms, terminals, and digital control systems from physical attacks, cyber threats, theft, and sabotage. Oil and gas infrastructure is critical to national energy security and is frequently targeted by state-sponsored hackers, ransomware groups, militants, and criminal networks. Drone attacks on refineries, pipeline sabotage, fuel theft, and intrusions into operational technology networks have heightened awareness of risks across the value chain. Companies are investing in perimeter security, video surveillance, access control, intrusion detection, drone detection, and integrated command centers, along with industrial cybersecurity solutions for SCADA, distributed control systems, and safety instrumented systems.
⮞Industrial cybersecurity capability building in the Middle East advanced when the Operational Technology Cybersecurity Center of Excellence, a partnership between Aramco and the Global Cybersecurity Forum, hosted, in September 2026, an OT cybersecurity hackathon in Dhahran where 40 teams developed prototypes and threat models for critical industrial systems.
To Get More Information On Oil and Gas Security and Service Market - Request Free Sample Report
Oil and Gas Security and Service Market Trends:
-
Rising adoption of OT cybersecurity platforms for SCADA and control systems.
-
Growing deployment of counter-drone systems at refineries and terminals.
-
Expanding use of AI-driven video analytics for perimeter and pipeline monitoring.
-
Increasing demand for managed OT security operations centers.
-
Rising integration of physical and cyber security into unified command centers.
-
Growing compliance requirements under pipeline security and NIS2 regulations.
U.S. Oil and Gas Security and Service Market Outlook:
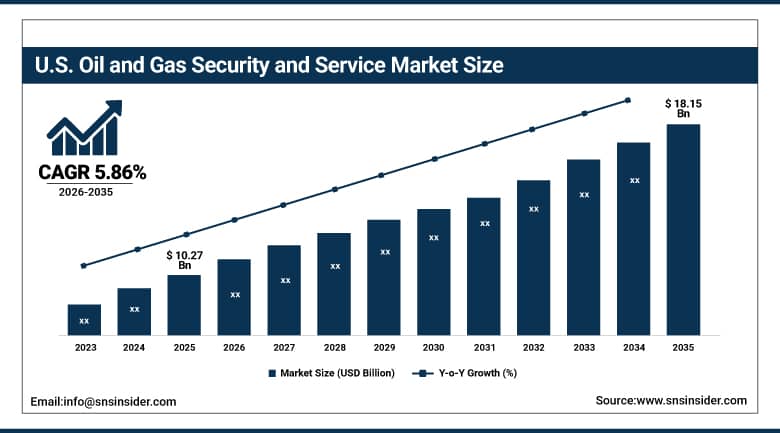
The U.S. Oil and Gas Security and Service Market was valued at USD 10.27 Billion in 2025 and is expected to reach USD 18.15 Billion by 2035, growing at a CAGR of 5.86% from 2026-2035.
The U.S. Oil and Gas Security and Service Market continues to grow on the strength of strict pipeline security regulations, rising cyber threats to energy infrastructure, and the scale of the country's oil and gas operations. The Transportation Security Administration's pipeline security directives, issued after the Colonial Pipeline ransomware attack, require operators to implement cybersecurity measures, incident response plans, and network segmentation. Threat groups such as VOLTZITE have targeted U.S. midstream pipeline operations, highlighting risks to operational technology. Operators in Texas, Louisiana, Oklahoma, Pennsylvania, and the Gulf of America invest in surveillance, access control, intrusion detection, and drone detection for refineries, LNG terminals, and offshore platforms. Honeywell, Cisco, Rockwell Automation, Emerson, Dragos, Claroty, and Nozomi Networks provide industrial cybersecurity solutions and services.
⮞Industrial cybersecurity offerings for U.S. energy operators expanded when Honeywell strengthened, in June 2026, its OT Cybersecurity Suite with five new capabilities, including an AI-powered Cyber Proactive Defense tool, a Secure Media Exchange portable scanner, data diodes, and a vendor-agnostic managed OT Security Operations Center providing 24/7 monitoring.
Oil and Gas Security and Service Market Segment Analysis:
-
By Component, the Solutions segment dominated the Oil and Gas Security and Service Market with approximately 58.42% share in 2025, while the Services segment is the fastest growing with a CAGR of approximately 7.48%.
-
By Security Type, the Physical Security segment dominated the Oil and Gas Security and Service Market with approximately 54.26% share in 2025, while the Network Security segment is the fastest growing with a CAGR of approximately 8.12%.
-
By Operation, the Upstream segment dominated the Oil and Gas Security and Service Market with approximately 41.36% share in 2025, while the Midstream segment is the fastest growing with a CAGR of approximately 7.24%.
-
By Deployment, the On-Premises segment dominated the Oil and Gas Security and Service Market with approximately 62.48% share in 2025, while the Cloud segment is the fastest growing with a CAGR of approximately 9.36%.
By Component, Solutions Dominate the Oil and Gas Security and Service Market and Services Grow Fastest
Solutions led the market in 2025, as oil and gas operators invest heavily in surveillance cameras, perimeter intrusion detection, access control, fire and gas detection integration, firewalls, OT network monitoring, and identity management systems. Security budgets increasingly cover both physical and cyber protection. These solutions protect large and remote facilities such as refineries, pipelines, offshore platforms, and LNG terminals from physical and cyber threats. Integrated security platforms from Honeywell, Siemens, Johnson Controls, Cisco, and Hexagon combine video, sensors, and analytics. The scale and complexity of oil and gas infrastructure continue to secure solutions as the largest component segment in the market over the forecast period.
⮞June 2026: Dragos and Accenture announced an industrial cybersecurity platform integrating Dragos’ OT security capabilities with Microsoft Azure and Microsoft Sentinel. The offering expands access to cybersecurity technology for critical infrastructure, including energy operators.
Services are the fastest-growing component as operators increasingly rely on managed security, risk assessment, consulting, system integration, and incident response services. Service contracts often span multiple years and asset locations. Many oil and gas companies face shortages of skilled cybersecurity professionals with operational technology expertise, encouraging outsourcing to specialized providers. Managed OT security operations centers, such as those offered by Honeywell, Dragos, and other providers, deliver 24/7 monitoring and threat detection. Compliance with pipeline security directives and NIS2 requirements also drives demand for audits and assessments. Rising threat complexity and limited internal resources continue to drive the fastest growth in the services segment.
By Security Type, Physical Security Dominates the Oil and Gas Security and Service Market and Network Security Grows Fastest
Physical security led the market in 2025, as oil and gas facilities require extensive protection against intrusion, theft, vandalism, sabotage, terrorism, and drone attacks. Physical security typically represents the largest share of security budgets at major facilities. Refineries, pipelines, storage terminals, and offshore platforms cover large areas and are often located in remote or high-risk regions. Operators deploy fencing, perimeter intrusion detection, thermal and video surveillance, access control, security personnel, and counter-drone systems. The March 2026 drone attack on a major Gulf refinery underscored physical threats to energy infrastructure. Large asset footprints continue to secure physical security as the largest security type segment in the market.
Network security is the fastest-growing security type as digitalization, remote operations, and IT-OT convergence expose control systems to cyber threats. Insurers increasingly require evidence of OT security controls before providing coverage to operators. Ransomware attacks, state-sponsored intrusions, and attacks on pipeline and refinery operations have increased awareness of cybersecurity risks. Operators are investing in OT network monitoring, segmentation, secure remote access, endpoint protection, and threat intelligence from Nozomi Networks, Claroty, Dragos, Fortinet, and Palo Alto Networks. Regulatory requirements and insurance conditions increasingly mandate cybersecurity controls. The growing sophistication of cyber threats continues to drive the fastest growth among security type segments in the market.
⮞December 2025: China’s National Energy Administration issued the Trial Measures for Energy Industry Data Security Management, effective July 2026. The measures establish data-security requirements for energy-sector activities, reinforcing the importance of protecting sensitive operational and digital information.
By Operation, Upstream Dominates the Oil and Gas Security and Service Market and Midstream Grows Fastest
Upstream operations led the market in 2025, as exploration and production sites, offshore platforms, and drilling rigs require comprehensive physical and cyber protection. Offshore platforms also require specialized maritime and helideck security. Upstream assets are often located in remote, offshore, or politically unstable regions where risks of attack, kidnapping, and theft are elevated. Operators invest in perimeter security, personnel protection, maritime security, and secure communications. Digital oilfield technologies and remote operations centers increase cybersecurity needs for upstream control systems. The large number of upstream assets worldwide continues to secure upstream operations as the largest operation segment in the oil and gas security and service market.
Midstream operations are the fastest-growing segment as pipelines, storage terminals, LNG facilities, and gas processing plants face rising physical and cyber threats. Many midstream operators are also adopting drone-based pipeline patrols and fiber optic intrusion sensing. Pipelines span thousands of miles and are vulnerable to tapping, sabotage, and attacks on SCADA systems that control flow and pressure. Threat groups such as VOLTZITE have specifically targeted midstream pipeline operations in the United States. Pipeline security directives require operators to strengthen cybersecurity and incident response. Expansion of LNG export capacity and new pipeline projects continues to drive the fastest growth among operation segments in the market.
⮞June 2026: China’s National Energy Administration held its annual oil and gas infrastructure planning and pipeline-protection meeting, emphasizing risk prevention, control of third-party construction near pipelines, and the use of AI and drone patrols where suitable. These measures support pipeline monitoring and protection across extensive transmission networks.
By Deployment, On-Premises Dominates the Oil and Gas Security and Service Market and Cloud Grows Fastest
On-premises deployment led the market in 2025, as oil and gas operators prefer to keep security systems for critical infrastructure under direct control within their facilities and private networks. Safety and reliability concerns also favor local hosting of security systems. On-premises video management, access control, and OT security systems offer low latency and continued operation when external connectivity is limited. Many operators also face regulatory and data sovereignty requirements that favor local hosting. National oil companies in particular maintain sensitive security data on-premises. Concerns about exposing control systems to external networks continue to secure on-premises deployment as the largest deployment segment in the market.
⮞June 2026: China’s National Data Administration documented an oil-and-gas pipeline data-protection initiative by PipeChina that uses a trusted data space and data-classification controls to manage secure sharing of electricity-use information among organizations. The example illustrates the need to retain governance and control over sensitive operational data.
Cloud deployment is the fastest-growing segment as operators adopt cloud-based security analytics, video surveillance management, threat intelligence, and managed security services. Video data volumes from large facilities are particularly well suited to cloud storage. Cloud platforms enable centralized monitoring of geographically dispersed assets, faster deployment of updates, and scalable data storage for video and security logs. AI-driven analytics in the cloud improve threat detection across large asset portfolios. Hybrid architectures that keep control system protection local while sending security data to cloud platforms are becoming common. Growing confidence in cloud security and the need for centralized visibility continue to drive the fastest growth in the cloud segment.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
84.62% |
|
Asia Pacific |
China |
36.48% |
|
Europe |
United Kingdom |
22.86% |
|
Latin America |
Brazil |
38.64% |
|
Middle East & Africa |
Saudi Arabia |
34.82% |
North America Oil and Gas Security and Service Market Insights
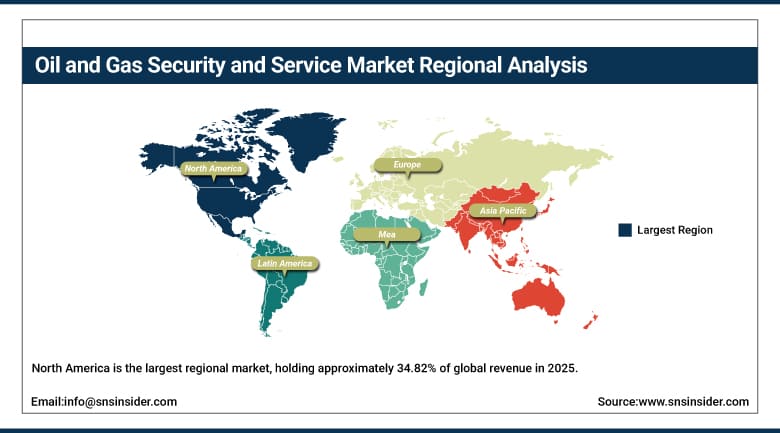
North America is the largest regional market, holding approximately 34.82% of global revenue in 2025, supported by extensive oil and gas infrastructure, strict pipeline security regulations, and high adoption of advanced security technologies. Operators in the region also face growing scrutiny from regulators and insurers regarding cybersecurity readiness and incident response capabilities. The region has the world's largest pipeline network, major refining and petrochemical complexes, and fast-growing LNG export capacity. Honeywell, Cisco, Rockwell Automation, Emerson, Johnson Controls, Dragos, Claroty, and Nozomi Networks serve operators across the region. Rising cyber threats against energy infrastructure and federal cybersecurity requirements continue to encourage investment in both physical and network security.
The United States anchors regional demand through security investment by pipeline operators, refiners, LNG exporters, and offshore producers, driven by TSA pipeline security directives and growing threat activity. Fuel theft remains a costly challenge for Mexican pipeline operators. Canada contributes through oil sands operations in Alberta, pipelines, and LNG projects in British Columbia that require physical and cyber protection. Mexico faces significant fuel theft from pipelines, prompting Pemex to invest in monitoring, surveillance, and security services. Continued infrastructure expansion, regulatory compliance, and rising cyber risks are expected to keep North America the largest regional market for oil and gas security and services.
⮞June 2026: The U.S. Department of Energy’s oil and natural gas security exercises focused on testing emergency procedures and coordination among operators. The initiative reflects continued attention to preparedness against cyber intrusions and physical threats affecting U.S. energy infrastructure.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Oil and Gas Security and Service Market Insights
Asia Pacific is the fastest-growing regional market, holding approximately 24.62% of global revenue in 2025 and expanding at a CAGR of approximately 7.36% from 2026 to 2035. Regional national oil companies are also partnering with international security technology providers to modernize surveillance, access control, and OT cybersecurity across refineries, pipelines, and offshore facilities. The region's growth reflects rising energy demand, expanding refining and petrochemical capacity, new LNG import terminals, and increasing cyber threats to critical infrastructure. China is investing in security for pipelines, refineries, and strategic petroleum reserves through state-owned companies such as Sinopec, PetroChina, and CNOOC, while regional governments strengthen critical infrastructure protection regulations.
⮞November 2025: China’s National Data Administration highlighted high-quality datasets for oil and gas pipeline protection. The initiative uses structured data resources to improve AI-based risk assessment and pipeline-protection capabilities, illustrating the growing role of data analytics in energy infrastructure security.
India is a major growth contributor, as Indian Oil, Reliance Industries, ONGC, and GAIL expand refining, pipelines, and city gas distribution networks that require physical and cyber security. Regional governments are also tightening critical infrastructure security requirements for energy operators. Australia's LNG export facilities and offshore operations invest in advanced security and cybersecurity under the Security of Critical Infrastructure Act. Malaysia, Indonesia, and Thailand are strengthening security for offshore platforms and refineries. Japan and South Korea focus on securing LNG import terminals and refining complexes. Rising infrastructure investment and evolving regulations are expected to keep Asia Pacific the fastest-growing regional market.
Europe Oil and Gas Security and Service Market Insights
Europe holds a significant share of the Oil and Gas Security and Service Market, supported by the EU NIS2 Directive, the Critical Entities Resilience Directive, and heightened concerns about sabotage of energy infrastructure. European operators also face heightened physical risks linked to regional conflicts, prompting stronger perimeter protection and surveillance at refineries, terminals, and pipelines. The United Kingdom is a leading country market, with North Sea offshore operations, refineries, and LNG terminals requiring advanced physical and cyber protection. Norway, the Netherlands, Germany, and Italy are also investing heavily in security for pipelines, offshore platforms, and LNG import terminals, while Siemens, Thales, ABB, and Schneider Electric provide key technologies and services.
⮞May 2026: The United Kingdom published its Energy Sector Cyber Security Strategy, establishing a four-year roadmap to improve energy-system resilience, strengthen cyber-risk oversight, and enhance incident response. The strategy includes oil and upstream gas within the UK’s energy cybersecurity regulatory framework.
Damage to subsea pipelines and cables in the Baltic Sea and North Sea has prompted European governments and operators to strengthen monitoring and protection of offshore infrastructure. Insurers are also tightening cyber coverage requirements for energy companies. New LNG import terminals built to replace Russian pipeline gas require comprehensive security systems. NIS2 expands cybersecurity obligations to more energy companies and introduces stricter incident reporting requirements. Operators are deploying underwater surveillance, drone detection, and OT security monitoring. Strong regulatory requirements and heightened geopolitical risks are expected to keep Europe a significant regional market for oil and gas security and services over the forecast period.
MEA & Latin America Oil and Gas Security and Service Market Insights
The Middle East & Africa represents a significant market, led by Saudi Arabia, the United Arab Emirates, Qatar, Kuwait, and Nigeria. Gulf operators are also building specialized OT security capabilities and local talent pipelines. Gulf oil and gas infrastructure faces elevated physical threats, including drone and missile attacks, as demonstrated by the March 2026 attack on the Ras Tanura refinery. Saudi Aramco, ADNOC, QatarEnergy, and Kuwait Oil Company invest heavily in physical security, counter-drone systems, and OT cybersecurity, supported by initiatives such as Aramco's OT Cybersecurity Center of Excellence. In Africa, Nigeria faces pipeline vandalism and oil theft that require extensive security services.
⮞October 2026: Saudi Aramco’s remarks at the Energy Intelligence Forum addressed attacks on energy facilities and emphasized the importance of resilience and cybersecurity. This highlights the strategic importance of protecting regional oil and gas infrastructure, although the speech did not announce a new security-system deployment.
Latin America is developing steadily, supported by Brazil, Mexico, Colombia, and Argentina. Regional operators are also adopting satellite and drone surveillance for remote pipelines. Brazil's Petrobras invests in security for offshore pre-salt platforms, refineries, and pipelines, along with cybersecurity for its digital operations. Mexico's fuel theft problem has driven investment in pipeline monitoring and security services. Colombia faces attacks on oil pipelines by armed groups, requiring physical security and rapid repair capabilities. Argentina's Vaca Muerta development adds new infrastructure requiring protection. Rising security risks and infrastructure expansion are expected to support steady growth across both regions over the forecast period.
⮞November 2025: Brazil’s National Agency of Petroleum, Natural Gas and Biofuels changed how it publishes operational safety incident data, making operator and installation details available following incident notifications rather than waiting for investigations to conclude. The change strengthens transparency around operational risks across Brazil’s oil and gas sector.
Market Dynamics:
Growth Drivers: Rising Cyber Threats to Operational Technology and Increasing Physical Attacks on Energy Infrastructure
Rising cyber threats to operational technology represent the primary driver of Oil and Gas Security and Service Market growth, as state-sponsored groups, ransomware gangs, and hacktivists increasingly target control systems that run pipelines, refineries, and offshore platforms. Energy companies are now among the most targeted sectors for cyberattacks. Dragos reported a surge in OT threat groups and ransomware activity in its 2026 review, including VOLTZITE targeting U.S. midstream pipeline operations. Successful attacks can halt production, damage equipment, and threaten safety. Growing IT-OT convergence, remote access, and connected sensors expand the attack surface, prompting operators to invest in OT network monitoring, segmentation, and managed security services.
Increasing physical attacks on energy infrastructure are further strengthening market growth, as drone strikes, sabotage, pipeline tapping, and armed attacks threaten oil and gas assets in multiple regions. Insurance losses from energy infrastructure attacks have also risen in recent years. Drone attacks on Gulf refineries, damage to subsea pipelines in Europe, and fuel theft in Mexico and Nigeria highlight the range of physical threats. Operators are investing in counter-drone systems, perimeter intrusion detection, thermal surveillance, maritime security, and integrated command centers. Geopolitical tensions and conflicts in key producing regions continue to elevate physical security requirements for oil and gas companies worldwide.
⮞June 2026: The U.S. Department of Energy’s security exercises for oil and natural gas operators highlighted the need to test emergency-response arrangements and address weaknesses before incidents occur. Increasing attention to cyber and physical threats supports demand for monitoring, threat detection, incident response, and specialist security services.
Restraints: High Implementation Costs and Shortage of Skilled OT Security Professionals
High implementation costs remain a key restraint on the Oil and Gas Security and Service Market, as securing large, remote, and complex infrastructure requires significant investment in hardware, software, integration, and ongoing operations. Supply chain constraints can also delay delivery of security equipment. Upgrading legacy control systems to support modern cybersecurity measures can be expensive and may require production downtime. Smaller operators and companies in emerging markets may struggle to fund comprehensive security programs, particularly during periods of low oil prices. Demonstrating return on investment for security spending can be difficult, leading some organizations to delay or limit upgrades to their security infrastructure.
A shortage of skilled OT security professionals further restrains market growth, as protecting industrial control systems requires expertise in both cybersecurity and process operations. Training programs and industry partnerships are helping to address these skills gaps over time. Many oil and gas companies struggle to recruit and retain staff with this specialized knowledge, particularly in remote locations. Legacy systems running outdated software, proprietary protocols, and limited documentation complicate security implementation. Coordination between IT, OT, and physical security teams is often challenging. These factors can slow the deployment of security solutions and increase reliance on external service providers, adding cost and complexity for operators.
Opportunities: Managed OT Security Services and AI-Driven Integrated Security Platforms
Managed OT security services present significant opportunities for the Oil and Gas Security and Service Market, as operators seek external expertise to monitor control systems, detect threats, and respond to incidents around the clock. Long-term service contracts also provide predictable revenue for providers. Managed security operations centers specializing in OT environments, such as Honeywell's vendor-agnostic OT SOC, provide continuous monitoring without requiring large internal teams. Service providers can also offer vulnerability management, compliance reporting, and incident response retainers. Growing regulatory requirements and the shortage of skilled staff are expected to drive strong demand for managed services across major oil and gas regions.
AI-driven integrated security platforms present a further opportunity, as operators seek to combine video surveillance, access control, intrusion detection, drone detection, and cybersecurity data into unified command centers. Unified platforms also simplify compliance reporting and auditing across multiple regulatory frameworks and jurisdictions. Artificial intelligence improves threat detection by analyzing video, sensor, and network data in real time, reducing false alarms and enabling faster response. Integrated platforms provide a single view of physical and cyber risks across dispersed assets. Vendors that combine physical security, OT cybersecurity, and analytics capabilities can capture large enterprise contracts as operators modernize and consolidate their security operations.
⮞August 2026: Powerus’ USD 22.3 million counter-drone contract demonstrates commercial demand for integrated detection, tracking, classification, and early-warning systems for energy infrastructure. Such contracts point to opportunities for vendors combining counter-UAS technology, command-and-control capabilities, and physical security services.
Recent Developments:
-
February 2026: Dragos released its 2026 OT Cybersecurity Year in Review, reporting a surge in OT threat groups and ransomware and elevating VOLTZITE to Stage 2 of the ICS Cyber Kill Chain after the group compromised cellular gateways to reach U.S. midstream pipeline operations.
Oil and Gas Security and Service Market Key Players:
-
Honeywell International Inc.
-
Siemens AG
-
ABB Ltd.
-
Schneider Electric SE
-
Rockwell Automation, Inc.
-
Yokogawa Electric Corporation
-
Emerson Electric Co.
-
Cisco Systems, Inc.
-
IBM Corporation
-
Microsoft Corporation
-
Lockheed Martin Corporation
-
Thales Group
-
Fortinet, Inc.
-
Palo Alto Networks, Inc.
-
Nozomi Networks Inc.
-
Claroty Ltd.
-
Dragos, Inc.
-
Johnson Controls International plc
-
Axis Communications AB
-
Hexagon AB
Oil and Gas Security and Service Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 34.86 Billion |
| Market Size by 2035 | USD 63.86 Billion |
| CAGR | 6.24% from 2026-2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Component: Dominant – Solutions (58.42% share in 2025); Fastest-Growing – Services (CAGR 7.48%) • By Security Type: Dominant – Physical Security (54.26% share in 2025); Fastest-Growing – Network Security (CAGR 8.12%) • By Operation: Dominant – Upstream (41.36% share in 2025); Fastest-Growing – Midstream (CAGR 7.24%) • By Deployment: Dominant – On-Premises (62.48% share in 2025); Fastest-Growing – Cloud (CAGR 9.36%) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Honeywell International Inc., Siemens AG, ABB Ltd., Schneider Electric SE, Rockwell Automation, Inc., Yokogawa Electric Corporation, Emerson Electric Co., Cisco Systems, Inc., IBM Corporation, Microsoft Corporation, Lockheed Martin Corporation, Thales Group, Fortinet, Inc., Palo Alto Networks, Inc., Nozomi Networks Inc., Claroty Ltd., Dragos, Inc., Johnson Controls International plc, Axis Communications AB, Hexagon AB |

Frequently Asked Questions
Key players include Honeywell International Inc., Siemens AG, ABB Ltd., Schneider Electric SE, Rockwell Automation, Inc., Cisco Systems, Inc., and Thales Group, among other global security technology and service providers.
Managed OT security services, along with AI-driven integrated security platforms, represent the primary opportunities.
Growth is primarily driven by rising cyber threats to operational technology combined with increasing physical attacks on energy infrastructure.
By Security Type, Physical Security dominated the market with approximately 54.26% share in 2025, reflecting the need to protect large and remote energy facilities.
North America dominated the market with approximately 34.82% share in 2025, driven by extensive infrastructure and strict pipeline security regulations.
