
Optical Film Market Report Scope & Overview:
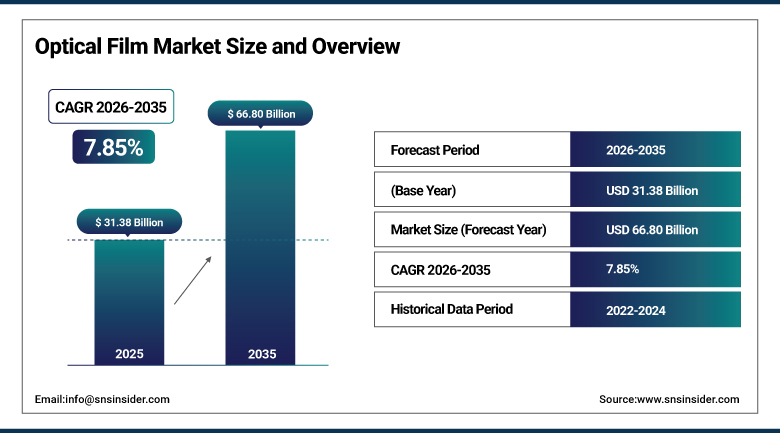
The Optical Film Market size was valued at USD 31.38 Billion in 2025 and is expected to reach USD 66.80 Billion by 2035, growing at a CAGR of 7.85% from 2026-2035.
Optical films constitute a critical category within display and light management materials, thin multilayer coated sheets that polarize, diffuse, reflect, or protect light inside televisions, monitors, smartphones, vehicle displays, and signage. Rising demand for larger and higher-resolution screens, the spread of OLED and mini-LED technologies, and growing display content in automobiles continue to widen the base of applications. These films are used by display panel manufacturers, polarizers, and electronics brands to enhance contrast, brightness, viewing angle, and durability. Sustained growth will be driven by investments in capacity expansions in Asia, innovations in cyclo olefin and ultra-thin functional films, and localization of raw material sourcing, thus emphasizing the nature of this market as a technology-based and Asia-focused sub-segment of the electronic materials market.
⮞In June 2025, Kuraray announced an expansion of its optical-use poval film production at its Saijo Plant in Japan, adding 38 million square meters per year to lift total capacity from 296 million to 334 million square meters annually. Poval film serves as the base material for polarizing films used in LCD and OLED displays.
To Get more information Optical Film Market - Request Free Sample Report
Optical Film Market Trends
- Growing capacity additions for polarizer base materials to support OLED and mini-LED display production.
- Rising substitution of cellulose acetate by cyclo olefin polymer films offering superior dimensional stability and clarity.
- Expanding use of optical films in automotive displays, instrument clusters, and head-up displays.
- Increasing development of ultra-thin optical adhesives and films for augmented and virtual reality devices.
- Rising demand for protective films with high ultraviolet blocking for outdoor signage and transit displays.
- Growing localization of raw material and film production across China, India, and Southeast Asia.
U.S. Optical Film Market Outlook
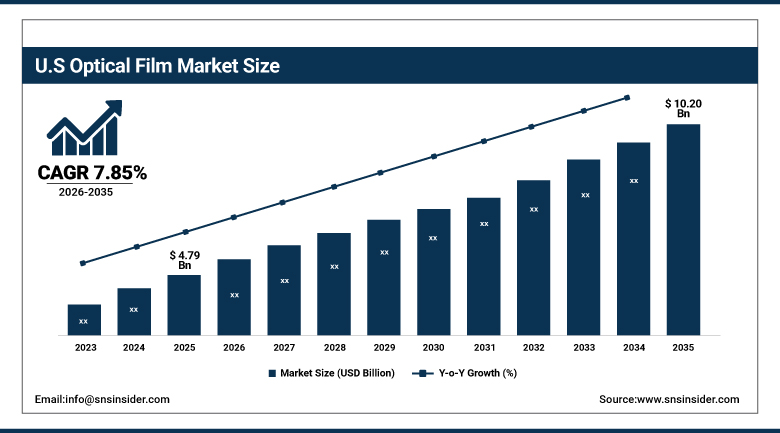
The U.S. Optical Film Market was valued at USD 4.79 Billion in 2025 and is expected to reach USD 10.20 Billion by 2035, growing at a CAGR of 7.85% from 2026-2035.
The U.S. Optical Film Market is growing steadily, supported by strong demand for premium consumer electronics, expanding automotive display content, and continued investment in augmented reality and advanced display research. Most polarizer and backlight films consumed in the country are imported from Asian manufacturers, so U.S. activity centers on light management technology, specialty coatings, and product design, where U.S. companies hold deep intellectual property in multilayer optical films. Defense, aerospace, medical imaging, and industrial displays add demand for high-performance films. Trade policy, supply chain resilience, and interest in localizing display materials are increasingly shaping sourcing decisions, while collaboration between global film makers and U.S. technology firms supports innovation and keeps the country an important market for premium optical solutions.
⮞In the first quarter of 2025, Toray Industries was reported to have acquired a minority stake in a U.S.-based company specializing in advanced optical film materials. The investment was described as aimed at strengthening Toray's global research and development capabilities in optical films.
Optical Film Market Segment Analysis
- By Product Type, the Polarizer Films segment dominated the market with a 48.60% share in 2025, while the Protective & Functional Films segment is the fastest growing with a CAGR of 9.10% during 2026-2035.
- By Application, the Television segment dominated the market with a 36.40% share in 2025, while the Automotive Displays segment is the fastest growing with a CAGR of 10.80% during 2026-2035.
- By Material, the Polyester segment dominated the market with a 42.60% share in 2025, while the Cyclo Olefin Polymer segment is the fastest growing with a CAGR of 10.20% during 2026-2035.
- By Display Technology, the LCD segment dominated the market with a 66.40% share in 2025, while the OLED segment is the fastest growing with a CAGR of 11.60% during 2026-2035.
By Product Type, Polarizer Films Dominates the Market and Protective & Functional Films Grows Fastest
Polarizer Films dominated the market in 2025, a position built on their essential role in both LCD and OLED panels, where every display needs polarizing layers to control light and deliver contrast. Panel makers favour these films precisely because there is no practical substitute for the function they perform at scale, a requirement that keeps polarizers close to half of overall optical film demand and anchors investment in poval base film, protective layers, and compensation films across the display supply chain, even as newer functional films continue to expand around them.
Protective & Functional Films are projected to be the fastest-growing product type over the forecast period. Demand is rising for ultraviolet-blocking films for outdoor signage, anti-reflective and anti-glare coatings, and durable protective layers for automotive and foldable displays. As screens move into harsher environments and thinner, flexible formats, and as vehicle makers demand long-lasting optical performance, these films continue to close the gap with polarizers in overall market demand.
⮞In June 2025, Kuraray announced an expansion of optical-use poval film capacity at its Saijo Plant in Japan. The additional line is designed to add 38 million square meters annually, increasing total capacity from 296 million to 334 million square meters, with operations scheduled to begin in December 2027. Poval film is a key base material for polarizing films used in LCDs.
By Application, Television Dominates the Market and Automotive Displays Grows Fastest
Television applications dominated the market in 2025. Large-screen televisions use several films per panel, including polarizers, prism and diffuser sheets, and reflective polarizers, and the steady trend toward larger sizes multiplies the film area required for each set. High production volumes and the continuous upgrade cycle to higher-resolution screens continue to sustain televisions as the largest application category by a clear margin across the broader market.
Automotive Displays are expected to be the fastest-growing application over the forecast period. Vehicles are adopting larger central touchscreens, digital instrument clusters, and head-up displays, all of which require durable films with wide temperature tolerance and high brightness performance. As electric and software-defined vehicles increase display content per car, automotive applications continue to close the gap with televisions in overall market demand.
⮞In October 2025, LG Chem and ZEISS announced a strategic alliance to establish an industrial-scale supply chain for photopolymer films used in automotive holographic windshield displays. The partners are co-developing materials for windshield-based display systems, with automotive OEM series production targeted for 2029.
By Material, Polyester Dominates the Market and Cyclo Olefin Polymer Grows Fastest
Polyester dominated the market in 2025. It provides a favourable balance of optical clarity, mechanical strength, thermal stability, and cost, and it is the workhorse base film for prism sheets, diffusers, reflective films, and protective layers. Well-established supply chains and large-scale coating lines continue to sustain polyester as the largest material category across the broader market.
Cyclo Olefin Polymer is projected to be the fastest-growing material over the forecast period. These films offer near-glass transparency, very low moisture absorption, and superior dimensional stability, making them well suited to large automotive displays, medical screens, and high-end polarizer protective layers. As producers expand dedicated capacity and displace cellulose acetate, cyclo olefin films continue to close the gap with polyester in overall market demand.
⮞In June 2025, Kuraray announced that it would discontinue production of certain polyester-related products. This is a relevant supply-chain development for optical-material buyers, but the announcement does not establish that optical-grade polyester films are affected; it should not be presented as a direct reduction in optical-film supply.
By Display Technology, LCD Dominates the Market and OLED Grows Fastest
LCD technology dominated the market in 2025. The installed base and continuing production of LCD televisions, monitors, and notebooks require multiple optical films per panel, including backlight unit sheets that OLED panels do not use. This breadth of film content per display, combined with very high panel volumes, continues to sustain LCD as the largest display technology category across the broader market.
OLED is expected to be the fastest-growing display technology over the forecast period. Adoption in smartphones, premium televisions, laptops, and foldable devices is rising, and although OLED panels use fewer film layers, they require specialized circular polarizers, touch films, and flexible protective layers. As OLED penetration widens into automotive and IT displays, demand for these specialized films continues to close the gap with LCD-related films in overall market demand.
⮞In October 2025, LG Chem and ZEISS established a partnership for photopolymer films supporting automotive holographic displays. Although the announcement is directly relevant to advanced optical films and emerging display applications, it concerns holographic windshield technology rather than an OLED-specific film launch.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 |
|---|---|---|
|
Asia Pacific |
China |
41.80% |
|
North America |
United States |
87.80% |
|
Europe |
Germany |
29.60% |
|
Latin America |
Mexico |
44.80% |
|
Middle East & Africa |
United Arab Emirates |
30.40% |
Asia Pacific Optical Film Market Insights
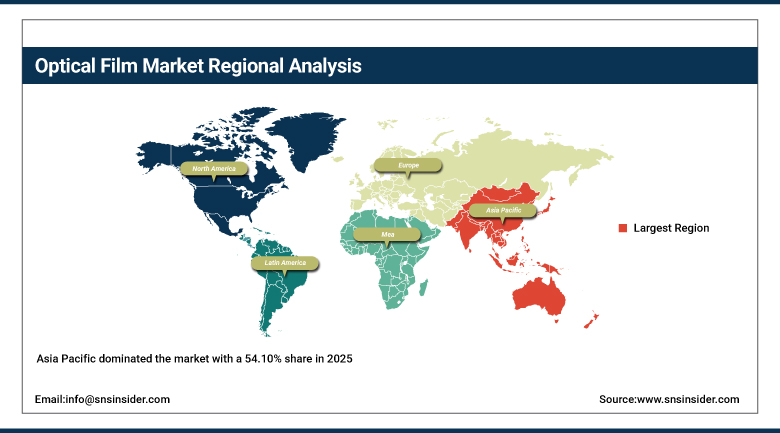
Asia Pacific dominated the market with a 54.10% share in 2025 and is also projected to expand at the fastest pace, with a CAGR of 8.40% during 2026-2035. The region has the top manufacturers and producers of display panels and films in the world, with Japan, South Korea, Taiwan, and China being the most productive areas both in manufacture and consumption of these products.
China acts as a source of demand for the area, thanks to its enormous panel manufacturing capability, in addition to the films and raw materials like polyvinyl alcohol that it is developing. Japan is characterized by the development of superior materials like poval, cyclo olefin, and polarizer. India and Southeast Asia are emerging as new production sites supported by localization programs, and producers have been expanding capacity in the latter region, positioning Asia Pacific to retain both the largest revenue base and the fastest growth through 2035.
⮞In June 2025, Kuraray announced additional optical-use poval film capacity in Japan to address growing demand for wider polarizing films as television screen sizes increase. The investment supports Asia-Pacific’s optical-material supply chain, although it is a Japan-based expansion rather than a China-specific production project.
Get Customized Report as per Your Business Requirement - Enquiry Now
North America Optical Film Market Insights
North America represents a significant regional market for optical films, anchored by the United States, where demand comes from premium consumer electronics, automotive displays, medical imaging, defense systems, and emerging augmented reality devices. Regional companies are leaders in multilayer optical film technology and light management, and they supply brightness enhancement and reflective polarizer concepts used worldwide.
Canada contribute additional volume through automotive and electronics assembly. Most display-grade films are imported, so growth is closely linked to consumer device demand and to sourcing decisions shaped by trade policy. Investment in augmented reality and flexible displays is expected to support steady regional growth, even as percentage growth trails the fast-scaling Asia Pacific market.
⮞In December 2025, 3M announced an expansion of its Digital Materials Hub to include optical models that simulate film performance in common engineering environments. The tools help automotive and consumer-electronics designers evaluate optical behaviour and material trade-offs earlier in product development.
Europe Optical Film Market Insights
Europe holds a meaningful share of the global market, driven mainly by automotive display demand, industrial and medical imaging, and premium electronics. Germany anchors regional demand through its automotive sector, which is integrating larger and more sophisticated displays into vehicles, and through specialty optical component manufacturers.
France, the United Kingdom, and Italy contribute consistent demand, while regional suppliers of specialty films and glass focus on high-value niches such as architectural glazing, sensors, and automotive glass laminates. Limited local panel manufacturing means most standard display films are imported, so growth is expected to follow automotive and industrial display adoption.
⮞In October 2025, ZEISS and LG Chem announced a strategic partnership to develop an industrial-scale supply chain for photopolymer films used in automotive holographic windshield displays. The collaboration combines ZEISS’s microoptics expertise with LG Chem’s materials capabilities, with series production for automotive manufacturers targeted for 2029.
MEA & Latin America Optical Film Market Insights
The Latin American market is driven by Mexico and Brazil, wherein television and consumer electronics assembly ensures constant demand for display parts. Consumption in the region is dependent on imports, while development is driven by electronics manufacturing, import duties, and consumer buying power.
The Middle East & Africa region is developing from a small base, with demand being generated mainly in the GCC countries like UAE, which are seeing rising demand for digital signage, retail applications, and smart cities initiatives. In Africa, the main driver of demand comes from South Africa, aided by the growth in consumer electronics distribution and large format displays.
⮞In July 2026, Dubai-based XPANCEO announced a collaboration with JBD to develop a microdisplay for smart contact lenses. The project includes a compact optical system designed to form an image close to the eye, providing evidence of regional activity in emerging microdisplay technology.
Market Dynamics
Growth Drivers: Display Proliferation and Larger Screen Sizes
Increasing demand for big screen TVs, monitors, smartphones, and tablets is the biggest driver behind growth, since each display will have to use several optical films in order to manipulate light and ensure contrast. Rising consumer preference for larger and higher-resolution displays multiplies the film area per device, while continuous product refresh cycles sustain volumes.
The adoption of OLED, mini-LED, and flexible display technologies provides a second major driver, along with growing display content in vehicles and the emergence of augmented reality devices. Advances in materials such as cyclo olefin polymers and ultra-thin adhesives, together with government-backed localization programs in China and India, further support capacity expansion and innovation.
⮞In June 2025, Kuraray announced an expansion of its optical-use poval film capacity by 38 million square meters annually to meet increasing demand for wider polarizing films associated with larger LCD television panels.
Restraints: Raw Material Dependence and Price Pressure
Raw material dependency is an actual constraint to the growth of the market. Polarizer manufacturing uses polyvinyl alcohol, iodine, and triacetyl cellulose or other types of protective films; shortages and price fluctuations may influence profits. Business relationships in the area of substrates used for displays and patenting system bring additional complications to the films manufacturer.
Price pressure and technology shifts present further restraints. Fierce competition among display panel manufacturers has driven down the price levels, which have been transmitted to film suppliers. There are many film suppliers but the market is dominated by few Asian companies who hold considerable bargaining power. The advancement of OLED technology, which has lesser film layers as compared to LCD, may further lower the amount of film used.
Opportunities: Automotive, AR/VR, and Advanced Functional Films
Growth in automotive displays offers a substantial opportunity, as vehicles adopt larger screens and head-up displays that require durable, high-performance films. Suppliers with automotive-grade qualification, wide temperature tolerance, and strong optical performance can win long-lifecycle contracts and command premium pricing relative to consumer electronics films.
The development of films and adhesives for augmented and virtual reality devices presents a further avenue for growth. Ultra-thin optical adhesives, light-control films, and waveguide-related materials are needed in compact head-mounted devices, and micro-LED and flexible display formats create demand for new functional layers. Producers that invest early in these technologies can establish leadership in emerging high-value niches.
⮞In September 2026, Sumitomo Chemical announced a transparent coating material capable of forming thin films with a refractive index as low as 1.06. The company identified applications in advanced optical devices, including next-generation AR/VR displays and optical components for image sensors.
Recent Developments:
- 2026: 3M Company and BOE launched a joint laboratory focused on display materials, including optical films, with R&D targeting optical efficiency, foldable displays, narrow bezels, LCD, OLED, and MLED applications.
- 2026: Sumitomo Chemical Co., Ltd. developed a transparent ultra-low-refractive-index coating capable of forming optical thin films with a refractive index as low as 1.06, targeting next-generation optical devices.
- 2026: LG Chem Ltd. expanded advanced-materials development for optical and display applications, while its 2025 partnership with ZEISS established a strategic framework for industrial-scale photopolymer films for automotive holographic windshield displays.
- 2026: Ningxia Shuangying New Material Technology announced the start of construction of a 100,000-ton-per-year polyvinyl alcohol project in Ningxia, China, with trial production planned by November 2026.
Optical Film Companies are:
- LG Chem Ltd.
- Nitto Denko Corporation
- Sumitomo Chemical Co., Ltd.
- Toray Industries, Inc.
- 3M Company
- Dai Nippon Printing Co., Ltd.
- FUJIFILM Holdings Corporation
- Zeon Corporation
- Kuraray Co., Ltd.
- Teijin Limited
- Toyobo Co., Ltd.
- Mitsubishi Chemical Group Corporation
- SKC Co., Ltd.
- Shinwha Intertek Corp.
- Eastman Chemical Company
- Sanritz Corporation
- Sekisui Chemical Co., Ltd.
- Kolon Industries, Inc.
- Samsung SDI Co., Ltd.
- Hyosung Chemical Co., Ltd.
Optical Film Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 31.38 Billion |
| Market Size by 2035 | USD 66.80 Billion |
| CAGR | CAGR of 7.85% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (Polarizer Films, Backlight Unit Films, ITO Films, Protective & Functional Films, Others) • By Application (Television, Monitors & Laptops, Smartphones & Tablets, Signage & Large Format Displays, Automotive Displays, Others) • By Material (Polyester, Cyclo Olefin Polymer, Polycarbonate, Acrylic, Others) • By Display Technology (LCD, OLED, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | LG Chem Ltd., Nitto Denko Corporation, Sumitomo Chemical Co., Ltd., Toray Industries, Inc., 3M Company, Dai Nippon Printing Co., Ltd., FUJIFILM Holdings Corporation, Zeon Corporation, Kuraray Co., Ltd., Teijin Limited, Toyobo Co., Ltd., Mitsubishi Chemical Group Corporation, SKC Co., Ltd., Shinwha Intertek Corp., Eastman Chemical Company, Sanritz Corporation, Sekisui Chemical Co., Ltd., Kolon Industries, Inc., Samsung SDI Co., Ltd., Hyosung Chemical Co., Ltd. |

Frequently Asked Questions
Key players in the optical film market include 3M, Nitto Denko, LG Chem, Toray, Mitsubishi Chemical, and others innovating in polarizer and functional films.
Recycling limitations for multilayer films hinder the optical film market’s sustainability goals, as reported by the U.S. EPA’s 2023 PET recycling statistics.
Polarizing film led the optical film market with a 46.5% share due to rising integration in smartphones, automotive HUDs, and high-resolution OLED screens.
Asia Pacific dominates the optical film market share with 47.6%, supported by strong electronics manufacturing in China, Japan, and South Korea.
The optical film market size reached USD 27.95 billion in 2024, driven by demand from OLED, automotive, and smartphone display applications.
