
Personal Cooling Device Market Report Scope & Overview:
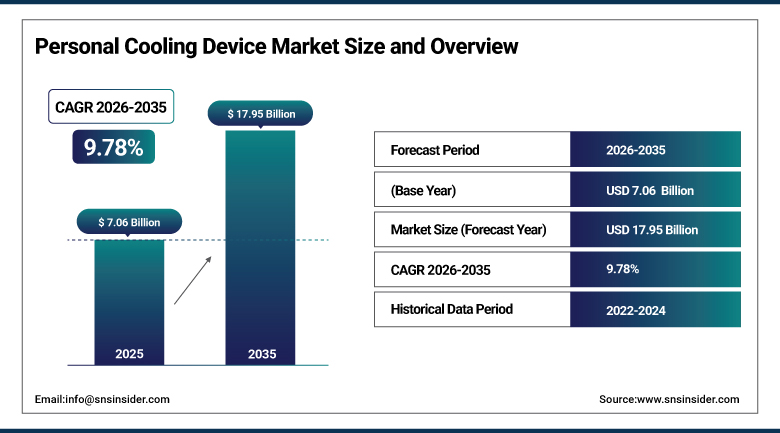
The Personal Cooling Device Market size was valued at USD 7.06 Billion in 2025 and is expected to reach USD 17.95 Billion by 2035, growing at a CAGR of 9.78% from 2026-2035.
The Personal Cooling Device Market covers wearable and portable products that lower body temperature without cooling a whole room, including neck fans, neck air conditioners, cooling vests, fan-equipped work clothing and handheld units. Hotter summers are pushing households, outdoor workers, commuters and athletes toward products that cost far less to run than a room air conditioner. Lighter batteries, thermoelectric modules and phase change materials are improving comfort and runtime. Employers are also buying cooling garments as heat protection rules tighten. Online retail has widened access, while fashion and workwear brands are adding cooling features to everyday apparel. These shifts support strong growth through 2035.
⮞In August 2025, the World Health Organization and the World Meteorological Organization reported that worker productivity falls by 2-3% for every degree Celsius above 20°C and that more than 2.4 billion workers face excess heat. The finding strengthens the business case for personal cooling products.
To Get more information Personal Cooling Device Market - Request Free Sample Report
Personal Cooling Device Market Trends
-
Thermoelectric neck air conditioners are replacing simple fans as prices fall and cooling performance improves.
-
Fan-equipped and liquid-circulation work clothing is moving from industrial use into mainstream fashion and retail.
-
App control, smart temperature sensing and wearable integration are being added to premium cooling devices.
-
Phase change material vests and inserts are gaining use where users need cooling without batteries or noise.
-
Online and direct-to-consumer sales are expanding reach for new brands, particularly during summer peaks.
U.S. Personal Cooling Device Market Size Outlook
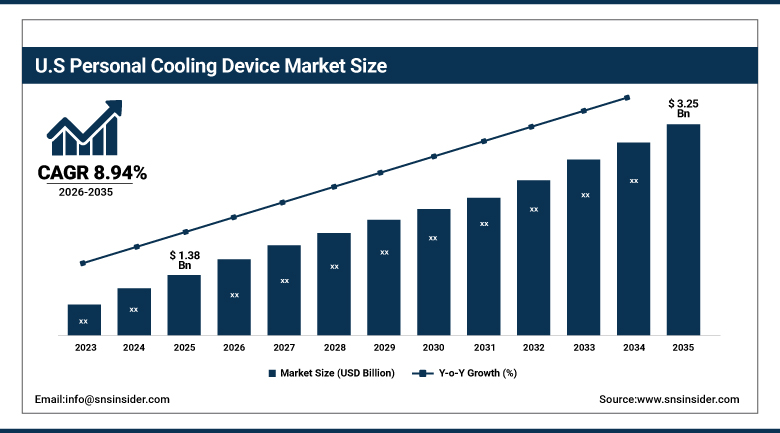
The U.S. Personal Cooling Device Market was valued at USD 1.38 Billion in 2025 and is expected to reach USD 3.25 Billion by 2035, growing at a CAGR of 8.94% from 2026-2035.
The U.S. Personal Cooling Device Market is supported by long hot summers across the South and Southwest, a large base of outdoor workers in construction, agriculture and logistics, and active consumer interest in camping, sports and travel. Online marketplaces and big-box retailers carry a wide range of neck fans, cooling towels and vests at accessible prices. Employers are weighing heat illness prevention programs as federal and state attention to workplace heat grows. Military, firefighting and emergency services buy specialized cooling garments. Medical and wellness uses, including menopause and multiple sclerosis support, add a smaller premium segment. These factors sustain steady growth in the U.S. through 2035.
⮞The Occupational Safety and Health Administration held its public hearing on the proposed federal heat injury and illness prevention rule from 16 June to 2 July 2025 and closed post-hearing comments on 30 October 2025. The rulemaking keeps employer attention on heat protection equipment.
Personal Cooling Device Market Segment Analysis
-
By Product Type, the Personal Air Conditioners segment dominated the Personal Cooling Device Market with approximately 38.40% share in 2025, while the Cooling Vests segment is the fastest growing with a CAGR of approximately 11.52%.
-
By Technology, the Evaporative segment dominated the Personal Cooling Device Market with approximately 41.30% share in 2025, while the Thermoelectric segment is the fastest growing with a CAGR of approximately 11.38%.
-
By Application, the Residential segment dominated the Personal Cooling Device Market with approximately 42.80% share in 2025, while the Industrial segment is the fastest growing with a CAGR of approximately 10.94%.
-
By Distribution Channel, the Online segment dominated the Personal Cooling Device Market with approximately 44.70% share in 2025 and is also the fastest growing with a CAGR of approximately 11.86%.
By Product Type, Personal Air Conditioners Dominates the Personal Cooling Device Market and Cooling Vests Grows Fastest
Personal air conditioners lead because they deliver noticeable cooling in a compact form that suits commuting, travel and daily outdoor activity. Neck-worn units, clip-on coolers and small desktop evaporative units are widely available in a broad price range, which opens the category to students, office workers and families. Rechargeable batteries and USB-C charging have removed the main barriers to everyday use. Retailers feature these products prominently every summer, and review-driven marketing helps new brands win quick visibility. Steady product refreshes keep repeat purchases common.
Cooling vests are growing fastest as industrial employers, military units, athletes and motorsport users look for stronger heat relief than a fan can offer. Designs now combine phase change packs, circulating chilled water and ventilated fabrics, so users can pick a vest by shift length and budget. Lighter materials and better ergonomics improve acceptance among workers who wear protective equipment. Fashion-oriented work shirts with built-in fans are widening the audience. Rising workplace heat obligations are encouraging bulk orders from companies and public agencies. Suppliers also invest in testing, certification and after-sales support to build lasting trust with buyers.
⮞In August 2026, Workman Co., the Japanese workwear retailer, said that cumulative sales of its fan-equipped clothing passed 1.2 million units through July 2026. The figure shows how quickly ventilated garments are reaching mainstream buyers.
By Technology, Evaporative Dominates the Personal Cooling Device Market and Thermoelectric Grows Fastest
Evaporative cooling leads because it is inexpensive, uses little power and works well in dry and moderately humid climates. Cooling towels, misting fans, evaporative neck bands and small desktop coolers rely on water and airflow rather than compressors, so manufacturing costs stay low. Consumers value simple operation and the absence of refrigerants. Hot and dry regions in the Middle East, India and the southwestern United States offer good conditions for this method. Large production volumes in Asia keep retail prices attractive and support wide distribution through e-commerce.
Thermoelectric technology is growing fastest because Peltier modules can now lower skin temperature in a thin wearable package that works in humid conditions. Neck air conditioners and chest-worn units built on this approach deliver a clear temperature drop without water or refrigerant. Improvements in module efficiency, heat sinks and battery capacity are extending runtime. Premium brands add heating functions for year-round use, which supports sales outside summer. App control and sensor-based adjustment improve the user experience and justify higher price points. Product refresh cycles are short, so brands that release improved models each season keep their lead.
⮞In July 2026 , Midea said that its portable air conditioner sales in Europe passed 200,000 units, double the level of the prior year. The result reflects heightened consumer interest in compact cooling during heatwaves.
By Application, Residential Dominates the Personal Cooling Device Market and Industrial Grows Fastest
Residential use leads because individual consumers account for the bulk of unit sales across neck fans, handheld fans, cooling towels and personal air conditioners. Buyers include commuters, parents, students, older adults and outdoor hobbyists who want relief without running a home air conditioner. Apartments and older buildings with limited cooling benefit especially from personal devices. Seasonal promotions on online marketplaces create large spikes in volume. Gift buying and travel preparation add further demand outside peak heat weeks. Competition among established groups and new entrants continues to shape pricing, design and distribution choices.
Industrial market is experiencing growth at the highest rate due to the stringent heat protection policies in place and increased cost of heat illnesses and accidents among employees. Construction companies, logistics firms, manufacturers, farmers and utility workers are embracing the use of cooling vests, fan jackets and neck wraps as standard gear. The safety managers are keen on solutions that can be worn underneath personal protective equipment and which will last an entire working shift. The purchase of the items via distributors and safety catalogues facilitates bulk purchases. Pilot projects that show improvement in efficiency and reduction in heat injuries become company-wide.
⮞On 1 June 2025, Japan's Ministry of Health, Labour and Welfare brought into force a revised ordinance that requires employers to prepare heatstroke reporting and response procedures for work in hot conditions. The rule is expected to lift workplace purchases of cooling clothing.
By Distribution Channel, Online Dominates the Personal Cooling Device Market and Also Grows Fastest
Online channels lead because marketplaces and brand websites give shoppers the widest selection, quick comparisons and easy delivery during heatwaves. Many neck fan and cooling vest brands started as digital sellers and rely on video reviews, influencer content and search advertising. Cross-border e-commerce lets Asian manufacturers sell directly to buyers in North America and Europe. Frequent discounts around seasonal sales events draw impulse purchases. Customer ratings help new entrants build trust faster than they could in physical stores. Rising public awareness of heat risk keeps interest in cooling products high from year to year.
Online is also the fastest growing channel as mobile shopping, same-day delivery and social commerce expand. Brands are using subscription offers, bundled accessories and extended warranties to increase basket size. Direct-to-consumer stores provide better margin and customer data for product development. Retail chains now mirror this momentum with omnichannel promotions and click-and-collect options. Industrial buyers are also moving orders to online business marketplaces, which streamlines procurement and widens the supplier pool. Manufacturers continue to refine materials, batteries and ergonomics to raise comfort and runtime.
⮞Makeman, the Okinawa-based home improvement chain, reported that sales of fan-equipped work clothing in the first half of June 2025 were 3.3 times the level of the previous year. The surge shows how sharply demand responds to early summer heat.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
43.62% |
|
North America |
United States |
85.40% |
|
Europe |
Germany |
24.35% |
|
Latin America |
Brazil |
41.76% |
|
Middle East & Africa |
Saudi Arabia |
27.48% |
Asia Pacific Personal Cooling Device Market Insights
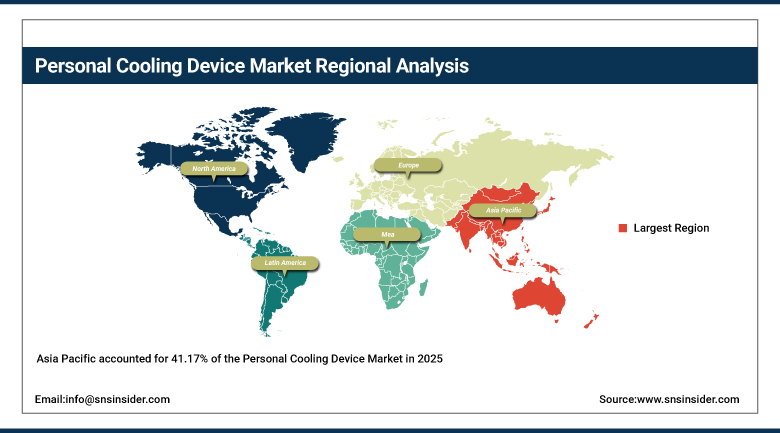
Asia Pacific accounted for 41.17% of the Personal Cooling Device Market in 2025, which made it the largest region, and it is also the fastest growing at a CAGR of 10.68% during 2026-2035. China is both the leading manufacturing base and the largest consumer market, with a vast e-commerce ecosystem. Japan is the most advanced market for fan-equipped clothing and wearable coolers, supported by corporate adoption. India offers the fastest country growth as summers intensify and incomes rise. South Korea and Southeast Asia contribute strong consumer demand.
Thermoelectric modules, small fans, and lithium batteries have seen substantial investment by local manufacturers to make prices affordable and fasten production cycles. Manufacturers of cooling garments among those involved in constructions, logistics, and manufacturing industries are embracing these garments under the ever-evolving heat regulations. Local firms are introducing new cooling garments every season while Japan's workwear and electronic companies are venturing into premium cooling garments. City commuting, outdoor events, and sports events create consumer demand for these garments. Big retailers and live selling platforms are making sure these new products are accessible to consumers within weeks of introduction.
⮞The China Meteorological Administration reported in January 2026 that the national average temperature in 2025 was 10.9°C, tied with 2024 for the highest on record, and that the country logged the most days with highs of 35°C or above since records began. These conditions sustain demand for personal cooling.
Get Customized Report as per Your Business Requirement - Enquiry Now
North America Personal Cooling Device Market Insights
North America holds the second-largest share, led by the United States, with Canada contributing a smaller but growing consumer base. Long heat seasons, extensive outdoor recreation and a large number of outdoor workers support steady demand. Retail penetration is high through big-box stores, sporting goods chains and online marketplaces. Established safety equipment suppliers sell cooling vests, towels and neck wraps to construction, utilities and emergency services. Consumers increasingly choose rechargeable neck fans and wearable air conditioners for travel and events. Differences in climate, income and retail structure also guide product choice and pricing.
Employers and safety managers are watching federal and state heat illness rules, and some are voluntarily adopting cooling equipment to protect workers and productivity. Military and public safety buyers favor proven phase change and liquid-circulation systems. Medical and wellness brands target users who are sensitive to heat. Premium thermoelectric products sell well in specialty and direct channels. Growth is solid rather than rapid because the market is mature and price sensitive, and because many buyers replace low-cost units every season. Quiet operation and light weight are becoming standard expectations among first-time buyers.
⮞On 19 February 2026, The U.S. Bureau of Labor Statistics reported that its Census of Fatal Occupational Injuries recorded 53 deaths from exposure to temperature extremes in 2024. The figure keeps workplace heat protection on employer agendas.
Europe Personal Cooling Device Market Insights
Europe holds a substantial share and is among the fastest-changing markets as repeated heatwaves expose limited air conditioning in homes and workplaces. Germany, France, Italy, Spain and the United Kingdom lead consumption, supported by an active online retail sector. Portable air conditioners have enjoyed sharp demand, and wearable coolers are following as consumers look for lower-cost relief. Public health campaigns around heat risk raise awareness among older adults and outdoor workers. Southern countries show the most urgent need. Bundled accessories such as spare batteries, charging cables and carrying cases raise the value of each sale.
Construction, agricultural, and tourism sector employers are increasingly offering cooling clothing and hydration programs as heat warnings are becoming more common. Local working conditions in Greece, Italy, and Spain specify that work must be halted during extreme heat events, providing an incentive to invest in appropriate equipment. The European manufacturers emphasize design, comfort, and sustainability, whereas the Asian ones deliver the majority of affordable options. The retail ranges are being expanded by retailers annually before the summer season starts. Legislation regarding batteries, product safety, and electronic waste creates additional compliance responsibilities for the suppliers.
⮞In August 2026 , Spain's Carlos III Health Institute reported that 4,458 heat-related deaths were recorded from 1 June to 19 August 2026, compared with 3,073 in 2025 and 1,890 in 2024. The trend raises public and employer demand for personal cooling.
MEA & Latin America Personal Cooling Device Market Insights
Middle East and Africa is expanding as extreme summer temperatures in the Gulf states, North Africa and parts of the Sahel create constant need for heat protection. Saudi Arabia and the United Arab Emirates lead demand through construction, oil and gas, logistics and pilgrimage activity. Seasonal midday work bans encourage employers to provide cooling gear for the remaining hours. Retail growth in malls and online platforms makes consumer devices easy to buy. South Africa and Egypt add steady volumes from households and industry. Product refresh cycles are short, so brands that release improved models each season keep their lead.
Latin America consists of Mexico, Brazil, Argentina and Colombia that have warm weather conditions and non-dependable air conditioning systems in low-income families leading to an inclination towards affordable personal coolers. In Mexico, demand is driven by factory workers and those working outside while in Brazil the consumer base is the largest one. Online retail platforms play a huge role in sales along with imports, where customs duties affect pricing. The agriculture and mining sectors are using cooling clothes. Both markets are still small in comparison to others, but increasing temperatures and e-commerce make them grow steadily.
⮞in March 2026, the World Meteorological Organization reported in its State of the Global Climate 2025 report that 2015 to 2025 were the eleven warmest years on record. The warming trend lifts the need for heat protection across both regions.
Market Dynamics
Growth Drivers: Record Heat and Workplace Heat Rules Drive Growth in the Personal Cooling Device Market
The second motivator is the aspect of regulation and employer accountability. Governments are mandating heat illness prevention responsibilities, breaks and midday limitations, and thus putting pressure on firms to provide cooling clothing and devices. Insurance providers and safety officers have associated cooling devices with reduced number of accidents and increased productivity. Fashion and work wear manufacturers are coming up with fan-infused clothes to target everyday consumers. All these factors lead to expanding the consumer market from just outdoors lovers to normal consumers and companies’ car fleets.
Regulation and employer responsibility add a second driver. Governments are introducing heat illness prevention duties, rest requirements and midday work limits, which push companies to supply cooling clothing and equipment. Insurers and safety managers link cooling gear to lower accident rates and better productivity. Fashion and workwear brands are launching fan-equipped apparel that appeals to everyday users. Together, these forces widen the buyer base beyond outdoor enthusiasts to mainstream households and corporate fleets. Customer reviews and demonstrations on video platforms strongly influence which models buyers trust.
⮞The Japan Meteorological Agency reported in September 2025 that the June to August 2025 average temperature in Japan was 2.36°C above normal, the highest since records began in 1898. Isesaki recorded 41.8°C on 5 August 2025, a national record.
Restraints: Seasonal Demand and Battery Limitations Restrain Growth in the Personal Cooling Device Market
The demand is seasonal, meaning that any cold or short summer period may drastically lower sales and result in retailers having unsold stock. The manufacturing company has to plan its production well in advance, and any mistake in the forecasting may have an impact on profitability. Low entrance barriers mean that there will be lots of smaller competitors, which means that the prices will be lowered and there will not be much quality control. A bad experience of the customer with the first purchased item leads to non-purchase in future.
Product limitations add friction. Most wearable devices run for only a few hours on a charge, and weight on the neck or shoulders can limit comfort. Thermoelectric cooling loses effectiveness in extreme ambient heat and consumes considerable power. Lithium battery safety concerns create regulatory and shipping costs. Evaporative products work poorly in humid climates. Some users find noise or skin contact unpleasant, which restricts repeat purchases and slows adoption among older consumers. Sustainability claims, such as recyclable materials and longer product life, are gaining weight in purchase decisions.
⮞In January 2026, The Copernicus Climate Change Service reported that 2025 was the third-warmest year on record at 1.47°C above the 1850-1900 level, cooler than the record set in 2024. Year-to-year swings of this kind illustrate how seasonal demand can shift.
Opportunities: Occupational Safety and Health-Linked Products Create Opportunities in the Personal Cooling Device Market
Occupational safety programs offer large opportunities for suppliers that can certify performance and durability. Construction firms, utilities, ports, farms and factories need cooling solutions that fit under protective gear and run for full shifts. Suppliers that offer fitting, training and replacement services can win multi-year contracts. Integrations with heat stress monitoring sensors and wearable platforms allow companies to track worker exposure and justify spending. Government tenders for public works crews and emergency services add further volume. Seasonal promotions and early-summer launches help brands capture the first wave of demand each year.
Use of health and lifestyle applications is another area. There is room for products catering to women with menopausal hot flashes, people having problems with heat during chronic illnesses, and people of the senior age category who can afford to pay a little more for such products. Partnering with fashion houses, designing school uniform collections and licensing with sports brands increases their customer base. The potential emerging markets in South Asia, Africa and Latin America are vast and have populations that do not have air conditioning. Designs that are solar-powered or have long battery life will help find applications even without electricity.
⮞In October 2025, The Lancet Countdown on Health and Climate Change reported that 640 billion potential labor hours were lost to heat exposure in 2024. The scale of lost work highlights the economic potential for protective cooling products.
Recent Developments:
-
2026: Sony released the Reon Pocket 6 wearable thermo device in Japan on 12 May at JPY 25,300. It uses a dual thermo module, reaches a cooling surface temperature of 21.2°C against 23.3°C for the Reon Pocket 5, and runs up to 5.5 hours. The company also expanded the Reon Pocket Pro Plus to Germany at EUR 229, with a 10-hour battery and a surface that reaches 19.7°C.
-
2026: Indian startup CHILTIER announced the Thermo Pod, a wearable cooling and heating system that combines Peltier thermoelectric technology with hydro-circulation. The 800 g pod and Hydro Vest provide temperature control from 10°C to 40°C, app control and refrigerant-free operation, targeting workers and everyday users in hot climates.
-
2026: Los Angeles-based Venustas introduced its first cooling vest, which combines chilled-water circulation with two fans and runs on USB-A power. The kit is priced at USD 149.99 and the vest alone at USD 99.99, aiming at outdoor workers, hobbyists and travelers.
-
2026: Japanese retailer Yofuku no Aoyama and Kuchofuku, the maker behind fan-equipped clothing, launched an air-conditioned short-sleeve work shirt at JPY 17,490. It has two fans of about 95 g each, up to 10 hours of runtime and airflow of about 53 liters per second.
Personal Cooling Device Companies are:
-
Sony Group Corporation
-
Kuchofuku (FZN Co., Ltd.)
-
CHILTIER
-
Venustas
-
Embr Labs
-
CoolShirt Systems
-
JISULIFE
-
Makita Corporation
Personal Cooling Device Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 7.06 Billion |
| Market Size by 2035 | USD 17.95 Billion |
| CAGR | CAGR of 9.78% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (Personal Air Conditioners, Wearable Devices, Cooling Vests, and Others) • By Technology (Evaporative, Thermoelectric, Phase Change Material, and Others) • By Application (Residential, Industrial, Commercial, and Others) • By Distribution Channel (Online, Supermarkets and Hypermarkets, Specialty Stores, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Sony Group Corporation, TORRAS, Kuchofuku (FZN Co., Ltd.), CHILTIER, Venustas, Glacier Tek, Embr Labs, CoolShirt Systems, JISULIFE, Makita Corporation |

Frequently Asked Questions
The key players in the Personal Cooling Device Market include Sony Group Corporation, TORRAS, Kuchofuku (FZN Co., Ltd.), CHILTIER, Venustas, among others.
Key opportunities include occupational safety programs that require certified cooling garments, health and lifestyle products for heat-sensitive users, and affordable off-grid cooling for emerging markets.
The major growth factor is rising temperatures combined with stricter workplace heat rules, which push households and employers toward low-cost wearable and portable cooling products.
The Personal Air Conditioners segment dominated the Personal Cooling Device Market with approximately 38.40% share in 2025, supported by compact designs and wide retail availability.
Asia Pacific dominated the Personal Cooling Device Market with a 41.17% share in 2025, driven by manufacturing scale, large consumer bases and strong adoption in China, Japan and India.
