
Personal Lubricants Market Report Scope & Overview:
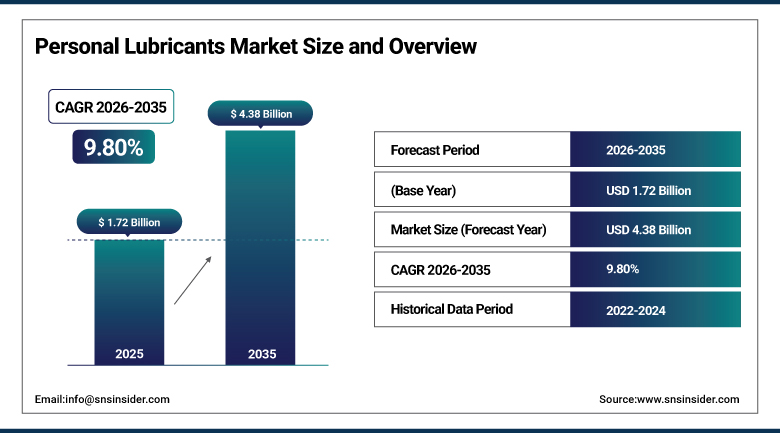
The Personal Lubricants Market was valued at USD 1.72 Billion in 2025 and is expected to reach USD 4.38 Billion by 2035, growing at a CAGR of 9.80% from 2026-2035.
The Personal Lubricants Market is growing steadily as wider openness about sexual wellness, menopause awareness and wellness-oriented marketing move lubricants from a discreet purchase to an everyday self-care product. The market covers water-based, silicone-based, oil-based and hybrid lubricants used to reduce friction and discomfort during intimate activity and to relieve vaginal dryness. Brands sell through e-commerce, pharmacies, supermarkets and specialty stores, and demand is supported by formulation focus on pH balance, osmolality and skin-friendly ingredients, as well as greater inclusion of diverse consumers in marketing.
⮞In February 2025, Reckitt's Durex launched its Afterglow campaign, presenting lubricant use as part of routine intimate wellbeing rather than a discreet purchase. The approach reflects how mainstream brands are widening the buyer base beyond traditional users and normalizing the category in pharmacies and online.
To Get more information Personal Lubricants Market - Request Free Sample Report
Personal Lubricants Market Trends
- Positioning of lubricants as everyday self-care and wellness
- Growth of hybrid and specialty formulations
- Rapid expansion of e-commerce and discreet delivery
- Menopause-related and therapeutic use gaining attention
- Clean-label, pH-balanced and paraben-free formulations
- Greater inclusion of non-binary and LGBTQ+ consumers in marketing
U.S. Personal Lubricants Market Outlook
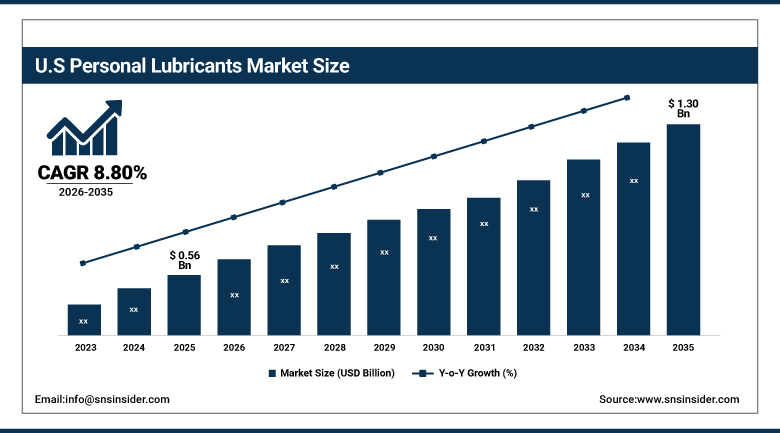
The U.S. Personal Lubricants Market was valued at USD 0.56 Billion in 2025 and is expected to reach USD 1.30 Billion by 2035, growing at a CAGR of 8.80% from 2026-2035.
The U.S. Personal Lubricants Market is the largest national market, supported by high consumer awareness, broad pharmacy and mass retail distribution, strong online sales and the presence of major brands such as Astroglide, K-Y and Durex. Menopause awareness and wellness-oriented marketing are widening the buyer base beyond traditional users, while retailers continue to expand shelf space and premium ranges.
⮞In May 2022, BioFilm, Inc., the U.S. maker of Astroglide, launched ASTROGLIDE X Spray 'n Glide, a premium silicone personal lubricant in a spray format. The launch shows how U.S. brands are extending established names into convenient, higher-priced formats.
Personal Lubricants Market Segment Analysis
- By Type, water-based segment dominated the Personal Lubricants Market in 2025 with 52.50% share; silicone-based segment is the fastest-growing segment, with an estimated CAGR of 11.00% during 2026–2035.
- By Application, personal and sexual wellness use segment dominated the Personal Lubricants Market in 2025 with an estimated 89.00% share; clinical and medical use segment is the fastest-growing segment, with an estimated CAGR of 11.40% during 2026–2035.
- By Distribution Channel, e-commerce segment dominated the Personal Lubricants Market in 2025 with 73.20% share; drug stores segment is the fastest-growing segment, with an estimated CAGR of 10.20% during 2026–2035.
- By End User, women segment dominated the Personal Lubricants Market in 2025 with an estimated 54.00% share; LGBTQ+ segment is the fastest-growing segment, with an estimated CAGR of 10.50% during 2026–2035.
By Type, Water-Based Lubricants Dominate Personal Lubricants Market; Silicone-Based to Register Fastest Growth.
Water-based lubricants dominate the Personal Lubricants Market because they are compatible with condoms and most toys, easy to clean and gentle on skin. Their lower price and wide availability keep them the default choice for first-time and mainstream buyers, and retailers use water-based items as the anchor of private-label ranges. Manufacturers favor the base because formulations are simple to scale, shelf life is long and products fit many sizes and price points, while natural extracts and pH targets allow premium lines to emerge within the category.
Silicone-based products are projected to register the fastest growth as consumers look for longer-lasting glide and as clinical procurement expands. They are not suitable with silicone toys, but their durability in water suits shower and extended use, and brands such as Uberlube and Astroglide support premium pricing. Oil-based products serve specific needs, and hybrid blends that combine the glide of silicone with easier cleanup are gaining attention among buyers who want performance without a difficult cleanup routine. Warming, cooling and flavored variants help brands differentiate premium lines.
By Application, Personal and Sexual Wellness Use Dominates Personal Lubricants Market; Clinical and Medical Use to Register Fastest Growth.
Personal and sexual wellness use dominates the Personal Lubricants Market as consumers use lubricants to improve comfort and pleasure. Greater openness, wellness-oriented marketing and retail visibility have normalized the category, and pharmacists and gynecologists increasingly recommend products as part of routine intimate care. Retailers give the category growing shelf space, and condom manufacturers pair lubricants with their core products in multipacks and promotions, which widens the audience that encounters the category regularly. Educational campaigns by healthcare professionals reduce embarrassment and encourage open conversations about comfort.
Clinical and medical use is projected to register the fastest growth as products for vaginal dryness, painful intercourse, fertility care and post-treatment comfort gain attention. Menopause awareness and clinician recommendations support the segment, and pH-balanced, iso-osmotic and non-spermicidal products are sold through pharmacies, clinics and fertility centers. Companies are seeking medical device clearance for such products, which raises compliance cost but builds trust with healthcare professionals and supports premium pricing over mainstream items. Clinician-endorsed products also reach older consumers through pharmacy recommendations.
By Distribution Channel, E-Commerce Dominates Personal Lubricants Market; Drug Stores to Register Fastest Growth.
E-commerce lead the Personal Lubricants Market because of the availability of discretion, variety, and subscription models. Social networks and discreet packing enable direct-to-consumer players to appeal to younger consumers; meanwhile, marketplaces assist small specialty brands to compete with bigger players. Free returns and samples reduce customer reluctance to try various brands; at the same time, information provided by marketplaces is valuable for manufacturers in terms of understanding preferences concerning ingredients and prices. Subscription plans and social media advertising can be applied to attract repeat customers and keep them loyal.
Drug stores will see the highest growth rates in the Personal Lubricants Market because the pharmacies are seen as trusted channels of purchasing and getting professional advice on intimate products. Co-location with condoms and feminine hygiene products helps to maintain constant demand volumes; moreover, pharmacies provide their clients with such things as loyalty programs, private labels, and consultations. Supermarket and hypermarket formats, along with specialist stores or adult retail channels, have an important share in some markets due to regulations and cultural factors that do not allow selling in other retail locations.
By End User, Women Dominate Personal Lubricants Market; LGBTQ+ to Register Fastest Growth.
Women constitute the major share of Personal Lubricants Market because of their application in the context of comfort, dryness, and menopause, apart from sexual well-being. Modern marketing campaigns directed at women focus on comfort, hydration, and self-care rather than purely sexual messaging, making it acceptable for mature customers to buy the products. Moreover, placing personal lubricants close to feminine care products makes purchase normal and brands targetting mature people invest significantly in soft, pH balanced, and fragrance-free formulas. Brands also perform testing of product names, packaging, and imagery with female panels in order to make products accepted in mass retail.
The Others (LGBTQ+) is expected to be the fastest growing end user segment due to inclusion in the marketing campaigns and broad assortment of products. Brands offering relationships and bodies of different nature, such as Good Clean Love and Pjur create brand loyalty and expand the category, while Sliquid, for example, creates Pride-edition products showing how brands work with this community. Men are still considered a stable base due to the purchase of personal lubricants alongside with condoms and use by couples, which is stimulated by campaigns of big consumer health brands.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
North America |
United States |
80.00 |
|
Asia Pacific |
China |
45.00 |
|
Europe |
Germany |
26.00 |
|
Latin America |
Brazil |
46.00 |
|
Middle East & Africa |
South Africa |
30.00 |
North America Personal Lubricants Market Insights
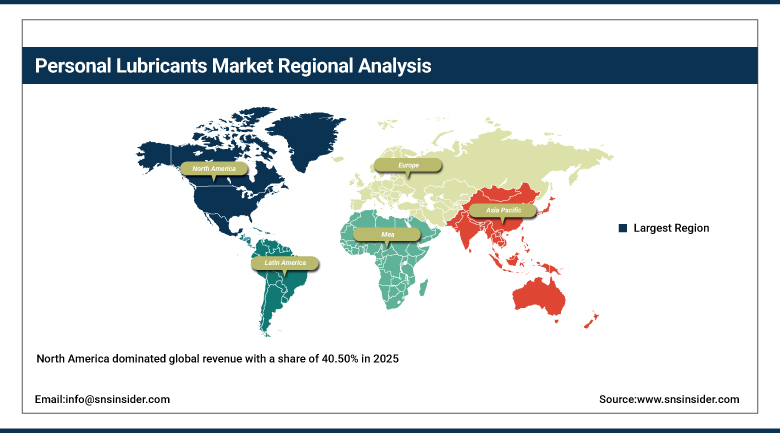
North America dominated global revenue with a share of 40.50% in 2025, supported by high consumer awareness, broad pharmacy and mass retail distribution, strong online sales and the presence of brands such as Astroglide, K-Y and Durex. The United States accounts for most regional demand, with Canada adding volumes through pharmacy chains and provincial health programs. Church & Dwight and BioFilm benefit from established brands, promotional capability and retail relationships that keep the category visible to shoppers.
Menopause awareness and expanded conversations around sexual wellness continue to add buyers, while direct-to-consumer brands and premium, clean-ingredient positioning raise average selling prices. Consolidation among retailers and price competition from private-label products moderate revenue growth, and a mature consumer base limits expansion relative to Asia Pacific. Insurance coverage and health conversations around menopause and sexual wellness are widening acceptance, and retailers continue to expand shelf space and premium ranges. Product education from clinicians and pharmacists strengthens repeat use among established buyers.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Personal Lubricants Market Insights
The Asia Pacific region is forecasted to be the fastest-growing segment at a CAGR of 11.50% between 2026-2035. China is the largest market in the region, owing to discrete accessibility through online portals, followed by Japan, India, and Australia. While the Japanese market is already mature with popular condom and lubricant brands, India and Southeast Asia are rapidly developing through e-commerce and pharmacy distribution routes. Southeast Asian markets benefit from online sales, while South Korea and Taiwan demonstrate increasing demand for premium imported brands through pharmacies and convenience stores.
Urban youth, increasing disposable income, and awareness about sexual and reproductive health constitute the major contributors to market growth in the segment, along with the collaborations of international brands with local distributors and online retailers. The social taboo in certain countries results in limited visibility and advertising on offline channels, and stringent advertising regulation in China adds another challenge, although fast commerce services and public health communication have been boosting the accessibility of the segment. Okamoto Industries of Japan manufacture innovative products with unique textures and packaging.
Europe Personal Lubricants Market Insights
Europe is a mature market where the United Kingdom, Germany and France lead demand through strong pharmacy distribution and open attitudes toward sexual health. Younger consumers in Western Europe are driving demand for body-safe, inclusive products, and campaigns by sexual health charities have helped normalize use across age groups. Premium natural, organic and vegan brands such as Pjur and Yes Yes are headquartered in the region. Public pharmacy networks in Germany are comparatively underpenetrated in this category, which suggests room for clinical-positioned brands.
Cosmetics and medical device regulation requires clear labeling and safety documentation, which favors established manufacturers with compliance resources. Southern and Eastern Europe lag Northern Europe in openness but are gradually converging, giving brands that invest in education and pharmacy distribution room for expansion, while drugstore chains and online marketplaces provide broad assortments that encourage competition between local and international brands. Sustainability expectations also shape packaging choices, with recyclable materials and refill formats under discussion among larger brand owners. Retailers also give prominent placement to pH-balanced and paraben-free items.
MEA & Latin America Personal Lubricants Market Insights
In Latin America, Brazil and Mexico lead through pharmacy chains and growing online sales, with Chile, Colombia and Argentina emerging as developing markets. Growing urban middle classes are more receptive to wellness-oriented marketing, and rising smartphone use and marketplace logistics are improving access to specialist brands and supporting repeat purchases among regular users. Local production is limited, so imports from North America and Europe remain important to assortment in pharmacies. Regional distributors support new brand entry by managing registration, importation and pharmacy listing.
In the Middle East and Africa, South Africa and the Gulf states lead through pharmacies and specialist online retailers, although cultural and regulatory limits restrict marketing in parts of the region. Expatriate communities and tourism-linked retail supply a share of demand in Gulf markets, while Sub-Saharan Africa relies on public health programs and imported brands that often accompany condom distribution. Affordability and distribution gaps limit penetration outside major cities, although awareness campaigns are improving acceptance. Retail modernization and wider pharmacy coverage should lift availability over the forecast period.
Market Dynamics
Growth Drivers: Wellness Positioning, Menopause Awareness and E-Commerce
Wellness positioning is a main driver. Campaigns that present lubricant as everyday self-care have reduced stigma, and retailers now give the category more prominent shelf space. Social media influencers, healthcare professionals and wellness publications now discuss intimate comfort more openly, and this visibility has helped brands reach new demographic groups. Retailers have responded by giving the category more shelf presence and by creating dedicated sexual wellness sections. These shifts raise purchase frequency and basket sizes. Social media influencers, healthcare professionals and wellness publications discuss intimate comfort more openly than in the past, which helps brands reach new demographic groups and raises purchase frequency.
Awareness and e-commerce increase demand. An increasingly large number of women looking for help with dryness, together with the possibility of discreetly placing orders via the internet, will facilitate purchasing for people who do not like buying products at physical stores. The older generation of customers, which used to be less inclined towards using lubricants before, is increasing in terms of its share of the demand as healthcare professionals speak about dryness more openly. Additionally, the internet gives customers a chance to investigate the composition of products and read comments on them anonymously. Increased sexual health awareness across generations will support higher volumes during the forecast period.
Restraints: Social Stigma, Ingredient Concerns and Regulatory Limits
Social stigma still limits advertising and sales in conservative markets, restricting growth potential in several regions. Retailers in several countries limit shelf placement or advertising, and major online platforms apply advertising restrictions that raise the cost of customer acquisition for smaller brands. Cultural barriers also discourage conversation about products, which suppresses trial among potential first-time users. Such barriers keep per-capita use below levels seen in more open markets. Online platforms apply advertising restrictions that raise the cost of acquiring customers for smaller brands.
Ingredient concerns and regulation also constrain the market. Consumers question parabens, glycerin and fragrance, and some products must meet medical device rules, which raises compliance cost for brands. Consumers increasingly scrutinize ingredient lists for glycerin, parabens, fragrances and propylene glycol, and some formulations face questions about effects on vaginal flora. Brands must therefore invest in testing and transparent communication, and products classified as medical devices face additional regulatory costs. Rising compliance requirements favor larger firms and can slow product introductions by smaller brands. Rising compliance requirements favor larger firms and can slow product introductions by smaller brands.
Opportunities: Hybrid Formulations, Therapeutic Products and Emerging Markets
Hybrid and specialist products provide a margin advantage, with warming, organic, pH balanced and long-lasting products being sought by high-value customers. Silicone-water products, cooling and warming effects, and long-lasting effects are popular among those consumers willing to spend more on performance. The collaborations with wellness brands in limited edition products increase visibility among younger consumers. This is an innovation strategy that helps protect brand margins from private label competition. Silicone-water products, cooling and warming effects, and long-lasting effects are popular among those consumers willing to spend more on performance.
Therapeutic products and emerging markets provide further growth. Clinician-recommended moisturizers and lubricants can build trust, while rising incomes and online access open new consumers in Asia, Latin America and Africa. Partnerships with gynecologists, pharmacies and telehealth platforms can help brands reach women experiencing dryness, and expansion into markets with low penetration offers long-term volume growth as incomes rise and cultural attitudes continue to shift. Together these routes can lift both volumes and value per unit over the forecast period. Partnerships with gynecologists, pharmacies and telehealth platforms can help brands reach women experiencing dryness, supporting both volume and value growth.
Recent Developments:
- In August 2025, PH-D Feminine Health launched Femme Glide, a water-based personal lubricant. The product extends the company's feminine health range into intimate comfort and hydration.
- In September 2024, Peptonic Medical launched VagiVital Active Glide, a water-based lubricant focused on deep hydration. The product targets women seeking relief from vaginal dryness.
- In June 2024, Playground launched Pillow Talk, a line of water-based lubricants with clean, vegan and pH-balanced ingredients. The line targets buyers looking for body-safe formulations.
- In August 2023, Sliquid, LLC announced Sliquid Sparkle, a Pride-edition repackaging of its Sliquid H2O lubricant. The edition supports the brand's outreach to LGBTQ+ consumers.
- In July 2022, System JO added Mimosa, Cosmopolitan and Mai Tai flavors to its water-based JO Cocktails line. The flavors extend the brand's flavored lubricant range.
Personal Lubricants Market Key Players are:
- Reckitt Benckiser Group plc
- Church & Dwight Co., Inc.
- LifeStyles Healthcare Pte. Ltd.
- BioFilm, Inc.
- Trigg Laboratories, Inc.
- Good Clean Love, Inc.
- Lovehoney Group
- Mayer Laboratories, Inc.
- Sliquid
- Uberlube
- Peptonic Medical AB
- The Yes Yes Company
- SASMAR
- Toaster Labs
- PH-D Feminine Health
- Pjur Group
- System JO
- Swiss Navy (Empire Labs)
- Pasante Healthcare Ltd.
Personal Lubricants Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 1.72 Billion |
| Market Size by 2035 | USD 4.38 Billion |
| CAGR | CAGR of 9.80% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (Water-Based, Silicone-Based, Oil-Based) • By Application (Personal and Sexual Wellness Use, and Clinical and Medical Use) • By Distribution Channel (E-Commerce, Drug Stores, Supermarkets and Hypermarkets, and Specialty Stores) • By End User (Women, Men, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Reckitt Benckiser Group plc; Church & Dwight Co., Inc.; LifeStyles Healthcare Pte. Ltd.; BioFilm, Inc.; Trigg Laboratories, Inc.; Good Clean Love, Inc.; Lovehoney Group; Mayer Laboratories, Inc.; Sliquid; Uberlube; Peptonic Medical AB; The Yes Yes Company; SASMAR; Toaster Labs; PH-D Feminine Health; Pjur Group; System JO; Swiss Navy (Empire Labs); Pasante Healthcare Ltd. |

Frequently Asked Questions
Key players include Reckitt Benckiser, Church & Dwight, LifeStyles Healthcare, BioFilm, Trigg Laboratories, Good Clean Love, Lovehoney, Sliquid, Uberlube and Peptonic Medical.
Key opportunities include hybrid and specialty formulations, therapeutic products for dryness, and expansion in Asia Pacific and other emerging regions.
The major growth factor is wider acceptance of sexual wellness products, supported by menopause awareness and the growth of discreet online purchasing.
By Type, the Water-Based segment dominated the market in 2025, supported by compatibility with condoms and toys, ease of cleaning and lower prices.
North America dominated the market with a share of 40.50% in 2025, driven by high awareness, broad retail access and strong online sales.
