
Pharmaceutical Fine Chemicals Market Report Scope & Overview:
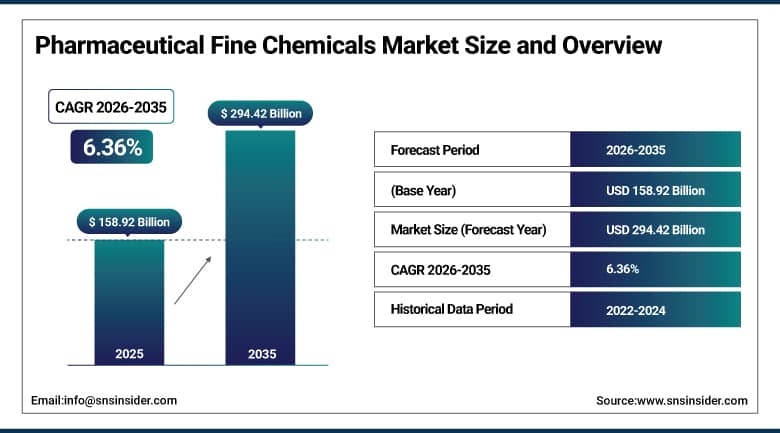
The Pharmaceutical Fine Chemicals Market was valued at USD 158.92 Billion in 2025 and is expected to reach USD 294.42 Billion by 2035, growing at a CAGR of 6.36% from 2026-2035.
The growth of the Pharmaceutical Fine Chemicals Market is attributed to an increase in the demand for active pharmaceutical ingredients, drug intermediates, and high purity chemical compounds. The increasing research and development activities in the field of pharmaceuticals, production of more generic drugs, and the increasing demand for specific treatment options are fueling the need for fine chemicals. Chronic diseases are on the rise, leading to the expansion of drug development and production capabilities of pharmaceutical companies. Outsourcing of the processes of chemical synthesis and manufacturing to specialist manufacturers is aiding pharmaceutical companies in optimizing their operations.
⮞Capacity for small-molecule ingredients is being upgraded in the United States. On July 8, 2026, Evonik announced a USD 100.00 million investment in its Tippecanoe site in Lafayette, Indiana. The plan covers upgraded equipment, including 100 cubic meter reactors, added automation, and new production trains and laboratories for small-molecule active ingredients, with added capacity expected by 2029.
To Get More Information On Pharmaceutical Fine Chemicals Market - Request Free Sample Report
Pharmaceutical Fine Chemicals Market Trends
-
Outsourcing of intermediates and ingredients to specialist custom manufacturers
-
Supply chain diversification away from single-country sourcing
-
Continuous flow chemistry and automation that improve yield and safety
-
High-potency and oncology ingredient capacity with contained suites
-
Peptide, oligonucleotide and complex molecule chemistry
-
Greener solvents, catalysis and waste reduction in synthesis
U.S. Pharmaceutical Fine Chemicals Market Outlook:
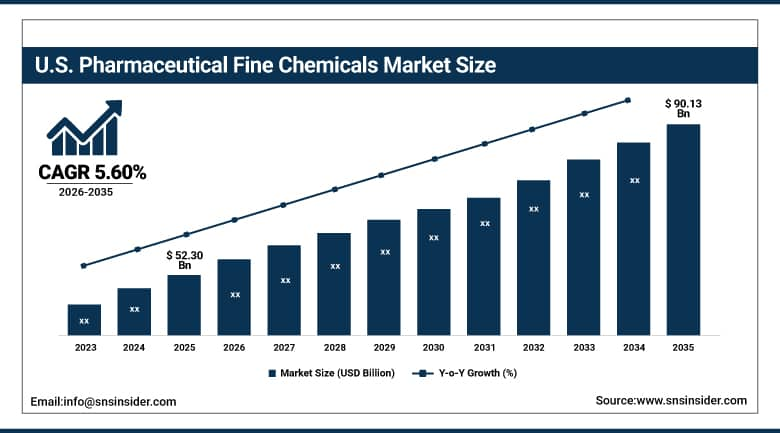
The U.S. Pharmaceutical Fine Chemicals Market was valued at USD 52.30 Billion in 2025 and is expected to reach USD 90.13 Billion by 2035, growing at a CAGR of 5.60% from 2026-2035.
The U.S. Pharmaceutical Fine Chemicals Market is witnessing growth owing to increasing demand for active pharmaceutical ingredients, drug intermediates, and high-purity chemical substances. The presence of extensive pharmaceutical research and development activities, innovation in biotechnology, and growing demand for generic drugs are contributing to the expansion of this market. The increasing trend of developing target-specific drugs and formulations requires quality chemical substances. In addition, domestic manufacturing of pharmaceuticals and the strengthening of the supply chain are leading to production capacity expansion. Contract development and manufacturing organizations are also witnessing gains owing to the outsourcing of chemical substance synthesis and manufacturing by pharmaceutical companies.
Pharmaceutical Fine Chemicals Market Segment Analysis
-
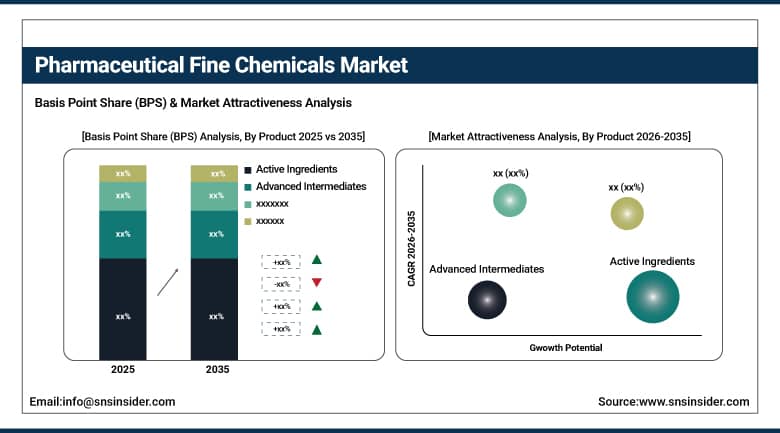
By Product, active ingredients segment dominated the Pharmaceutical Fine Chemicals Market in 2025 with an estimated 41.00% share; advanced intermediates segment is the fastest-growing segment, with an estimated CAGR of 7.60% during 2026–2035.
-
By Type, proprietary segment dominated the Pharmaceutical Fine Chemicals Market in 2025 with an estimated 62.00% share; non-proprietary segment is the fastest-growing segment, with an estimated CAGR of 6.90% during 2026–2035.
-
By Application, cardiovascular segment dominated the Pharmaceutical Fine Chemicals Market in 2025 with an estimated 22.00% share; oncology segment is the fastest-growing segment, with an estimated CAGR of 8.40% during 2026–2035.
By Product, Active Ingredients Dominates Pharmaceutical Fine Chemicals Market; Advanced Intermediates to Register Fastest Growth.
Active ingredients dominate the Pharmaceutical Fine Chemicals Market because they are the highest-value products in the chain and are required for every drug dose. Drug companies purchase these ingredients from specialist manufacturers or make them in-house, and their price reflects complex multi-step synthesis, purity needs and regulatory documentation. Long supply contracts support steady volumes. Regulators require full documentation of starting materials, impurities and process changes, so buyers qualify suppliers carefully and rarely switch them. This creates durable relationships and favors manufacturers with strong audit histories and reliable capacity.
Advanced intermediates are projected to register the fastest growth as drug makers outsource more synthesis steps to specialist partners and look for secure sources outside single regions. Intermediates for oncology, metabolic and antiviral drugs are in demand, and manufacturers with strong process development skills are winning long-term contracts. Suppliers are building process development labs, continuous flow lines and analytical teams to take on more complex synthesis steps. Early involvement in a drug program lets them lock in supply from clinical stage through commercial launch. Partnerships with academic groups also help suppliers access new reaction technology.
By Type, Proprietary Dominates Pharmaceutical Fine Chemicals Market; Non-Proprietary to Register Fastest Growth.
Proprietary fine chemicals dominate the Pharmaceutical Fine Chemicals Market because they are made for patented drugs under custom agreements, with protected processes and higher prices. Innovator companies and their manufacturing partners invest in dedicated capacity, and these programs run for the life of the drug. Quality and confidentiality needs keep this work with a small group of trusted suppliers. Innovator companies often hold the process knowledge and intellectual property, and they pay premiums for secrecy, dedicated suites and technology transfer support. Lifecycle management of branded drugs keeps these programs running for many years. Pricing in these programs is usually set through multi-year agreements with volume commitments.
Non-proprietary products are projected to register the fastest growth as patents expire and generic drug makers need large volumes of standard ingredients and intermediates. Producers in India and China compete on cost and scale, while buyers in Europe and North America look for second sources to reduce supply risk. Rising demand for complex generics and biosimilar-linked chemistry also supports volumes, and buyers are asking for dual sourcing and local inventory to reduce risk from trade disruptions or plant closures. Quality agreements for these products are strict, and suppliers must show consistent batch records for years.
By Application, Cardiovascular Dominates Pharmaceutical Fine Chemicals Market; Oncology to Register Fastest Growth.
Cardiovascular dominates the Pharmaceutical Fine Chemicals Market because heart disease, high blood pressure and cholesterol are common and require lifelong treatment, creating high volumes of statins, beta blockers, anticoagulants and related ingredients. Many of these drugs are generic, so demand is large and stable, and manufacturers rely on dependable chemical supply. Aging populations in North America, Europe and Asia raise prescriptions for these drugs, while fixed-dose combination products require several ingredients per tablet. Procurement is often centralized and tender-based, which rewards scale.
Oncology is projected to register the fastest growth as new targeted therapies, antibody-drug conjugates and high-potency ingredients enter the market. Manufacturers need contained facilities and specialized chemistry, and prices per kilogram are high. Rising cancer incidence and expanding treatment access drive demand for these ingredients. Antibody-drug conjugates, kinase inhibitors and hormonal therapies require highly potent payloads and complex linkers that few plants can handle. Specialist manufacturers with containment experience are capturing a growing share of this work. Clinical trial activity in oncology continues to expand, which keeps early-stage demand for new intermediates high.
Regional Insights
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
Asia Pacific |
China |
41.35 |
|
North America |
United States |
85.34 |
|
Europe |
Germany |
23.56 |
|
MEA |
Saudi Arabia |
31.23 |
|
Latin America |
Brazil |
25.23 |
North America Pharmaceutical Fine Chemicals Market Insights
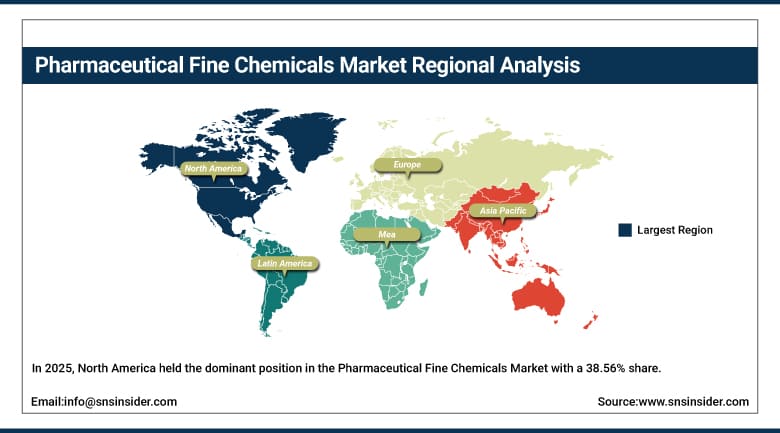
In 2025, North America held the dominant position in the Pharmaceutical Fine Chemicals Market with a 38.56% share owing to the well-developed pharmaceutical industry, high-level R&D, and drug manufacturing infrastructure present in the region. Growing demand for active pharmaceutical ingredients and specialty chemical intermediates is fueling the growth in the region. Presence of biotechnology companies, contract development & manufacturing organizations, and novel drug developers is further contributing to market demand. Besides, rising investment in pharmaceutical innovations, growing demand for complex drugs, and efforts towards improving domestic manufacturing capabilities are helping drive the use of pharmaceutical fine chemicals.
A large innovator drug industry, strong demand for oncology and metabolic drugs, and interest in resilient supply chains support demand. Policies that encourage local drug manufacturing are driving new investment in intermediate and ingredient plants. High labor costs, tough environmental permits and competition from imports moderate growth. Federal programs on drug supply security, tax incentives for new plants and closer buyer-supplier partnerships encourage investment in local capacity. Venture-funded biotechs also buy small, high-value batches for early clinical programs. Strong venture funding for biotech also keeps early-stage orders flowing to specialist chemists.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Pharmaceutical Fine Chemicals Market Insights
The Europe Pharmaceutical Fine Chemicals Market is driven by a well-established pharmaceutical industry, increasing investments in drug research, and rising demand for high-quality active pharmaceutical ingredients and chemical intermediates. Growing production of generic medicines and complex therapies is supporting the need for specialized chemical compounds. Strict quality standards and regulatory requirements are encouraging manufacturers to adopt advanced synthesis technologies and improve production processes. Additionally, increasing outsourcing to contract development and manufacturing organizations is creating opportunities for specialized suppliers. The region's focus on pharmaceutical innovation, supply chain resilience, and high-purity chemical production is expected to support market expansion throughout the forecast period.
Europe is home to well-established custom manufacturers who are known for their excellent quality of products and proficiency in chemistry. Factors such as high energy prices, regulations concerning environment, and age-old factories hinder growth, but policy discussions about security of medicine supply encourage investments in domestic production capacities of important raw materials. European commission is considering policies regarding the securing of supply of critical medicines, and there are many nations that provide incentives for the renovation of manufacturing plants. The need to report on sustainability makes suppliers reduce solvents and emissions.
⮞On September 24, 2026, Siegfried announced a new large-scale drug substance facility in Minden, Germany. The plant has 100 cubic meters of reactor capacity and produces mainly small-molecule active ingredients, combining automation, containment for hazardous materials, gravity-driven material transfer and RFID-based recipe management.
Asia Pacific Pharmaceutical Fine Chemicals Market Insights
Asia Pacific is projected to be the fastest-growing region, at a CAGR of 7.60% during 2026-2035. China, India, Japan, South Korea and Singapore lead regional demand. Divi's Laboratories, Neuland Laboratories, Laurus Labs, WuXi AppTec, Sumitomo Chemical, Zhejiang Huahai and Aurobindo operate in the region. China accounts for about 41.00% of regional demand. Industrial clusters in Gujarat, Telangana, Zhejiang and Jiangsu provide solvents, utilities and trained staff in one place, and governments are funding bulk drug parks. Singapore and South Korea focus on high-value, complex molecules. Skilled labor costs remain well below those of Europe and North America.
There is a great capability in the region in terms of the manufacture of chemicals, chemists, and low costs of production, which makes it an attractive place for global pharmaceutical companies. India is expanding its capability through production incentives and increased custom manufacture, while China continues to be a big provider of intermediaries. Inspection processes, regulations on the environment, and geopolitical diversification strategies slow down growth, but there is high demand from exports. Global pharmaceutical companies are establishing secondary facilities in India and Southeast Asia even as they maintain their presence in China.
⮞On May 27, 2025, Divi's Laboratories signed a long-term supply agreement with a global pharmaceutical company for advanced intermediates and said it plans capital spending of INR 6.50 billion to INR 7.50 billion, funded by staged advance payments from the customer for reserved capacity.
MEA & Latin America Pharmaceutical Fine Chemicals Market Insights
In Latin America, Brazil leads, followed by Mexico, Argentina and Colombia, with regional demand growing at about 6.20% annually. Local drug makers and multinational plants buy intermediates and ingredients, and governments are encouraging local manufacturing to cut import dependence. Currency swings and regulatory approval times shape the market. Brazil, Mexico and Argentina have established generic drug industries, and public procurement programs favor local production. Companies such as TAPI and others are expanding specific API lines to meet this demand. Growth in private hospitals and pharmacy chains is raising demand for local drugs.
In the Middle East and Africa, Saudi Arabia, the United Arab Emirates, Egypt, South Africa and Jordan lead demand, with growth of about 7.00% annually. Governments are funding local pharmaceutical manufacturing and industrial zones, but chemical know-how and skilled labor remain limited, so imports still supply most fine chemicals. Saudi Arabia and the United Arab Emirates are building pharmaceutical clusters with incentives for foreign partners, and Egypt has a large generic industry. Technology transfer deals with global suppliers are an important route to capability.
⮞On July 31, 2026, Mexico Business News reported that TAPI Mexico would invest MXN 140.00 million in its Lerma, State of Mexico API plant, with a first phase this year and a second phase of MXN 60.00 million in 2027. The plant makes 35 APIs, including oncology ingredient 5-fluorouracil. No verified, dated company instance was found for the Middle East and Africa.
Market Dynamics
Growth Drivers: Chronic Disease, New Drugs and Outsourcing
Rising rates of cardiovascular disease, cancer and diabetes increase demand for ingredients, and new drug approvals bring new intermediates. Aging populations raise long-term demand for cardiovascular, diabetes and cancer drugs, which increases consumption of fine chemicals at every step of the chain. Rising use of generics in emerging markets and government programs for universal health coverage increase volumes of standard ingredients, supporting steady demand for large-scale, low-cost producers. Public and private spending on cancer care, diabetes treatment and rare disease therapies continues to rise, widening the range of molecules that require specialist synthesis and giving suppliers many long-term projects to choose from.
Drug makers outsource more chemistry to specialist partners to save capital, and supply chain diversification is adding new qualified sources. Growing numbers of biotech start-ups with no manufacturing plants rely on outside partners for chemistry, which widens the customer base for custom manufacturers. Contract manufacturers also benefit from drug makers focusing capital on research and marketing instead of owning chemical plants. Innovator companies are also launching more drugs through accelerated approval pathways, which compresses timelines and favors partners that can scale from kilograms to tonnes quickly and reliably.
Restraints: Regulatory Burden, Raw Material Costs and Environmental Rules
The strict quality audits, long qualifying period and paperwork make the process expensive and cumbersome for new suppliers. Most of the facilities are old and require extensive renovation to comply with the present standards, and a single audit failure can disrupt supply and erode consumer confidence. Geopolitical tensions and trade barriers may disrupt the supply chain of raw material, and a sharp increase in prices of a few critical solvents/reagents can erode the profit margin under fixed-price contracts. Fluctuations in currency exchange rate and increasing energy costs can affect the economics of suppliers in different regions, making fixed-price contracts difficult to arrange.
Volatile solvent and raw material prices and tough waste rules increase production cost, particularly in Europe and North America. Tight rules on solvent emissions, waste water and hazardous materials increase capital and operating cost, and permits for new sites can take years. Shortages of experienced process chemists and plant engineers in several regions slow technology transfer and limit how fast suppliers can add new capacity. Intellectual property disputes and data integrity findings in some inspections can lead to import alerts, product recalls and loss of customers, creating risk for suppliers with weaker quality systems.
Opportunities: Complex Molecules, Local Supply and Green Chemistry
Peptides, conjugates and high-potency molecules need specialized chemistry and command higher prices. Peptide, oligonucleotide and conjugate chemistry is expanding rapidly, and companies with the right equipment can charge premium prices and secure long contracts. Digital tools such as process analytics and predictive maintenance can raise yield, shorten batch cycles and improve compliance records for regulators and customers. Strategic alliances and acquisitions among custom manufacturers can create larger platforms that offer end-to-end services from route design to commercial supply, attracting biotech and large pharma customers.
Government support for local manufacturing and greener, more efficient processes allows suppliers to win long-term supply contracts. Use of continuous processing, biocatalysis and recycled solvents can cut waste, lower costs and meet customer sustainability goals at the same time. Regional manufacturing hubs close to large markets let suppliers cut lead times and offer safety stock, a service that drug makers are increasingly willing to pay for. Rising need for stable supply of generic essential medicines in Africa and the Middle East creates room for new plants supported by technology partners and development finance. Exports of high-value intermediates from Asia and Europe to the United States create growth for suppliers with strong regulatory records.
Recent Developments
-
September 2026, Siegfried announced a new large-scale drug substance facility in Minden, Germany, with 100 cubic meters of reactor capacity.
-
July 2026, TAPI Mexico announced a MXN 140.00 million investment in its Lerma API plant, including capacity for oncology ingredient 5-fluorouracil.
-
July 2026, Evonik announced a USD 100.00 million investment to upgrade its Tippecanoe site in Lafayette, Indiana.
-
May 2025, Divi's Laboratories signed a long-term supply agreement for advanced intermediates and planned capital spending of INR 6.50 billion to INR 7.50 billion.
Pharmaceutical Fine Chemicals Companies are:
-
BASF SE
-
Lonza Group AG
-
Evonik Industries AG
-
Siegfried Holding AG
-
Divi's Laboratories Limited
-
Neuland Laboratories Limited
-
Laurus Labs Limited
-
WuXi AppTec Co., Ltd.
-
Albemarle Corporation
-
Solvay S.A.
-
Eastman Chemical Company
-
Borregaard ASA
-
W. R. Grace and Co.
-
Sumitomo Chemical Co., Ltd.
-
Olon S.p.A.
-
TAPI
-
Thermo Fisher Scientific Inc.
-
Bachem Holding AG
Pharmaceutical Fine Chemicals Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 158.92 Billion |
| Market Size by 2035 | USD 294.42 Billion |
| CAGR | CAGR of 6.36% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product (Active Ingredients, Advanced Intermediates, and Basic Building Blocks) • By Type (Proprietary and Non-Proprietary) • By Application (Cardiovascular, Oncology, Neurology, Infectious Diseases, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | BASF SE, Lonza Group AG, Evonik Industries AG, Siegfried Holding AG, Cambrex Corporation, Divi's Laboratories Limited, Neuland Laboratories Limited, Laurus Labs Limited, WuXi AppTec Co., Ltd., Albemarle Corporation, Solvay S.A., Eastman Chemical Company, DSM-Firmenich AG, Borregaard ASA, W. R. Grace and Co., Sumitomo Chemical Co., Ltd., Olon S.p.A., TAPI, Thermo Fisher Scientific Inc., Bachem Holding AG |
Frequently Asked Questions
Key players include BASF SE, Lonza Group AG, Evonik Industries AG, Siegfried Holding AG, Cambrex Corporation, Divi's Laboratories Limited, Neuland Laboratories Limited and Albemarle Corporation.
Key opportunities include complex molecules, local supply chains and greener synthesis.
The major growth factor is rising chronic disease and new drug approvals, along with outsourcing of chemistry to specialist manufacturers.
By Product, the Active Ingredients segment dominated the market in 2025 with an estimated 41.00% share, as they are the highest-value products in the chain.
North america dominated the market with a share of 38.56% in 2025
